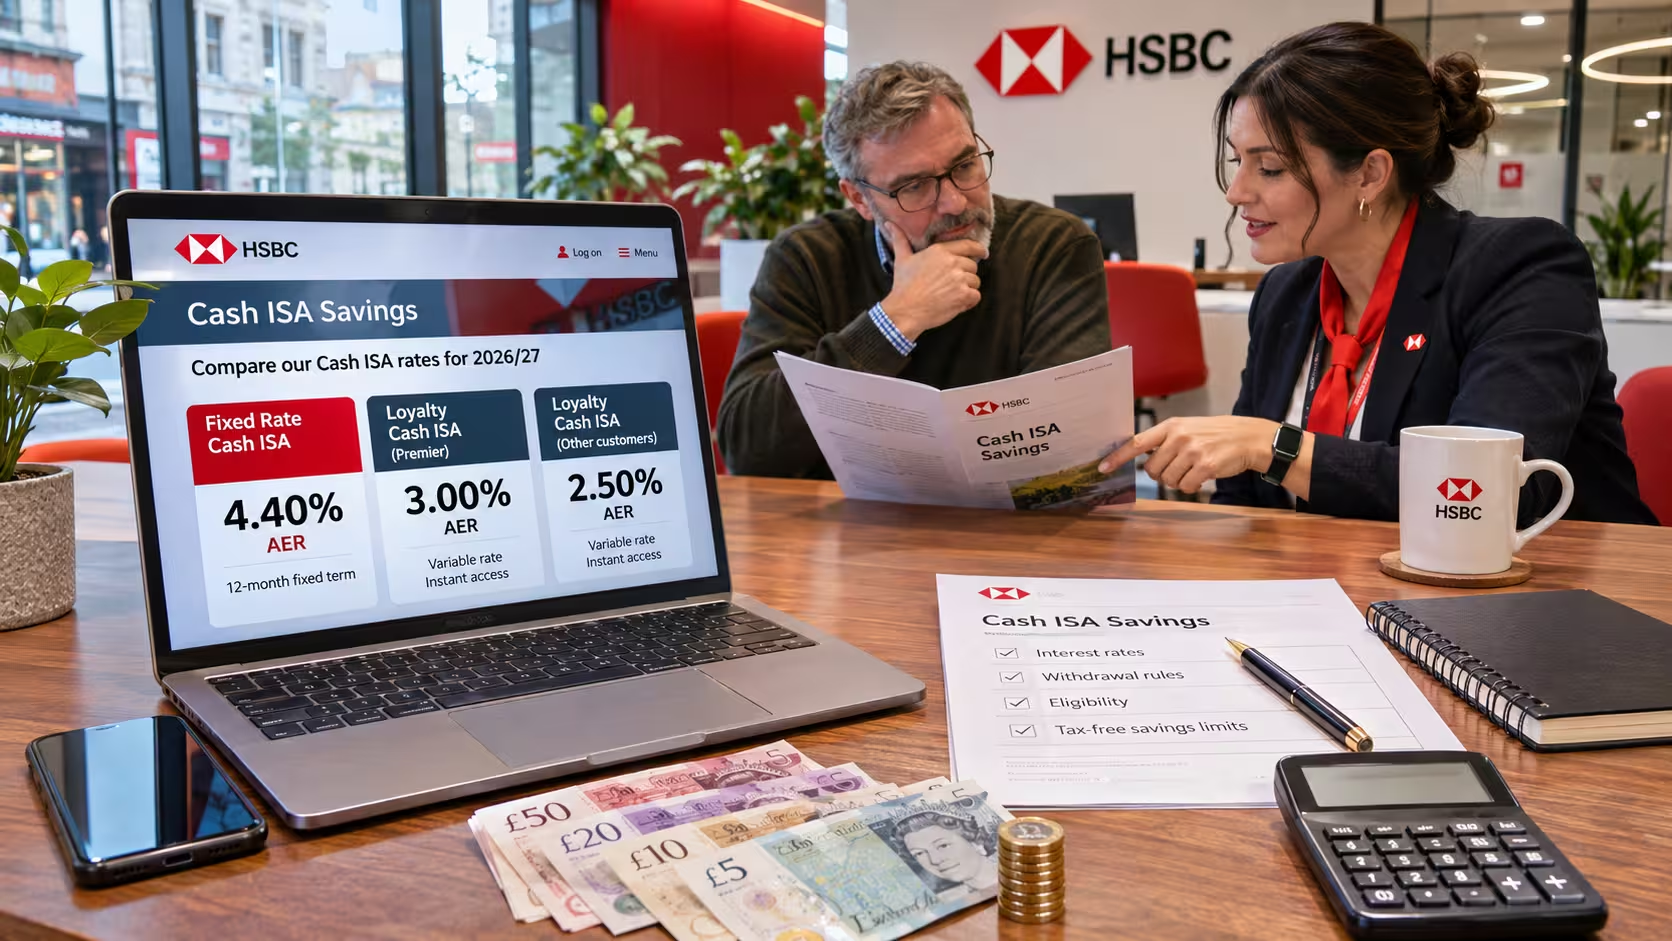
HSBC ISA rates currently range from 2.50% to 4.40% AER, depending on the Cash ISA and the customer’s account type. The HSBC Fixed Rate Cash ISA pays 4.40% AER tax-free, while the Loyalty Cash ISA pays 3.00% AER for HSBC Premier customers and 2.50% AER for customers with other eligible HSBC current accounts.
The main decision is whether a saver prefers the higher guaranteed rate of the fixed account or the easier access provided by the variable-rate Loyalty Cash ISA.
AER stands for Annual Equivalent Rate and provides a standard way to compare savings rates by showing the annual return with compounding taken into account.
Rates on savings products can change or be withdrawn for new applicants, so the live product terms should be checked immediately before opening or transferring an ISA.
What Is The HSBC Fixed Rate Cash ISA?
The HSBC Fixed Rate Cash ISA is designed for savers who can leave their money largely untouched in exchange for a guaranteed return.
The account includes a 30-day funding window followed by a 12-month fixed-rate period.
During the fixed term, partial withdrawals are not allowed, so it is generally better suited to money that is unlikely to be needed at short notice.
Current HSBC Fixed ISA Rate
The HSBC Fixed Rate Cash ISA currently pays 4.40% AER tax-free. The rate is locked in once the account is opened, giving savers certainty over the return for the full fixed period.
Interest is calculated daily and added at the end of the term. This means the return is predictable as long as the account remains open under the agreed conditions and no early closure takes place.
The fixed-rate structure can be useful when savings rates are expected to move lower, because the account continues to pay the agreed rate throughout the term.
The trade-off is reduced flexibility, so the headline rate should be considered alongside the account’s withdrawal restrictions rather than in isolation.
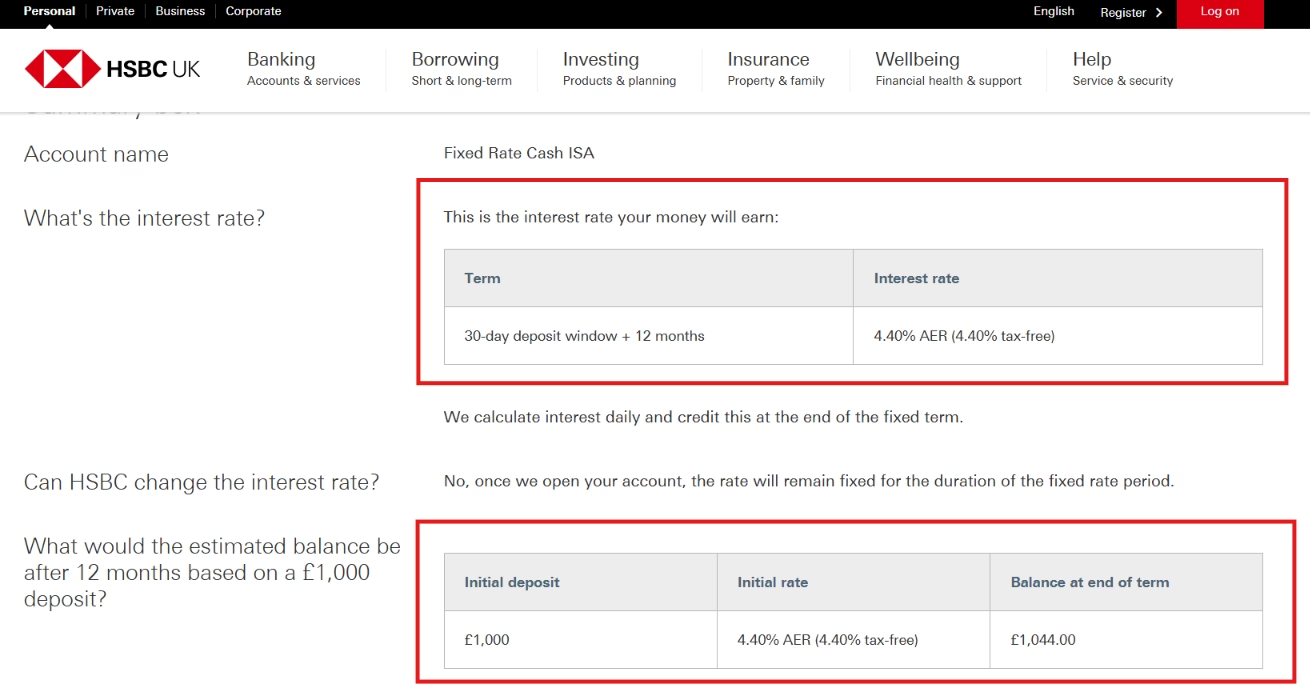
HSBC’s official product page confirms how interest is calculated and how the fixed-term funding period works.
Term, Minimum Deposit And Withdrawal Rules
A minimum of £500 must reach the account, or the relevant transfer instruction must be received, within the first 30 days.
The opening amount can include new subscriptions as well as eligible transfers from existing Cash ISAs or Stocks and Shares ISAs.
The account is less suitable for money that may be required unexpectedly. HSBC does not permit partial withdrawals during the fixed term. Accessing the money requires the account to be closed.
After the 30-day cancellation period, an early closure charge may apply. HSBC caps that charge at the lower of the interest earned or a maximum equivalent to the first 90 days of interest.
Someone closing the ISA before day 90 could therefore receive no interest.
When the fixed term ends, HSBC converts the account into a Loyalty Cash ISA unless another available maturity option is selected.
The replacement interest rate should therefore be reviewed rather than assuming the fixed rate will continue.
What Is The HSBC Loyalty Cash ISA?
The Loyalty Cash ISA is HSBC’s instant-access Cash ISA for eligible current-account customers.
Unlike the fixed product, its interest rate is variable.
HSBC can change the rate over time, including in response to factors such as movements in the Bank of England base rate. Interest is calculated daily and added monthly.
HSBC Premier ISA Rate
HSBC Premier customers currently receive 3.00% AER, equivalent to a quoted tax-free rate of 2.96%.
HSBC’s own illustration shows that £1,000 would become £1,030 after 12 months if the rate remained unchanged and no further deposits or withdrawals were made.
HSBC ISA Rate For Other Current Account Customers
Customers with other eligible HSBC current accounts currently receive 2.50% AER, with HSBC quoting a 2.47% tax-free rate.
On the same £1,000 illustrative balance, HSBC shows a projected balance of £1,025 after 12 months if the variable rate does not change.
Access And Withdrawal Rules
The Loyalty Cash ISA can be opened with £1 and provides instant access. Customers can make fee-free withdrawals without a set limit on the number of withdrawals.
However, it is not a flexible Cash ISA.
That distinction matters because withdrawing money does not restore the part of the annual ISA subscription allowance already used.
For example, a saver who pays £20,000 into a non-flexible Cash ISA and later withdraws £5,000 cannot simply pay that £5,000 back during the same tax year after using the full allowance.
HSBC confirms that a fully subscribed customer would normally need to wait until the next tax year to contribute further funds.
Which HSBC Cash ISA Offers The Better Rate?
The Fixed Rate Cash ISA currently pays the stronger HSBC ISA rate, while the Loyalty Cash ISA offers substantially greater access.
| HSBC Cash ISA | Rate | Access | Minimum Deposit | Best Suited For |
| Fixed Rate Cash ISA | 4.40% AER | Full closure required for early access | £500 | Savers who can leave money untouched for the fixed term |
| Loyalty Cash ISA – Premier | 3.00% AER | Instant access | £1 | Premier customers who want easy access |
| Loyalty Cash ISA – Other Current Accounts | 2.50% AER | Instant access | £1 | Existing HSBC customers prioritising flexibility |
Fixed Rate Cash ISA Vs Loyalty Cash ISA
For money that can remain untouched for the fixed period, the 4.40% rate provides a higher potential return than either Loyalty Cash ISA rate.
The difference becomes clearer when the same balance is compared.
| Account | Rate | Approximate Interest On £10,000 Over One Year |
| HSBC Fixed Rate Cash ISA | 4.40% | £440 |
| HSBC Premier Loyalty Cash ISA | 3.00% | £300 |
| HSBC Loyalty Cash ISA – Other Current Accounts | 2.50% | £250 |
These are simple illustrations rather than guaranteed returns. The Loyalty Cash ISA rates are variable, while actual interest also depends on deposit timing and account activity.
£10,000 Interest Comparison
At the quoted rates, the fixed account produces approximately £140 more annual interest than the Premier Loyalty Cash ISA on £10,000.
Compared with the 2.50% Loyalty rate, the difference is approximately £190.
That additional return has to be weighed against the fixed account’s access restrictions. A saver who may need the money for an emergency, home purchase or other near-term expense could reasonably value instant access more highly than the extra interest.
How Do HSBC ISA Rates Compare With Other UK Cash ISAs?
HSBC’s 4.40% fixed rate is competitive compared with some established providers, but it is not currently a market-leading Cash ISA rate.
Moneyfacts comparison data shows leading fixed Cash ISA rates reaching 5.30% AER, while a leading one-year fixed rate is 5.06% AER. Its highest listed promotional easy-access Cash ISA rate is 4.90% AER. Rates and product availability can change quickly.
HSBC Fixed ISA Rate Comparison
A simple comparison illustrates the difference between HSBC’s 4.40% rate and a 5.06% one-year market rate.
On £10,000:
| Rate | Approximate One-Year Interest |
| 4.40% | £440 |
| 5.06% | £506 |
| Difference | £66 |
The highest rate is not automatically the best account. Minimum deposits, maturity dates, transfer rules and early-access penalties also affect whether a particular ISA is appropriate.
Current Newcastle Building Society ISA rates, for example, include several fixed terms and limited-access products, while Coventry Building Society ISA rates show how relatively small differences in AER can come with substantially different withdrawal restrictions.
HSBC Easy-Access ISA Rate Comparison
HSBC’s Loyalty Cash ISA provides convenient access but its headline rate currently sits below several higher-paying easy-access products in market comparison tables.
Moneyfacts lists promotional easy-access Cash ISA rates as high as 4.90% AER, although some leading rates include temporary bonuses and may operate under different eligibility or transfer conditions.
Which? also shows a range of easy-access products above HSBC’s 3.00% Premier rate.
The wider range of Skipton Building Society ISA rates demonstrates why access conditions should be compared alongside AER. Its current range includes fixed, bonus, limited-access and standard Cash ISA products with different withdrawal arrangements.
For an existing HSBC customer, convenience may have genuine value. For someone whose priority is maximising interest, comparing the wider market before applying could produce a higher return.
Who Is Eligible For An HSBC Cash ISA?
HSBC applies eligibility requirements to both its fixed and Loyalty Cash ISA products.
Applicants generally need to be 18 or over, hold an HSBC current account and provide a National Insurance number if eligible to have one.
To subscribe, the customer must normally be resident in the UK for tax purposes.
Exceptions can apply to qualifying Crown servants working overseas and their spouses or civil partners. The accounts are opened in a sole name rather than jointly.
Age, Residency And Current Account Requirements
The requirement to hold an HSBC current account is particularly important when comparing HSBC ISA rates with providers that allow applications from new customers without an existing banking relationship.
For someone who already uses HSBC, this condition may make account management more convenient. Someone without an HSBC current account should consider whether opening an additional banking product is worthwhile simply to access the ISA.
ISA Transfer Eligibility
HSBC accepts eligible ISA transfers.
For the Fixed Rate Cash ISA, an opening balance can include transfers from existing Cash ISAs or Stocks and Shares ISAs.
HSBC requires the transfer instruction within the account’s initial 30-day funding window and states that transferred money must arrive from the previous ISA provider within the first 70 days.
The Loyalty Cash ISA also allows current and previous tax-year subscriptions to be transferred using the formal ISA transfer process.
A saver intending to preserve the tax-free ISA status of existing money should use the provider-to-provider transfer process rather than withdrawing the money personally and attempting to redeposit it.
What Are The ISA Limits For 2026/2027 And 2027/2028?
The overall annual ISA subscription allowance is £20,000 for the 2026/27 tax year. The money can be placed into one qualifying ISA or divided across different eligible ISA types, subject to their individual rules.
The Lifetime ISA has a separate annual contribution cap of £4,000 within the overall allowance. Readers considering first-home or later-life savings can compare those rules separately when looking at how to open a Lifetime ISA.
2026/2027 ISA Allowance
A saver who contributes the full £20,000 to Cash ISAs during the tax year has used the entire adult ISA allowance.
Alternatively, £15,000 might be placed into Cash ISAs and £5,000 into a Stocks and Shares ISA, again reaching the £20,000 overall total.
Since the 2024 rule changes, eligible adults can generally subscribe to more than one ISA of the same type during a tax year, provided the overall allowance and individual provider conditions are respected.
2027/2028 Cash ISA Limit
The Cash ISA limit will remain at £20,000 from 6 April 2027.
An earlier policy would have reduced Cash ISA subscriptions to £12,000 for many savers.
The Government subsequently reversed that decision. HMRC confirmed that the £20,000 Cash ISA limit would be retained and that the regulations introducing the lower limit would be revoked.
The overall ISA allowance is also confirmed at £20,000 for 2027/28.
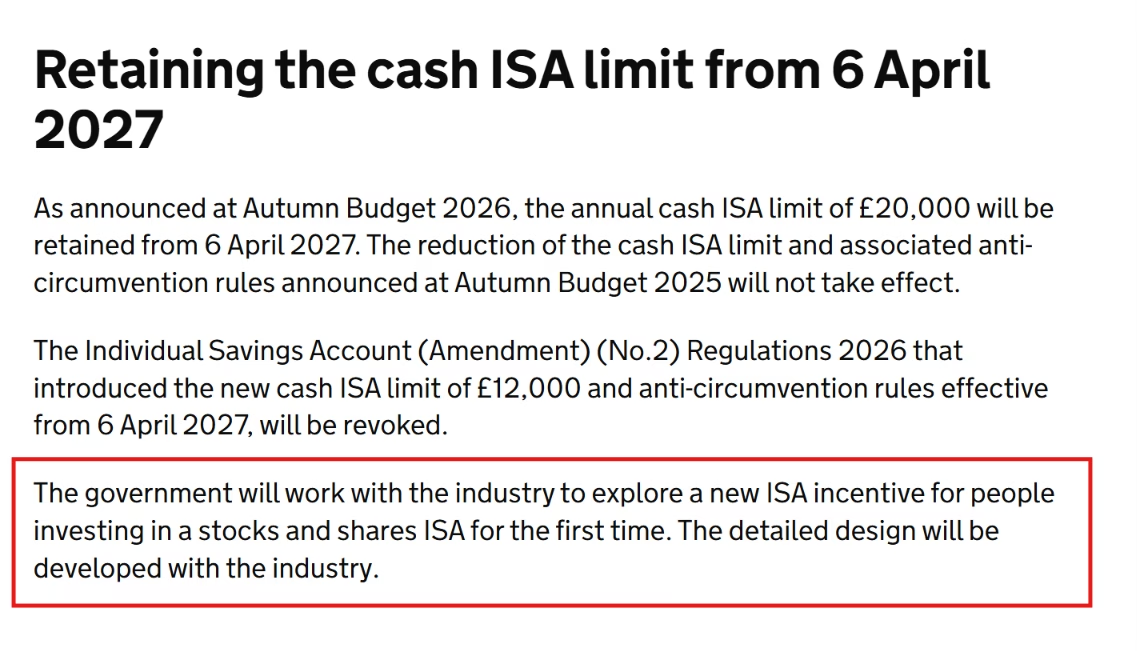
Caption: HMRC confirms that the £20,000 annual Cash ISA limit will remain in place from 6 April 2027.
The policy reversal is significant because older information may still refer to the abandoned £12,000 limit. The wider change in direction, including the proposal for a future first-time investment incentive, is covered in the UK Budget Starter Investment ISA update.
Is An HSBC Cash ISA Worth It?
An HSBC Cash ISA can be worth considering for an existing HSBC customer who values straightforward account management, tax-free interest and a choice between a fixed return and instant access.
Whether it represents the best value depends on how important the interest rate is compared with convenience and access.
- Rate Certainty: The Fixed Rate Cash ISA locks in 4.40% AER for the fixed period, protecting the customer from a rate reduction during that term.
- Access To Savings: The Loyalty Cash ISA offers instant, fee-free withdrawals and may suit money that needs to remain accessible.
- Current Account Requirement: Both products are tied to HSBC current-account eligibility, which may make them less attractive to someone who does not already bank with HSBC.
- Market Competition: Higher Cash ISA rates are currently available elsewhere, particularly for savers willing to compare different providers and account structures.
- Withdrawal Restrictions: Early access to the HSBC fixed ISA requires full closure and may result in an interest charge.
- ISA Flexibility: The Loyalty Cash ISA is instant access but not flexible, so withdrawn money does not automatically restore used ISA subscription allowance.
- Tax-Free Interest: Interest earned within a qualifying Cash ISA is free from UK Income Tax, which may become more relevant for savers whose non-ISA interest exceeds their available tax-free savings allowances.
The clearest case for HSBC is likely to be an existing customer who prefers keeping savings and everyday banking together and finds the available rate acceptable.
Someone focused primarily on obtaining the highest available AER has a stronger reason to compare alternative providers before committing money.
Conclusion
HSBC ISA rates provide two distinct choices for eligible UK savers.
The 4.40% AER Fixed Rate Cash ISA offers the bank’s strongest Cash ISA return but restricts access, while the Loyalty Cash ISA provides instant access at 3.00% AER for Premier customers or 2.50% AER for other eligible current-account customers.
HSBC’s fixed rate is below the strongest rates currently available across the wider market, although the difference may be acceptable to customers who value convenience and already bank with HSBC.
Eligibility, access requirements and transfer rules should be considered alongside the headline percentage.
The annual ISA allowance remains £20,000, and the Government has confirmed that the Cash ISA limit will also remain £20,000 from April 2027.
The most suitable account therefore depends not only on the HSBC ISA rate but also on how long the saver can leave the money untouched and whether a competing provider offers sufficiently better terms to justify switching.
FAQs About HSBC ISA Rates
What Is The Current HSBC ISA Rate?
HSBC currently pays 4.40% AER on its Fixed Rate Cash ISA, 3.00% AER on the Premier Loyalty Cash ISA and 2.50% AER for other eligible current-account customers.
What Is The HSBC Fixed Rate Cash ISA Rate?
The HSBC Fixed Rate Cash ISA currently pays 4.40% AER tax-free, with the rate fixed for the account’s fixed-rate period.
What Is The HSBC Premier ISA Rate?
HSBC Premier customers currently receive 3.00% AER on the Loyalty Cash ISA. The rate is variable and can change.
Does HSBC Offer An Instant-Access Cash ISA?
Yes. The Loyalty Cash ISA provides instant access and fee-free withdrawals, although it is not a flexible ISA.
Can An Existing ISA Be Transferred To HSBC?
Yes. Eligible existing ISA balances can be transferred using HSBC’s formal ISA transfer process, subject to the chosen product’s conditions and funding deadlines.
How Much Can Be Paid Into An HSBC ISA?
The overall adult ISA allowance is £20,000 per tax year. Contributions made to other qualifying adult ISAs during the same tax year also count towards that overall limit.
What Is The Cash ISA Limit For 2027/2028?
The annual Cash ISA subscription limit will remain £20,000 from 6 April 2027 after the Government reversed the previously planned reduction.
More in Finance & Tax
How to Open a Lifetime ISA in 2027?: Step-by-Step Guide, Eligibility and 2026 Rule Changes
Opening a Lifetime ISA in 2027 could help UK residents build a first-home deposit or create a tax-efficient savings fund for later life. The government provides a 25% bonus on eligible contributions, meaning someone who saves £4,000 in a tax year can receive an additional £1,000. However, choosing the right account involves more than finding […]
Skipton Building Society ISA Rates 2027: Latest Cash ISA Rates and 2026 Updates
Skipton Building Society ISA rates currently reach 5.05% AER tax-free on its five-year fixed-rate Cash ISA, while its 15-month fixed account offers 4.90% and its Bonus Cash ISA Saver pays 4.21% variable, including a temporary introductory bonus. For savers preparing their finances for 2027, these rates create different opportunities depending on how long they can […]