Nationwide ISA rates currently reach 4.70% AER tax-free, with the building society offering four fixed-rate Cash ISAs alongside its 1 Year Triple Access ISA.
As of 1 October 2026, Nationwide’s current fixed Cash ISA rates are 4.50% for one year, 4.55% for two years, 4.65% for three years and 4.70% for five years. Its 1 Year Triple Access ISA pays 3.30% AER tax-free variable where no more than three withdrawals are made during the term.
The highest Nationwide ISA rate is therefore attached to the five-year fix, but the highest rate is not automatically the most suitable option. Fixed ISAs substantially restrict access, while the Triple Access ISA provides considerably more flexibility at a lower variable rate.
Rates can also change for new applicants, so savers should check Nationwide’s current Cash ISA rates immediately before opening an account.
What Are the Current Nationwide ISA Rates?
The current Nationwide Cash ISA range is:
| Nationwide Cash ISA | Current rate | Rate type | Access |
| 1 Year Fixed Rate Cash ISA | 4.50% AER | Fixed | Closure required for early access |
| 2 Year Fixed Rate Cash ISA | 4.55% AER | Fixed | Closure required for early access |
| 3 Year Fixed Rate Cash ISA | 4.65% AER | Fixed | Closure required for early access |
| 5 Year Fixed Rate Cash ISA | 4.70% AER | Fixed | Closure required for early access |
| 1 Year Triple Access ISA | 3.30% AER | Variable | Up to 3 withdrawals without rate reduction |
| Triple Access ISA after 4+ withdrawals | 1.05% AER | Variable | Lower rate applies for rest of term |
Nationwide states that the fixed Cash ISA rates shown above took effect on 26 August 2026. Its Triple Access ISA rate currently remains 3.30% AER tax-free.
This distinction matters because some articles published earlier in August still show the previous one-year and two-year Nationwide ISA rates of 4.40% and 4.50%. Those figures were subsequently replaced by the current 4.50% and 4.55% rates.
How Does the Nationwide Fixed Rate Cash ISA Work?
Nationwide combines its one-, two-, three- and five-year terms under its Fixed Rate Cash ISA range.
The minimum amount required to open one is just £1. Once the account has been opened, however, further money cannot simply be added later.
Nationwide requires the Fixed Rate Cash ISA to be funded during the application. The money can come either from an ISA transfer from another provider or from an eligible Nationwide account.
Where someone wants to use both funding methods, Nationwide says two separate ISAs need to be opened.
That funding restriction is one of the most important differences between the fixed product and Nationwide’s Triple Access ISA.
Someone who has £5,000 available now but expects to save another £5,000 gradually over the following six months should therefore understand that the existing Nationwide fixed ISA cannot simply be topped up each month.
Another Cash ISA may be required for later subscriptions, subject to the overall ISA allowance.
UK rules have allowed adults to contribute to more than one ISA of the same type since April 2024, provided the overall subscription limits are followed. We has a separate explanation of whether someone can have more than one ISA in the same tax year.
What Happens if Money Is Withdrawn Early?
A Nationwide Fixed Rate Cash ISA is not an ordinary easy-access savings account.
Money can technically be taken out before maturity, but the account must be closed and Nationwide applies an early-access charge.
| Fixed ISA term | Early-access charge |
| 1 year | 60 days’ interest |
| 2 years | 120 days’ interest |
| 3 years | 180 days’ interest |
| 5 years | 300 days’ interest |
Nationwide warns that an early-access charge can mean someone receives less back than was originally paid into the account. There is no early-access charge where the account is cancelled within the applicable 14-day cancellation period.
The difference becomes particularly important with the five-year ISA. The extra interest rate compared with the one-year account is relatively modest, while the potential early-access charge increases from 60 days to 300 days of interest.
Money required for an emergency fund, upcoming property purchase or another short-term expense may therefore require greater accessibility than a long fixed term provides.
How Much Interest Could a Nationwide Fixed ISA Earn?
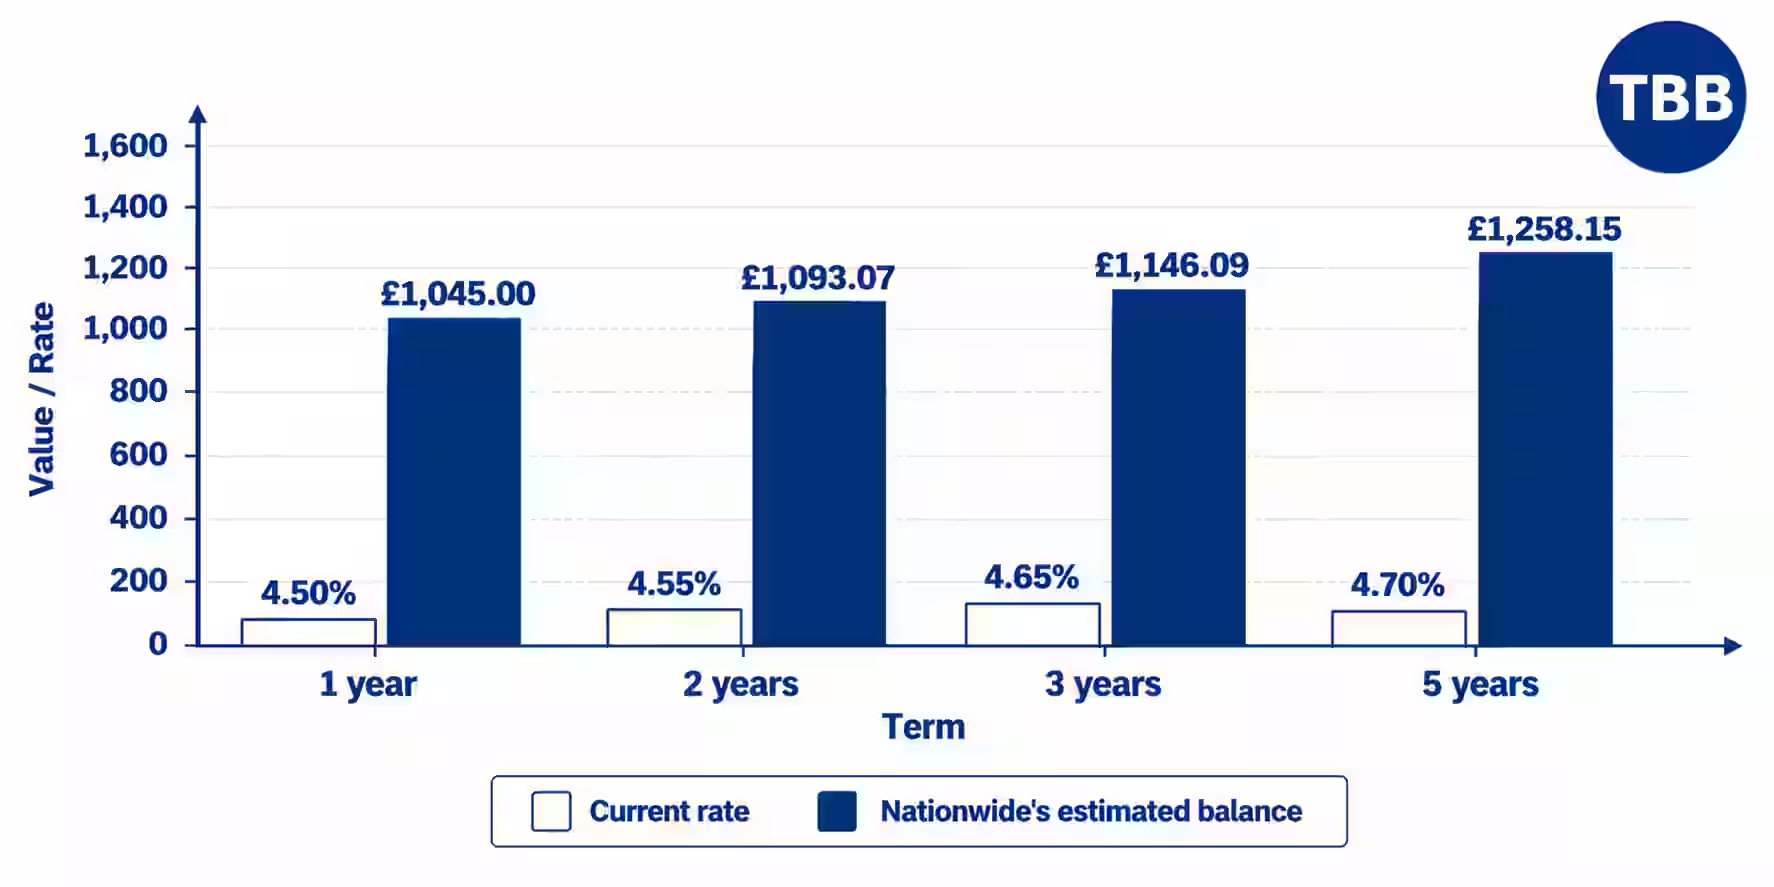
Nationwide provides illustrations based on a £1,000 deposit held for the entire term.
| Term | Current rate | Nationwide’s estimated balance |
| 1 year | 4.50% | £1,045.00 |
| 2 years | 4.55% | £1,093.07 |
| 3 years | 4.65% | £1,146.09 |
| 5 years | 4.70% | £1,258.15 |
The calculations assume the account and money remain in place until maturity. Interest is calculated daily and Nationwide pays it on the anniversary of opening, at the end of the term and when the account closes.
Because these are Cash ISAs, qualifying interest is paid tax-free.
The tax wrapper can become increasingly valuable for people whose taxable savings interest would otherwise exceed their Personal Savings Allowance.
What Is the Nationwide Triple Access ISA Rate?
Nationwide’s other main Cash ISA option is its 1 Year Triple Access ISA.
The current rate is 3.30% AER tax-free variable when no more than three withdrawals are made during the 12-month term.
The important word is variable. Unlike the fixed ISA rates, Nationwide can change the Triple Access ISA interest rate during the term in accordance with its account conditions.
The withdrawal structure is also unusual.
A saver can make up to three withdrawals during the term while retaining the higher rate. Once a fourth withdrawal is made, the rate falls to 1.05% AER tax-free variable for the remainder of the term.
It is therefore better described as a limited-access account than a conventional easy-access Cash ISA.
Is the Nationwide Triple Access ISA Flexible?
Yes. This is an important feature that can easily be missed when comparing Nationwide ISA rates.
Nationwide states that money withdrawn from the Triple Access ISA can be replaced during the same tax year without the replacement using additional ISA allowance.
For example, suppose £10,000 is subscribed and £2,000 is subsequently withdrawn.
Provided the relevant flexible ISA conditions are followed, that £2,000 can be returned during the same tax year without being treated simply as another £2,000 of normal ISA subscriptions.
The withdrawal would still count towards the Triple Access ISA’s withdrawal limit.
Flexibility and withdrawal frequency are therefore two separate rules: replacing withdrawn money may preserve ISA allowance, but making a fourth withdrawal can still trigger the lower interest rate.
Can More Money Be Added to the Triple Access ISA?
Unlike Nationwide’s fixed ISA, the Triple Access ISA accepts further payments during its term, subject to the applicable ISA allowance.
It can be opened with as little as £1, and Nationwide currently permits payments up to the unused annual allowance.
That can make the account more practical for someone accumulating savings gradually rather than depositing one lump sum.
Nationwide also operates its Cash ISAs using a portfolio Cash ISA structure. Different Nationwide Cash ISA products can sit within the same portfolio, allowing the annual allowance to be divided between different products.
For instance, part of an allowance could potentially be placed into a fixed-rate product while another portion remains in a more accessible product.
The overall ISA rules still apply. A detailed breakdown of the current limits is available in our guide to how much can be put into an ISA.
Can an Existing ISA Be Transferred to Nationwide?
Nationwide accepts qualifying ISA transfers.
Using the formal ISA transfer process is important because directly withdrawing money from an existing ISA and then paying it into another account can have different consequences for the ISA allowance and tax wrapper.
Nationwide says a Cash ISA transfer can take up to 15 working days, while transfers involving other types of ISA, such as Stocks and Shares ISAs, can take up to 30 working days. Transfers can take longer where the existing account has a notice period.
Anyone transferring a fixed-rate ISA should also check whether the existing provider charges an early-exit penalty.
Nationwide allows eligible non-Nationwide ISA transfers to be requested during the opening process.
Are Nationwide ISA Rates Competitive With the Wider Market?
Nationwide’s fixed Cash ISA rates are competitive among well-known high-street providers, but they are not currently the highest fixed Cash ISA rates available across the whole UK market.
Moneyfacts’ latest weekly ISA comparison, updated on 29 September 2026, showed the following market leaders:
| Term | Nationwide | Moneyfacts market-leading snapshot | Difference |
| 1 year | 4.50% | 4.90% | 0.40 percentage points |
| 2 years | 4.55% | 5.02% | 0.47 percentage points |
| 3 years | 4.65% | 5.03% | 0.38 percentage points |
| 5 years | 4.70% | 5.25% | 0.55 percentage points |
The Moneyfacts snapshot listed Vanquis Bank at 4.90% for one year and 5.02% for two years, Aldermore at 5.03% for three years and Shawbrook at 5.25% for five years.
These rates can change rapidly and should therefore be treated as a dated market comparison rather than permanent best buys.
Anyone wanting a broader whole-of-market comparison can see our regularly updated guide to the best Cash ISA rates in the UK.
Nationwide may nevertheless appeal to savers who value a low £1 opening amount, branch access or having savings alongside existing Nationwide products.
Rate alone does not establish which account is appropriate. Minimum deposits, access penalties, the ability to make further payments, branch availability, transfer rules and FSCS protection can all affect the practical value of an account.
Is the Nationwide Triple Access ISA Competitive?
The comparison is less favourable on headline rate.
Nationwide currently pays 3.30% AER on the Triple Access ISA, while Moneyfacts reported leading easy-access Cash ISA rates above 5% at the end of September 2026. Its 29 September table placed a promotional Trading 212 Cash ISA at 5.01% AER.
Those products are not necessarily directly equivalent. Promotional bonuses, transfer restrictions, app-only access, withdrawal conditions and other eligibility requirements can materially change the comparison.
Nevertheless, someone primarily interested in maximising the headline variable Cash ISA rate should compare the wider market rather than assuming Nationwide has the highest-paying accessible ISA.
What Happens When a Nationwide Fixed ISA Matures?
At the end of a Nationwide Fixed Rate Cash ISA term, Nationwide says the money will be moved into an instant-access Cash ISA.
The building society contacts the account holder before maturity and explains the interest rate and available options.
Nationwide also operates a maturity rate promise.
If someone tells Nationwide before maturity that the money should be reinvested into another Nationwide Fixed Rate Cash ISA and the applicable rate subsequently changes, Nationwide says it will give the better of the relevant rates, subject to its conditions.
Allowing a fixed ISA to mature without reviewing the destination account can therefore leave savings earning a different rate from the original fix.
How Much Can Be Put Into a Nationwide Cash ISA in 2026/27?
For the 2026/27 tax year, which runs from 6 April 2026 to 5 April 2027, the overall adult ISA allowance is £20,000.
The allowance applies across qualifying adult ISAs rather than giving someone £20,000 for every account.
Therefore, someone contributing £12,000 to Nationwide Cash ISAs and £8,000 to a Stocks and Shares ISA would already have used the full £20,000 adult allowance for the tax year.
Money accumulated inside ISAs in previous tax years does not itself consume the current year’s subscription allowance.
Unused annual allowance also normally expires when the tax year ends rather than carrying forward. We explain the timing in more detail in our guide to when the ISA allowance resets.
What Changes to Cash ISA Limits in April 2027?
This is particularly important for anyone considering Nationwide ISA rates as part of longer-term savings planning.
From 6 April 2027, people below the relevant age-65 threshold will generally be limited to £12,000 of new Cash ISA subscriptions per tax year.
The overall adult ISA allowance remains £20,000.
People covered by the age-65 rules will continue to have a Cash ISA subscription limit of up to £20,000. HMRC confirmed the change in September 2026, and the implementing regulations are due to take effect from 6 April 2027.
This means someone under 65 will no longer generally be able to put the entire £20,000 annual allowance into Cash ISAs from the 2027/28 tax year.
Existing money already held inside a Cash ISA is not simply reduced to £12,000. The change relates to new annual subscriptions.
Are Nationwide Cash ISAs Protected by the FSCS?
Eligible Nationwide deposits are covered by the Financial Services Compensation Scheme.
The current standard deposit-protection limit is £120,000 per eligible person per authorised institution.
One important detail is that Nationwide and Virgin Money now share this protection limit following the transfer of Virgin Money to Nationwide.
That means eligible deposits across Nationwide and Virgin Money are combined when applying the £120,000 individual protection limit, rather than each brand automatically providing a separate £120,000 limit.
This can matter particularly to people who already have substantial savings with both brands.
ISA tax protection and FSCS protection are also different concepts. An ISA protects qualifying interest or investment returns from UK tax, whereas the FSCS provides compensation protection if an eligible authorised financial institution fails.
Can New Customers Open a Nationwide ISA?
Nationwide Cash ISAs are available to qualifying adults aged 18 or over who meet the residence requirements and applicable ISA subscription rules.
There is, however, a distinction worth noting with the Fixed Rate Cash ISA.
Nationwide states that someone who is new to Nationwide must apply for the Fixed Rate Cash ISA in a branch. Existing Nationwide customers can use the available digital channels where eligible.
The Triple Access ISA can currently be opened through Nationwide’s website, banking app, internet bank or branch, subject to eligibility.
Fixed Rate ISA or Triple Access ISA: What Is the Difference?
The key trade-off is between rate certainty and access.
| Feature | Nationwide Fixed Rate ISA | Nationwide Triple Access ISA |
| Current rate | 4.50%–4.70% | 3.30% |
| Rate type | Fixed | Variable |
| Term | 1, 2, 3 or 5 years | 1 year |
| Minimum opening amount | £1 | £1 |
| Further deposits | No, after opening | Yes, subject to allowance |
| Normal withdrawals | No | Yes |
| Early access | Account closes and penalty applies | Up to 3 withdrawals without rate reduction |
| Fourth withdrawal | Not applicable | Rate falls to 1.05% |
| Flexible ISA withdrawals | Fixed-product restrictions apply | Withdrawn money can be replaced in same tax year under flexible rules |
| ISA transfers accepted | Yes | Yes |
For cash that can genuinely remain untouched, the fixed terms provide the higher Nationwide rates and certainty about the return.
Where access is more important, the Triple Access ISA offers greater flexibility but at a lower variable rate.
Neither structure should be selected purely because it carries the Nationwide name or because one has the highest rate within Nationwide’s own range.
The appropriate comparison is between the account’s rate, access conditions, tax treatment and the wider Cash ISA market.
Are Nationwide ISA Rates Worth Checking?
Nationwide’s current Cash ISA range has several advantages: a £1 minimum opening balance, fixed rates of up to 4.70% AER, branch access and the ability to transfer qualifying existing ISAs.
There are also significant restrictions.
The fixed ISAs cannot be topped up once opened, early access requires closure and can trigger up to 300 days’ interest in charges, while the Triple Access ISA’s rate falls sharply following a fourth withdrawal.
Nationwide’s rates are also currently below several whole-of-market leaders, based on late-September comparison data.
The result is that Nationwide’s Cash ISA range is better assessed on the combination of rate, convenience, access, branch service and existing banking arrangements rather than headline interest alone.
Because ISA pricing can move quickly, the rate should always be checked with Nationwide again immediately before an application is submitted.
Frequently Asked Questions
What is the highest Nationwide ISA rate?
The highest currently advertised Nationwide Cash ISA rate is 4.70% AER tax-free, available on its five-year Fixed Rate Cash ISA.
What is Nationwide’s one-year ISA rate?
Nationwide’s current 1 Year Fixed Rate Cash ISA pays 4.50% AER tax-free fixed. Its separate 1 Year Triple Access ISA currently pays 3.30% AER tax-free variable.
What is Nationwide’s two-year ISA rate?
The current Nationwide 2 Year Fixed Rate Cash ISA pays 4.55% AER tax-free fixed.
What is Nationwide’s three-year ISA rate?
The Nationwide 3 Year Fixed Rate Cash ISA currently pays 4.65% AER tax-free fixed.
What is Nationwide’s five-year ISA rate?
Nationwide currently pays 4.70% AER tax-free fixed on its five-year Fixed Rate Cash ISA.
Can money be withdrawn from a Nationwide fixed ISA?
Yes, but the account must normally be closed and an early-access charge applies. The charge ranges from 60 days’ interest for the one-year ISA to 300 days’ interest for the five-year ISA.
How many withdrawals are allowed from the Nationwide Triple Access ISA?
Up to three withdrawals can be made without triggering the lower rate. Once four or more withdrawals are made, the rate falls to 1.05% AER tax-free variable for the rest of the term.
Can an existing Cash ISA be transferred to Nationwide?
Yes. Nationwide accepts qualifying ISA transfers. Cash ISA transfers can take up to 15 working days, while some other ISA transfers can take up to 30 working days.
Is Nationwide’s Cash ISA flexible?
The Triple Access ISA is flexible, allowing qualifying withdrawals to be replaced during the same tax year without the replacement using additional ISA allowance. The fixed-rate product has much tighter access conditions.
How much can be put into a Nationwide Cash ISA in 2026/27?
The overall adult ISA allowance is £20,000 for 2026/27, subject to any contributions made to other adult ISAs during the same tax year.
Will the Cash ISA limit change in 2027?
Yes. From 6 April 2027, the Cash ISA subscription limit will generally fall to £12,000 for people under 65, while the overall ISA allowance remains £20,000. The Cash ISA limit remains up to £20,000 for those covered by the age-65 rules.
More in Finance & Tax
When Does ISA Allowance Reset? UK Rules for 2026/27 and 2027
The ISA allowance resets on 6 April every year, when the new UK tax year begins. For the current 2026/27 tax year, the annual adult ISA allowance is £20,000, covering money contributed between 6 April 2026 and 5 April 2027. Anything left unused when 5 April ends normally disappears rather than carrying into the next […]
Can You Have More Than One ISA? UK Rules for 2026/27 Explained
Yes, you can have more than one ISA in the UK, and since 6 April 2024 you can generally pay into multiple ISAs of the same type during the same tax year. That means someone could have two Cash ISAs, two Stocks and Shares ISAs, or several of each and contribute to them during 2026/27. […]