The ISA allowance resets on 6 April every year. The next reset is 6 April 2027, when eligible UK savers receive a fresh £20,000 annual ISA allowance for the 2027/28 tax year. The final day to use the current 2026/27 allowance is 5 April 2027.
The important development is that the government has cancelled its earlier proposal to reduce the Cash ISA allowance to £12,000 for people under 65. Following Autumn Budget 2026, the government intends to retain the full £20,000 Cash ISA allowance for eligible adults from April 2027.
However, other changes are approaching. The government has announced higher tax rates on ordinary savings interest from April 2027, potentially making tax-free ISAs more valuable for savers whose interest exceeds their tax-free allowances.
We analysed the updated HMRC rules, the October 2026 Budget announcements and practical savings considerations to explain exactly when ISA allowances reset, how much you can contribute, and how to use the two tax years effectively.
When Does the ISA Allowance Reset in 2027?
The next ISA reset takes place on Tuesday, 6 April 2027, at the beginning of the 2027/28 UK tax year.
The ISA allowance follows the UK tax calendar rather than the calendar year or the anniversary of opening an account.
| Tax year | Starts | Ends | Adult ISA allowance |
| 2025/26 | 6 April 2025 | 5 April 2026 | £20,000 |
| 2026/27 | 6 April 2026 | 5 April 2027 | £20,000 |
| 2027/28 | 6 April 2027 | 5 April 2028 | £20,000 |
| 2028/29 | 6 April 2028 | 5 April 2029 | £20,000 under the announced limit freeze |
For example, if someone opened a Cash ISA in October 2026 and contributed £5,000, they would have £15,000 of their overall ISA allowance remaining for the 2026/27 tax year, assuming no other ISA contributions.
On 6 April 2027, their annual contribution allowance resets to £20,000, regardless of when the account was opened.
The existing money does not disappear or become taxable simply because a new tax year has started.
For a detailed explanation of how different contributions are counted, it is useful to understand how much you can put in an ISA across the available ISA types.
What Is the ISA Allowance for 2026/27 and 2027/28?
The standard adult ISA allowance remains £20,000 for both tax years.
Eligible adults can divide that allowance between Cash ISAs, Stocks and Shares ISAs, Innovative Finance ISAs and Lifetime ISAs, subject to the individual rules for each product.
| ISA type | 2026/27 allowance | 2027/28 allowance |
| Cash ISA | Up to £20,000 | Up to £20,000 |
| Stocks and Shares ISA | Up to £20,000 | Up to £20,000 |
| Innovative Finance ISA | Up to £20,000 | Up to £20,000 |
| Lifetime ISA | £4,000 | £4,000 |
| Junior ISA | £9,000 | £9,000 |
| Overall adult ISA limit | £20,000 | £20,000 |
The Cash ISA, Stocks and Shares ISA and Innovative Finance ISA figures are alternative uses of the same overall £20,000 allowance, not three separate allowances.
The Lifetime ISA’s £4,000 limit also forms part of the adult £20,000 total.
Junior ISAs are different because the £9,000 allowance belongs to the child rather than the parent.
Example: Combining Different ISAs
An eligible saver could make the following contributions during 2027/28:
| Account | Contribution |
| Cash ISA | £10,000 |
| Stocks and Shares ISA | £6,000 |
| Lifetime ISA | £4,000 |
| Total | £20,000 |
| Remaining adult allowance | £0 |
Our assessment is that dividing ISA contributions according to financial objectives is usually more useful than treating the £20,000 limit as an amount everyone must invest.
Money required for short-term expenses has different risk and access requirements from money intended for retirement or long-term investment.
Did the Government Cancel the £12,000 Cash ISA Limit for 2027?
Yes. The planned reduction was reversed at Autumn Budget 2026.
The original Autumn Budget 2025 policy proposed reducing the annual Cash ISA subscription limit to £12,000 for most people under 65 from 6 April 2027. Individuals covered by the age-65 exception would have retained the £20,000 limit.
The policy was intended to encourage more people to invest through Stocks and Shares ISAs.
However, the government subsequently reversed this proposal.
On 29 October 2026, HMRC published its tax-free savings newsletter confirming that the £20,000 Cash ISA allowance would be retained and that the regulations introducing the £12,000 reduction would be revoked.
| Policy | Original 2025 proposal | Autumn Budget 2026 position |
| Overall annual ISA allowance | £20,000 | £20,000 |
| Cash ISA limit for under-65s | £12,000 from April 2027 | £20,000 retained |
| Cash ISA limit for over-65s | £20,000 | £20,000 |
| Special restrictions on transfers into Cash ISAs | Planned | Associated restrictions to be revoked |
| New support for first-time investors | Investment encouragement | New incentive being explored |
This is a significant change for savers who prefer the capital stability and straightforward interest payments of Cash ISAs.
It means eligible adults will not be required to place £8,000 into investment-based ISAs simply to use their full annual allowance.
The reversal is announced government policy, with the necessary amending secondary legislation scheduled for November 2026.
The government is also exploring new incentives for first-time ISA investors, although the detailed design has not yet been confirmed.
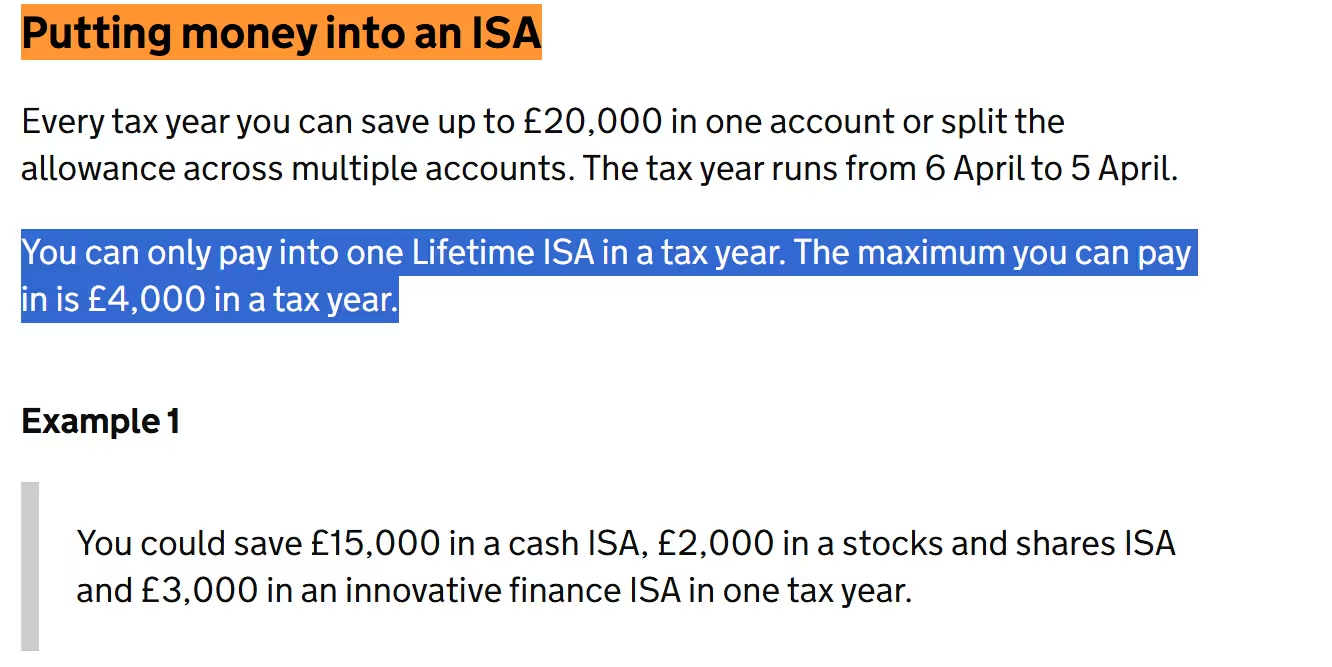
HMRC’s October 2026 tax-free savings newsletter confirms that the £20,000 Cash ISA limit will be retained from 6 April 2027.
What Happens to Unused ISA Allowance on 6 April?
Unused standard ISA allowance normally expires at the end of the tax year.
It cannot be carried into the following tax year.
Consider someone who contributes £7,000 during 2026/27.
| Calculation | Amount |
| Annual ISA allowance | £20,000 |
| Contributions already made | £7,000 |
| Unused allowance before 6 April 2027 | £13,000 |
| Amount carried into 2027/28 | £0 |
| Fresh allowance on 6 April 2027 | £20,000 |
The saver does not receive £33,000 in 2027/28 because they failed to use the previous year’s allowance.
The unused £13,000 expires.
However, that does not mean everyone should automatically transfer their remaining savings into an ISA before 5 April.
From a financial planning perspective, expensive borrowing, insufficient emergency cash reserves and unsuitable investment products may be more important considerations than maximising the annual tax allowance.
The advantage of understanding whether you can contribute £20,000 to an ISA every year is that it allows savers to plan contributions over several tax years rather than making rushed decisions.
Can You Put £20,000 Into an ISA on 5 April and Another £20,000 on 6 April?
Yes, potentially.
Because the dates fall into separate UK tax years, an eligible saver could make contributions in both periods without exceeding the standard £20,000 annual limit, provided all relevant ISA rules and provider deadlines are satisfied.
For example:
| Contribution date | Tax year | Contribution |
| 5 April 2027 | 2026/27 | £20,000 |
| 6 April 2027 | 2027/28 | £20,000 |
| Total | Two tax years | £40,000 |
This can be useful for someone who receives a substantial bonus, business distribution, inheritance or other legitimate personal funds around the end of the financial year.
The important distinction is that the ISA allowance is annual. The two contributions do not represent permission to invest £40,000 within one tax year.
There is also a practical banking consideration: payments must meet the provider’s processing arrangements. Simply initiating a transfer near midnight does not guarantee that it will be treated as a contribution for the earlier tax year.
What Time Does the ISA Allowance Reset on 6 April?
The new ISA tax year begins at midnight UK time between 5 and 6 April.
In principle, contributions made during the new tax year count towards that year’s allowance.
However, ISA providers may have their own processing cut-offs, especially for deposits made through bank transfers, debit cards, standing orders or investment platforms.
The distinction matters because a contribution submitted late on 5 April may not necessarily be accepted before the provider’s deadline.
Our practical recommendation is to verify the payment cut-off directly with the provider and avoid leaving substantial contributions until the final evening.
A sensible pre-deadline checklist is:
- Check how much you have contributed across every ISA since 6 April 2026.
- Confirm the remaining allowance.
- Check whether your provider accepts deposits on 5 April.
- Verify the provider’s final processing deadline.
- Allow for any bank-transfer or account-verification delays.
- Keep a record of the accepted subscription and date.
- Check the new tax-year allowance before contributing again.
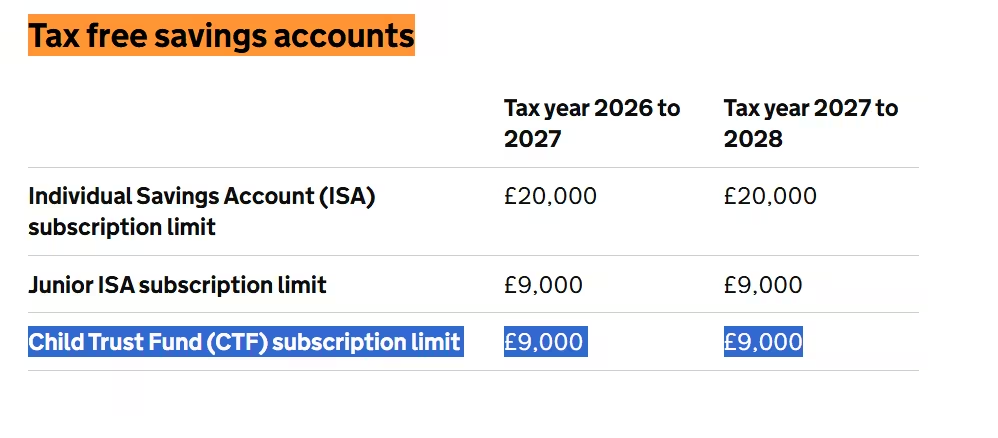
The official HMRC ISA guidance explains how the 6 April to 5 April tax year determines the annual £20,000 contribution allowance.
Does an Existing ISA Balance Reset to Zero in April?
No. The annual contribution allowance resets, but the money already held inside the ISA remains there.
Consider someone with the following savings:
| Source | Value |
| ISA savings accumulated in previous years | £80,000 |
| Additional contributions during 2026/27 | £20,000 |
| Total before interest or investment growth | £100,000 |
When 6 April 2027 arrives, the existing £100,000 does not disappear.
The account retains its ISA tax treatment, and the saver may receive a fresh annual allowance for eligible new contributions.
There is no general £20,000 ceiling on the lifetime value of an ISA.
An account can accumulate considerably more than £20,000 through contributions made in different tax years, interest, dividends and qualifying investment growth.
That is one reason to compare Cash ISA interest rates and product conditions periodically rather than assuming an existing account will remain competitive indefinitely.
Does Interest Earned Inside an ISA Count Towards the Annual Allowance?
No.
Interest generated inside a Cash ISA does not consume additional annual ISA subscription allowance.
The same general principle applies to eligible investment growth and returns inside Stocks and Shares ISAs.
For example, suppose a saver contributes £20,000 to a Cash ISA and earns an illustrative 4% AER over a full year.
| Item | Amount |
| Initial contribution | £20,000 |
| Illustrative annual return at 4% | £800 |
| Approximate balance after one year | £20,800 |
| Additional ISA allowance used by interest | £0 |
The £800 is interest generated within the ISA, not another personal contribution.
Therefore, the account can hold more than £20,000 without breaching the subscription rules.
The 4% interest rate is an illustration rather than a claim about currently available rates. Actual returns depend on the provider, account conditions and any rate changes.
Will Higher Savings Tax Rates Make ISAs More Valuable in 2027?
Potentially, particularly for savers whose interest from ordinary savings accounts exceeds their tax-free savings allowances.
At Autumn Budget 2026, the government announced further increases to the Income Tax rates applying to savings interest from April 2027.
Under the latest announced rates:
| Savings Income Tax rate | 2026/27 | Proposed 2027/28 |
| Basic rate | 20% | 24% |
| Higher rate | 40% | 44% |
| Additional rate | 45% | 49% |
| Interest earned within an ISA | 0% | 0% |
The 2027/28 percentages reflect the Autumn Budget 2026 proposal and require the relevant legislation to take effect.
This is a particularly important development because earlier tax announcements had suggested smaller increases. The latest Budget figures should therefore take priority when evaluating 2027 savings tax planning.
How Much Tax Could a Cash ISA Save?
The Personal Savings Allowance (PSA) generally permits eligible taxpayers to earn a certain amount of savings interest without paying Income Tax.
The standard allowances are:
| Taxpayer category | Personal Savings Allowance |
| Basic-rate taxpayer | £1,000 |
| Higher-rate taxpayer | £500 |
| Additional-rate taxpayer | £0 |
Some people with low non-savings income may qualify for the separate starting rate for savings, so these figures do not describe every taxpayer’s circumstances.
Consider a higher-rate taxpayer with £40,000 in cash savings, earning an illustrative 4% annual interest.
If all £40,000 sits in ordinary savings accounts:
- Gross annual interest: £1,600
- Personal Savings Allowance: £500
- Potentially taxable interest: £1,100
- Illustrative tax at the proposed 44% rate: £484
Now consider putting £20,000 in a Cash ISA and keeping £20,000 in an ordinary savings account.
| Calculation | All ordinary savings | Half held in a Cash ISA |
| Total savings | £40,000 | £40,000 |
| Interest earned at 4% | £1,600 | £1,600 |
| Interest sheltered by an ISA | £0 | £800 |
| Ordinary savings interest | £1,600 | £800 |
| Interest above £500 PSA | £1,100 | £300 |
| Tax at 44% | £484 | £132 |
| Illustrative tax saved | — | £352 |
In this simplified example, using a Cash ISA could reduce the annual tax on interest by £352, assuming the proposed 2027/28 rate applies, equal returns on both accounts, full-year balances and no other savings income or relevant tax adjustments.
This is not a guaranteed saving for every household. Someone whose ordinary savings interest remains within their available allowances may pay no interest tax even without an ISA.
Our assessment is that higher savings tax rates strengthen the case for evaluating ISAs as part of a broader tax-efficient savings strategy, especially for higher-rate taxpayers and people with substantial cash holdings.
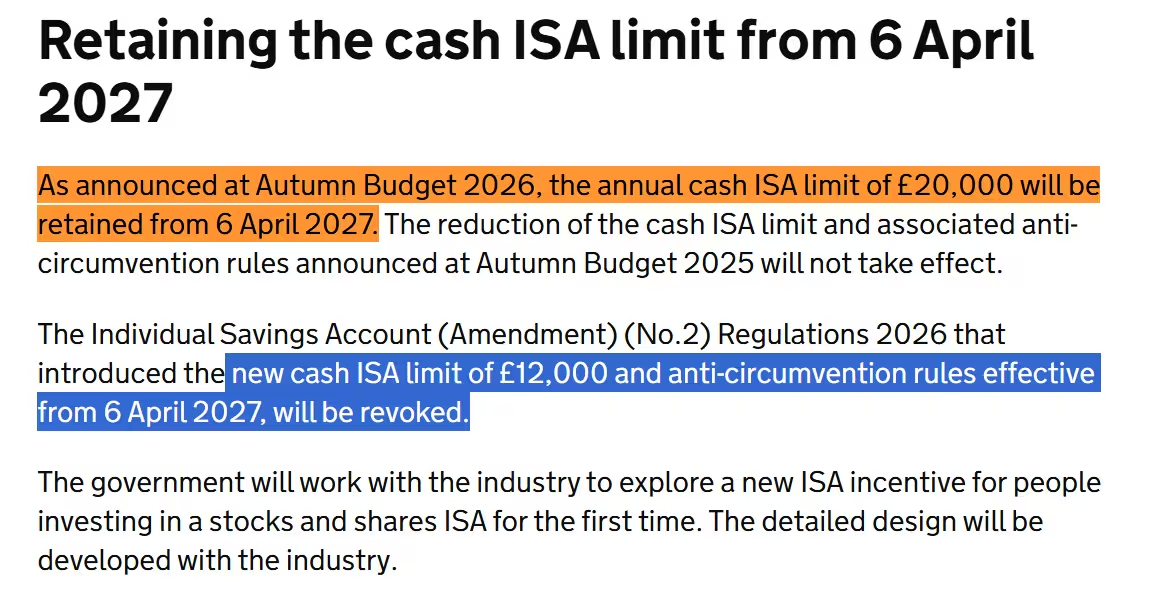
The government’s Budget 2026 rates and allowances table shows the proposed increase in savings Income Tax rates from April 2027.
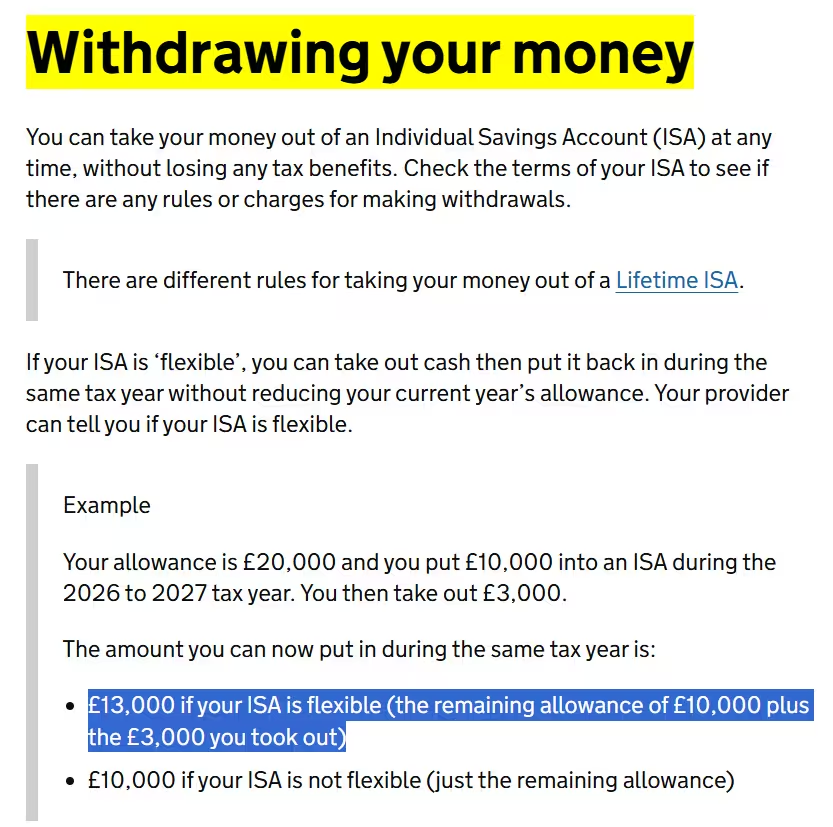
Do ISA Withdrawals Affect the Allowance Before the Reset?
They can. The outcome depends on whether the account is a flexible ISA.
A flexible ISA allows qualifying withdrawals to be replaced under the flexible-account rules without necessarily using additional annual subscription allowance.
A non-flexible ISA does not provide the same replacement facility.
For example, assume someone contributes £10,000 during 2026/27 and subsequently withdraws £3,000.
| Calculation | Flexible ISA | Non-flexible ISA |
| Annual allowance | £20,000 | £20,000 |
| Original contribution | £10,000 | £10,000 |
| Withdrawal | £3,000 | £3,000 |
| Permitted further contributions under the example | £13,000 | £10,000 |
With the flexible ISA, the £13,000 includes replacement of the £3,000 withdrawal and the £10,000 remaining standard allowance.
The replacement rules have important conditions.
Money withdrawn from a flexible ISA generally needs to be replaced within the same tax year to benefit from the relevant replacement treatment. Special rules also govern previous-year ISA funds and which account can receive the replacement.
Not every Cash ISA is flexible.
A product described as easy access is not automatically a flexible ISA, and withdrawal charges or restrictions can still apply to particular products.
Savers should confirm the account’s terms before removing money, particularly near 5 April.
Does Transferring an ISA Use Your New £20,000 Allowance?
A correctly completed ISA transfer generally allows existing ISA savings to move between eligible providers or accounts without treating previous years’ ISA money as a new personal contribution.
The key requirement is to use the formal ISA transfer process.
For example, someone may have accumulated £60,000 in Cash ISAs over several previous tax years.
If they find another provider offering a more suitable rate or better access terms, they may be able to transfer that money through the new provider.
The £60,000 does not automatically consume the new £20,000 allowance simply because the transfer takes place in 2027/28.
However, taking the £60,000 out personally and then paying it into another ISA is different. Outside the applicable flexible ISA replacement rules, the new payment could be treated as a fresh subscription and exceed the annual limit.
Our approach is to distinguish between two decisions: choosing a competitive provider for old ISA balances, and deciding how to use the current tax year’s new contributions.
Savers assessing specific building societies can compare Coventry Building Society ISA products and Newcastle Building Society ISA options, including their transfer acceptance policies, interest structures and withdrawal conditions.
Can You Contribute to More Than One ISA in 2027?
Yes, subject to the applicable account rules.
Following the changes introduced in April 2024, eligible savers can generally subscribe to multiple Cash ISAs, Stocks and Shares ISAs or Innovative Finance ISAs during a single tax year.
However, the total annual subscription limit still applies across all adult ISA accounts combined.
Someone could, for example, contribute:
| Account | Contribution |
| Cash ISA with provider A | £6,000 |
| Cash ISA with provider B | £4,000 |
| Stocks and Shares ISA | £10,000 |
| Total | £20,000 |
They would have used their full annual allowance.
Opening additional accounts does not create extra ISA allowances.
Lifetime ISAs have a separate restriction: savers can only subscribe to one Lifetime ISA in a tax year, subject to the £4,000 limit.
For people considering app-based providers, checking the safety and protection of a Trading 212 Cash ISA can be useful alongside reviewing interest rates, fees, eligibility and account terms.
Does the Lifetime ISA Allowance Reset in April 2027?
Yes. The Lifetime ISA contribution limit also resets with the UK tax year on 6 April.
Eligible savers can contribute up to £4,000 a year to a Lifetime ISA and potentially receive a 25% government bonus, worth up to £1,000 annually.
The £4,000 contribution counts towards the normal adult ISA allowance of £20,000.
For example, someone contributing £4,000 to a Lifetime ISA during 2027/28 would have £16,000 of their standard adult ISA allowance remaining.
Lifetime ISAs have eligibility conditions, including opening the account before age 40 and ordinarily stopping contributions at age 50.
Withdrawals that do not meet the qualifying conditions may attract a government withdrawal charge, so the account is not equivalent to an ordinary easy-access Cash ISA.
A separate government proposal for a new first-time-buyer savings product is under development, but savers should not assume an unlaunched product has replaced the current Lifetime ISA.
Does the Junior ISA Allowance Also Reset on 6 April?
Yes.
The Junior ISA limit is £9,000 for both 2026/27 and 2027/28.
It is an allowance for each eligible child, rather than an additional allowance belonging to the parent.
For example, two eligible parents could each use their adult £20,000 ISA allowances while also contributing to a child’s separate Junior ISA, subject to all relevant rules and available funds.
A Junior ISA belongs to the child. It generally cannot be withdrawn before age 18, apart from limited exceptions.
Family savings decisions should therefore account for whether the money may be needed before the child reaches adulthood.
How Should Self-Employed People and Business Owners Plan the 2027 ISA Reset?
For company directors, freelancers and sole traders, ISA planning often involves more than selecting the highest advertised interest rate.
Personal income can fluctuate significantly between tax years, particularly when money comes from dividends, client payments, business disposals or irregular contracts.
An ISA can provide a tax-efficient place for eligible personal savings, but a personal ISA is not a substitute for a business bank account.
Company funds cannot simply be treated as an owner’s personal savings without the appropriate legal and tax treatment.
From our analysis, three issues matter particularly for entrepreneurs.
- First, distinguish business cash flow from personal savings: Money needed to pay suppliers, VAT, Corporation Tax or other business liabilities should not automatically be committed to long-term personal investments.
- Second, consider the timing and taxation of personal income: A director receiving a lawful dividend or salary payment may decide to contribute part of the net proceeds to an ISA. The ISA does not remove tax obligations arising from the underlying salary or dividend.
- Third, assess retirement savings alongside cash reserves: Some business owners benefit from maintaining accessible ISA funds while contributing to pensions through separate arrangements.
The choice between drawing on pensions and ISAs can become especially important as retirement approaches. Our analysis of pension and ISA withdrawal strategies explores how the tax treatment of the two products can differ.
There is no universal financial advantage in using the ISA allowance immediately.
For someone with uncertain self-employment income, keeping an adequate emergency reserve may be more important than committing funds to an account with withdrawal restrictions.
What Should You Check Before Choosing a Cash ISA for 2027?
The tax wrapper is only one part of a good savings decision.
A Cash ISA paying a lower rate than a comparable ordinary savings account may still be suitable if the interest tax exemption is valuable to the saver.
Conversely, someone with little taxable savings interest may benefit more from a competitive ordinary savings account, depending on the rates and account terms.
We recommend comparing the following:
| Factor | What to check |
| Interest rate | AER, whether fixed or variable, and any promotional bonus |
| Withdrawal access | Instant access, notice periods or early-access penalties |
| ISA flexibility | Whether withdrawals can be replaced under the flexible ISA rules |
| Transfer facility | Whether existing ISA savings can be transferred in |
| Account restrictions | Minimum deposits, balances and eligibility requirements |
| FSCS protection | The relevant deposit-protection arrangements and shared banking licences |
| Interest payment | Monthly, annually or at maturity |
| Tax position | Whether ordinary savings interest may exceed available tax-free allowances |
Savers looking for competitive products can review Martin Lewis’s best ISA rate comparisons, while checking current provider terms directly before applying.
Rates can change, and a product that was competitive when an article was published may no longer be available on the same terms.
What Changes for ISA Savers From 6 April 2027?
The most important distinction is between measures that are being retained, cancelled and introduced.
| Rule or development | Position for 2027/28 |
| Annual ISA reset date | 6 April 2027 |
| Standard adult ISA allowance | £20,000 |
| Cash ISA limit | £20,000 retained under Budget 2026 policy |
| Proposed £12,000 limit for under-65s | Cancelled |
| Junior ISA allowance | £9,000 |
| Lifetime ISA contribution limit | £4,000 |
| Ordinary savings tax rates | Higher rates announced for April 2027 |
| National Insurance number requirement | Additional ISA subscription information requirements take effect |
| New first-time Stocks and Shares ISA incentive | Being explored; final details not confirmed |
One administrative point worth checking is the National Insurance number requirement.
From 6 April 2027, ISA managers are required to obtain a National Insurance number from eligible investors making subscriptions, or a declaration that the investor is not eligible for one.
This may be relevant to people holding older accounts where their provider needs to update its customer records.
HMRC’s official ISA manager guidance confirms the National Insurance number requirement applying to ISA subscriptions from 6 April 2027.
What Is Our Assessment of the Best ISA Reset Strategy for 2027?
Our analysis suggests that the most effective strategy depends on the amount available to save, the time horizon, expected tax treatment and the need for accessible funds.
| Saver profile | Planning approach worth considering |
| Saver with unused 2026/27 allowance | Review available funds and provider deadlines before 5 April |
| Higher-rate taxpayer with substantial savings | Calculate potential tax on ordinary interest and compare Cash ISAs |
| Saver with several Cash ISAs | Review total contributions and transfer terms |
| First-time buyer | Compare Lifetime ISA eligibility, bonuses and withdrawal restrictions |
| Long-term investor | Evaluate investment risk, diversification and Stocks and Shares ISA costs |
| Retiree | Assess withdrawals alongside pension taxation and liquidity |
| Company director | Separate personal contributions from company finances |
| Parent saving for a child | Review the child’s £9,000 Junior ISA allowance |
The essential point is that an ISA allowance is a tax opportunity, not an investment performance guarantee.
An ISA earning 3% interest does not automatically become a better financial product than a comparable non-ISA account offering a higher after-tax return. Likewise, Stocks and Shares ISAs can experience investment losses despite their tax advantages.
The right decision is based on the combination of net return, security, access, tax position and individual financial goals.
Final Thoughts: When Should You Use Your ISA Allowance?
The ISA allowance resets on 6 April each year. For 2027, the standard adult allowance remains £20,000, and the government has reversed its previous plan to reduce the Cash ISA limit for people under 65.
Unused 2026/27 allowance normally expires on 5 April 2027, but existing ISA balances retain their tax-efficient status.
For savers, the more important financial question is not simply when the allowance renews, but whether using it supports their wider financial objectives.
The proposed 2027 increases in savings Income Tax rates may make Cash ISAs more attractive for some higher-rate and additional-rate taxpayers. Nevertheless, rates, liquidity, account protection and personal circumstances remain essential considerations.
Our overall assessment is that planning ahead of the deadline, reviewing the latest rules and comparing actual after-tax returns offers greater value than rushing to use an allowance without a clear purpose.
Information reviewed against official UK government publications available in November 2026. Tax rules and proposals may change. This article provides general financial information rather than personalised investment or tax advice.
Frequently Asked Questions
Does the ISA allowance reset every year?
Yes. The standard ISA allowance resets every 6 April, at the start of the new UK tax year.
When is the next ISA allowance reset?
The next reset is 6 April 2027. The current 2026/27 allowance ends on 5 April 2027.
Can I carry unused ISA allowance into 2027?
No. Unused standard ISA allowance normally expires when the tax year ends and cannot be added to the following year’s allowance.
Will the Cash ISA allowance be £12,000 in 2027?
No. Autumn Budget 2026 reversed the proposed reduction. The government intends to retain the £20,000 Cash ISA allowance for eligible adults from 6 April 2027.
Can I put £20,000 into a Cash ISA in 2027?
Yes, subject to eligibility and the overall annual limit. Cash ISA subscriptions and other adult ISA contributions must collectively remain within the permitted £20,000 annual allowance.
Does transferring an old ISA use my allowance?
A properly completed ISA transfer generally preserves the tax wrapper and does not turn previous years’ ISA savings into new personal contributions. Transfer arrangements and restrictions should be confirmed with the receiving provider.
Does my ISA interest count towards the £20,000 limit?
No. Eligible interest, dividends and investment growth arising within an ISA do not count as new personal subscriptions.
Is the ISA allowance separate for married couples?
Yes. Each eligible adult has their own individual ISA allowance. A couple could therefore contribute £40,000 across their respective adult ISAs in a tax year if both qualify and have sufficient funds.
More in Finance & Tax
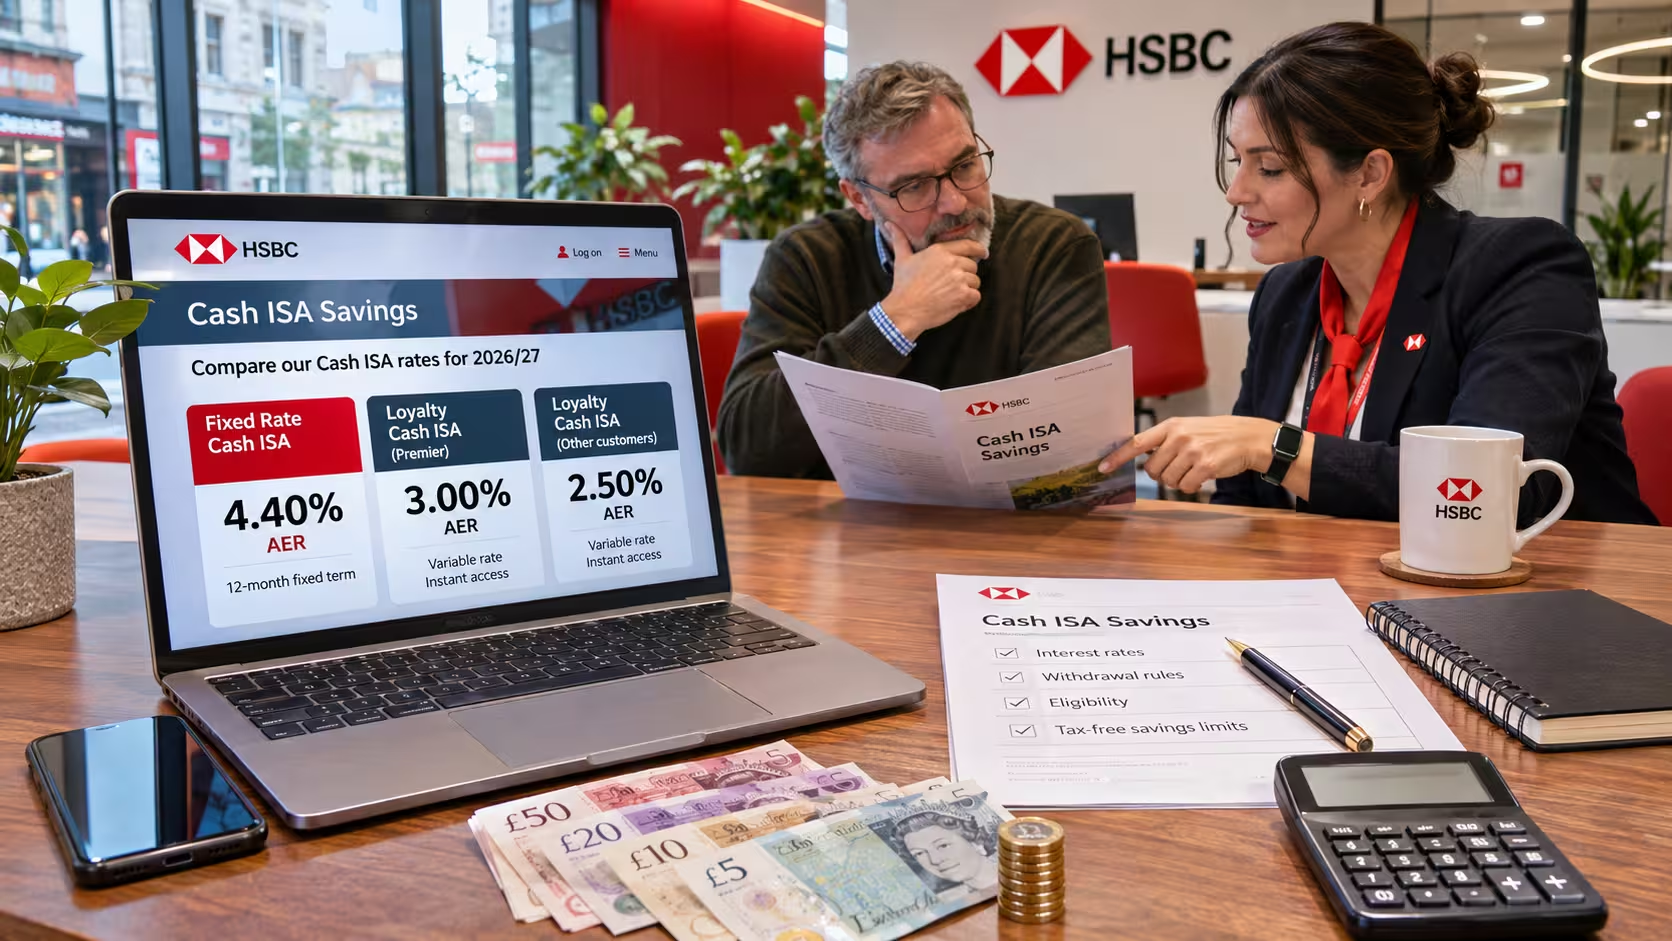
HSBC ISA Rates 2026/2027: Current Cash ISA Rates, Eligibility and Comparison
HSBC ISA rates currently range from 2.50% to 4.40% AER, depending on the Cash ISA and the customer’s account type. The HSBC Fixed Rate Cash ISA pays 4.40% AER tax-free, while the Loyalty Cash ISA pays 3.00% AER for HSBC Premier customers and 2.50% AER for customers with other eligible HSBC current accounts. The main […]
How to Open a Lifetime ISA in 2027?: Step-by-Step Guide, Eligibility and 2026 Rule Changes
Opening a Lifetime ISA in 2027 could help UK residents build a first-home deposit or create a tax-efficient savings fund for later life. The government provides a 25% bonus on eligible contributions, meaning someone who saves £4,000 in a tax year can receive an additional £1,000. However, choosing the right account involves more than finding […]