Yes, you can have more than one ISA in the UK, including multiple Cash ISAs and Stocks and Shares ISAs. Since 6 April 2024, eligible savers have generally been allowed to pay into more than one ISA of the same type during a single tax year.
However, opening multiple ISAs does not increase the amount you can save tax-free each year.
For the 2026/27 tax year, which runs from 6 April 2026 to 5 April 2027, the overall adult ISA allowance is £20,000. You can divide this between eligible ISA accounts, whether you use two providers or several.
There is also an important change approaching. From 6 April 2027, people under 65 will generally be limited to £12,000 of new contributions to Cash ISAs each tax year, although the overall annual ISA allowance will remain £20,000.
The distinction matters for anyone managing emergency savings, building an investment portfolio, saving for a first property or deciding how to distribute personal savings between different financial institutions.
Our analysis of the current rules shows that the number of ISA accounts is rarely the main issue. What matters most is how much new money you contribute, which account types you use and whether withdrawals or transfers are handled correctly.
How Many ISAs Can You Have in the UK?
There is no general statutory limit on the number of ordinary adult ISA accounts an eligible person can hold.
Someone could have three Cash ISAs, two Stocks and Shares ISAs and an Innovative Finance ISA without breaching ISA rules simply because they have several accounts.
An individual might accumulate these accounts gradually over many years. They may keep an older fixed-rate ISA until maturity, open a new easy-access account for emergency savings and maintain a separate investment account for longer-term goals.
The important difference is between holding an account and subscribing to it.
Holding an ISA means you have an existing account, potentially containing money contributed during earlier tax years. Subscribing means adding new money that counts towards your current annual allowance.
For example, suppose someone has £65,000 spread across four Cash ISAs opened between 2021 and 2025. Those existing balances do not prevent them from using their full £20,000 allowance during 2026/27.
Interest earned within the accounts does not count as an additional personal subscription either.
For a closer breakdown of how allowances are calculated, the annual ISA contribution limits explain how payments across different account types share the same £20,000 ceiling.
Can You Pay Into More Than One ISA in the Same Tax Year?
Yes. The rules introduced in April 2024 allow savers to subscribe to multiple Cash ISAs, Stocks and Shares ISAs and Innovative Finance ISAs in the same tax year.
Before this change, the usual restriction was that someone could only subscribe to one ISA of each type during a tax year.
The current system offers greater flexibility, especially for people who want to compare savings rates, separate short-term and long-term money, or use different investment platforms.
However, Lifetime ISAs remain an important exception.
Isa Rules for the 2026/27 Tax Year
| ISA type | Can you hold more than one? | Can you pay into more than one in the same tax year? |
| Cash ISA | Yes | Yes |
| Stocks and Shares ISA | Yes | Yes |
| Innovative Finance ISA | Yes | Yes |
| Lifetime ISA | Yes | No, only one can receive subscriptions |
| Junior ISA | Special rules | One Cash Junior ISA and one Stocks and Shares Junior ISA per child |
The total contribution limit for adult ISAs is £20,000 during 2026/27, including a maximum of £4,000 into one Lifetime ISA. Junior ISAs have a separate £9,000 annual allowance belonging to the child.
The official HMRC ISA guidance confirms that the adult allowance can be divided between multiple eligible accounts.
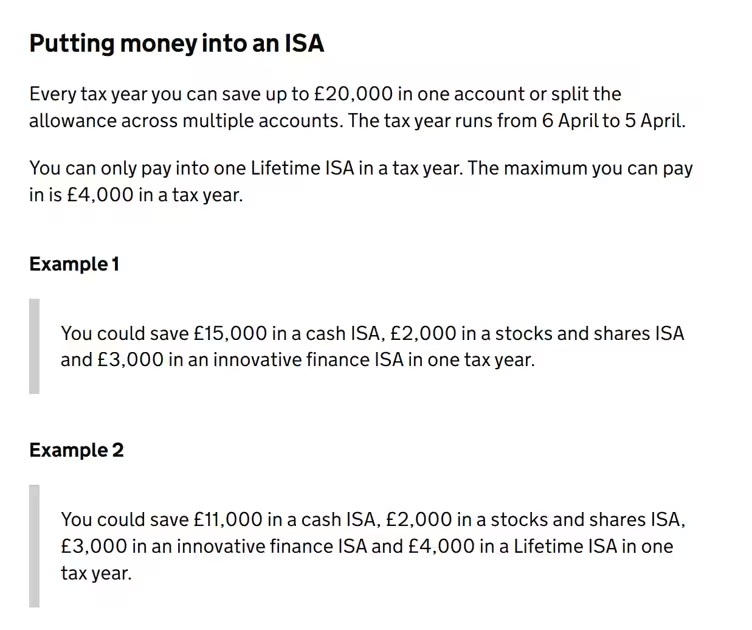
Official GOV.UK guidance showing the £20,000 adult ISA allowance, the ability to split contributions between accounts and the special Lifetime ISA restriction.
Does Each ISA Have Its Own £20,000 Allowance?
No. The £20,000 allowance belongs to the individual, not to each ISA account.
Opening five ISAs does not provide £100,000 of annual tax-free contribution capacity.
Instead, all qualifying adult ISA subscriptions are added together to determine how much of the annual allowance has been used.
Consider the following example:
| ISA account | Contributions during 2026/27 |
| Easy-access Cash ISA | £5,000 |
| Fixed-rate Cash ISA | £4,000 |
| Stocks and Shares ISA A | £5,000 |
| Stocks and Shares ISA B | £2,000 |
| Lifetime ISA | £4,000 |
| Total | £20,000 |
This allocation follows the 2026/27 subscription limits. The person uses five accounts but contributes only £20,000 in total.
The Lifetime ISA contribution is included within the overall allowance rather than being an additional £4,000.
If the saver subsequently tried to deposit another £2,000 into a Cash ISA during the same tax year, they would ordinarily exceed the annual limit.
The same principle applies regardless of the number of banks, building societies or investment platforms used.
Can You Have Two Cash Isas at the Same Time?
Yes. You can open and hold two or more Cash ISAs, and you can generally pay into multiple Cash ISAs during the same tax year.
This is particularly useful when the accounts have different purposes.
For example, an easy-access Cash ISA could hold money that may be required at short notice, while a fixed-rate Cash ISA could hold money that is unlikely to be needed during the fixed period.
Someone might contribute £7,000 to an easy-access Cash ISA and £13,000 to a fixed-rate Cash ISA during 2026/27. This would use their full annual adult ISA allowance without breaking the contribution rules.
The financial advantage depends on the interest rates, withdrawal conditions and fees associated with the accounts.
Can You Have Cash Isas With Different Banks?
Yes. There is no general requirement to keep all Cash ISA savings with the same institution.
However, an important practical distinction exists between HMRC rules and individual providers’ terms.
Although HMRC permits subscriptions to multiple Cash ISAs, some banks place restrictions on how many of their own Cash ISA products a customer may fund in a single tax year.
For instance, a provider might permit a customer to open one Cash ISA product with that institution while still allowing them to save with another bank.
Our assessment is that savers should check account-specific terms rather than assuming the flexibility available under tax legislation is automatically offered by every provider.
For an example of how individual product restrictions and flexible withdrawals can affect savers, the Virgin Money ISA account conditions illustrate why provider rules deserve attention.
Is Having Several Cash Isas Financially Beneficial?
Having multiple accounts can provide more flexibility, but it does not automatically improve returns.
Suppose two Cash ISAs both offer 4% AER and maintain that rate for a full year. Ignoring changes to balances during the period:
- £20,000 in one account would generate approximately £800 in annual interest.
- £10,000 in each of two accounts would also generate approximately £800 in total.
The number of accounts alone makes no difference to the total return.
The potential benefit arises when accounts offer different interest rates, access conditions or maturity dates.
Savers considering this approach can compare Cash ISA interest rates rather than assuming that splitting money between providers will necessarily produce a better result.
Can You Have More Than One Stocks and Shares ISA?
Yes. Under the rules applying in 2026/27, investors can hold and contribute to more than one Stocks and Shares ISA.
This allows an investor to maintain different portfolios or use investment platforms offering different services.
For instance, someone might have one Stocks and Shares ISA containing diversified index funds and another containing individual company shares.
They could contribute £8,000 to the first account and £6,000 to the second, leaving £6,000 of their overall annual allowance available for other qualifying ISA contributions.
However, using more than one investment account does not necessarily create greater diversification.
If two platforms hold investments tracking the same market index, the investor may still be exposed to substantially the same market risks.
From a portfolio-management perspective, diversification depends on the underlying assets, sectors, geographical exposure and investment strategy rather than the number of account providers.
Fees are another consideration. Platform charges, fund costs, transaction fees and foreign-exchange charges may reduce the benefits of maintaining multiple accounts.
Investment returns can also be negative. A Stocks and Shares ISA protects qualifying investments from UK capital gains tax and income tax within the ISA, but it does not protect investors against market losses.
Can You Have More Than One Lifetime ISA?
You can potentially hold more than one Lifetime ISA accumulated over different tax years, but you can only subscribe to one Lifetime ISA in a single tax year.
The annual contribution limit is £4,000, and this counts towards the overall £20,000 adult ISA allowance.
Lifetime ISAs are different from ordinary Cash ISAs because they are designed primarily for eligible first-home purchases and saving for later life.
The government adds a 25% bonus to qualifying contributions, up to £1,000 each tax year.
For example, contributing £4,000 would ordinarily generate a £1,000 government bonus, increasing the account’s value to £5,000 before any investment returns or interest.
That bonus does not count as a further personal subscription against the £20,000 allowance.
However, withdrawals outside qualifying circumstances normally attract a 25% charge on the withdrawn amount.
This is more significant than simply giving back the original bonus. If someone contributes £4,000 and receives a £1,000 bonus, withdrawing the entire £5,000 balance subject to the charge would leave £3,750. That represents a £250 loss against their original contribution, equivalent to 6.25%.
These restrictions mean a Lifetime ISA should not be treated as an ordinary emergency savings account.
For a practical example of first-home saving, Moneybox Lifetime ISA features and charges demonstrate why access conditions and bonus eligibility matter when choosing a provider.
Can You Have Both a Cash ISA and a Stocks and Shares ISA?
Yes, and this can be an effective way to separate money needed in the short term from investments intended for longer-term growth.
A Cash ISA offers interest without exposing the deposited capital to stock-market fluctuations, subject to provider risk and the relevant protections.
A Stocks and Shares ISA allows investment in qualifying assets, such as funds, shares and bonds, whose value can rise or fall.
The appropriate balance depends on when the money will be required, how much financial risk the saver can tolerate and whether they already hold sufficient accessible savings.
Consider someone with £20,000 available to contribute during 2026/27 who expects to need £8,000 within the next 12 months.
They might decide to keep £8,000 in a Cash ISA and invest the remaining £12,000 through a Stocks and Shares ISA, provided the latter amount is genuinely suitable for long-term investment.
Someone who might need the entire £20,000 soon could reasonably choose to keep all of it in cash instead.
The important principle is that the tax advantage of an ISA should not override the individual’s need for capital security and access to their money.
Can You Transfer Money Between Multiple ISAs?
Yes. An official ISA transfer can move eligible money between providers without normally treating the transferred balance as a new subscription.
This is particularly valuable for people who have accumulated sizeable savings over several years.
Suppose an individual has £85,000 in Cash ISAs built up from previous tax years. They find another provider offering more suitable account terms.
They can potentially transfer the existing £85,000 using the formal ISA transfer process without requiring an additional £85,000 of current-year subscription allowance.
The key is to instruct the receiving provider to arrange the transfer rather than withdrawing the money into an ordinary bank account.
How to Transfer An Isa Correctly?
- Choose a receiving ISA provider that accepts transfers of the relevant ISA type.
- Check whether the existing account has early-exit penalties or transfer charges.
- Complete the receiving provider’s ISA transfer instructions.
- Decide whether to transfer all or part of the existing balance, where supported.
- Confirm completion and retain the transfer statement for your records.
HMRC’s published guidance states that Cash ISA transfers should normally take no longer than 15 working days, while transfers involving other ISA types should normally take no longer than 30 calendar days. Some Innovative Finance ISA transfers require additional consideration.
A partial transfer may also be possible, including money contributed in the current year, although both providers’ processes and the applicable account restrictions need to be checked.
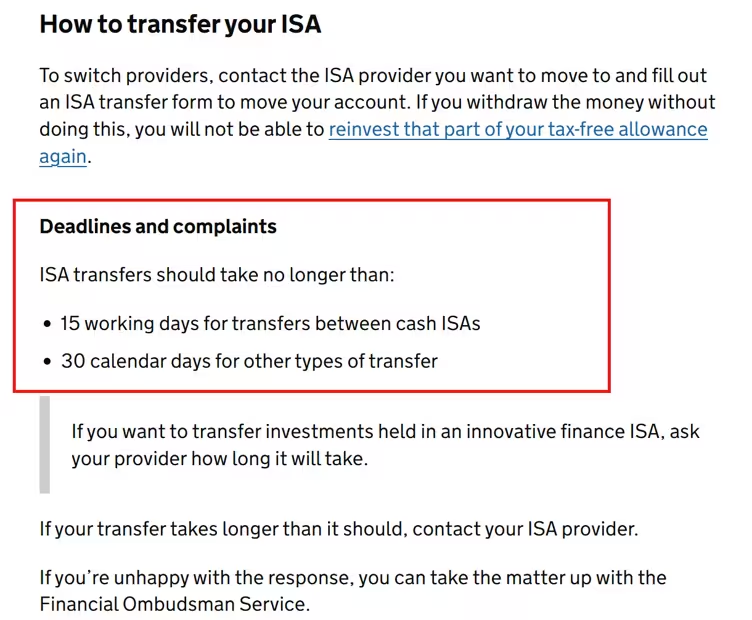
HMRC’s official ISA transfer guidance, showing how to transfer between providers and the expected transfer times.
Can You Withdraw From One ISA and Deposit Into Another?
Yes, but doing so may affect your ISA allowance because a personal withdrawal followed by a deposit into another account is not automatically an official ISA transfer.
This distinction is particularly important when an individual has already used most or all of their annual allowance.
Suppose someone contributed £20,000 to a non-flexible Cash ISA during 2026/27 and then withdrew £5,000.
They would not normally regain £5,000 of subscription allowance simply because the balance had fallen.
Depositing that £5,000 into a separate ISA as fresh money during the same tax year could create an over-subscription.
The position can be different when the original ISA is flexible.
How Flexible Isa Withdrawals Work?
A flexible ISA allows qualifying withdrawals to be replaced in the same tax year without consuming additional annual subscription allowance.
However, not all ISAs are flexible, and providers may apply different account terms.
One distinction that is frequently overlooked concerns the age of the money being withdrawn.
Under HMRC’s flexible ISA rules, withdrawals attributable to money subscribed in previous tax years generally need to be replaced into the account from which they were withdrawn.
Withdrawals of current-year subscriptions can reduce the net amount subscribed, potentially leaving allowance available for subscriptions elsewhere, subject to the applicable rules.
For example, imagine someone withdraws £6,000 of previous-year savings from a flexible Cash ISA in September 2026.
They may be able to replace the £6,000 into that same account before 5 April 2027 without using their current-year £20,000 allowance.
However, depositing the money into a different Cash ISA is not automatically treated as replacing those previous-year funds.
This is why we consider flexibility to be an important product feature for savers who expect irregular expenses or changing cash-flow requirements.
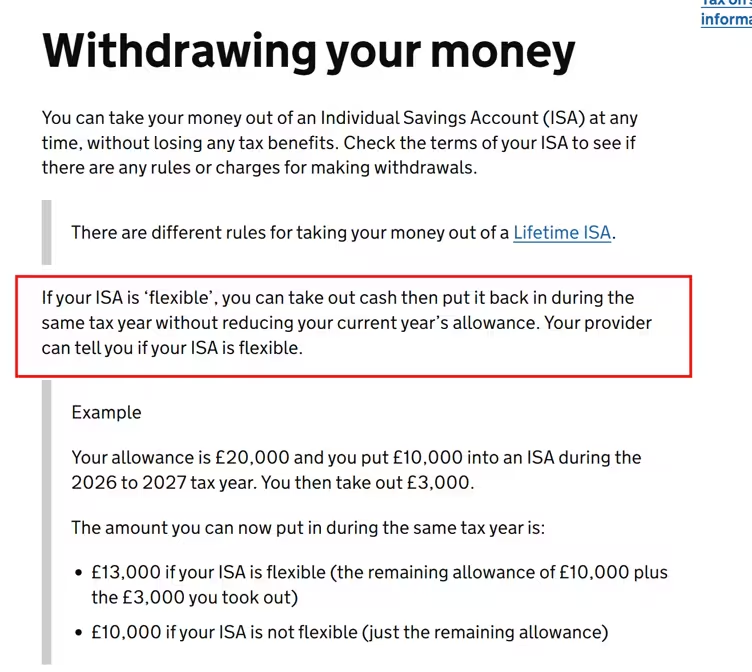
GOV.UK explanation of flexible ISA withdrawals and how replacing withdrawn money affects the annual ISA allowance.
What Changes for Multiple ISAs From 6 April 2027?
The most significant upcoming change to ISA rules concerns how much money people under 65 can contribute to Cash ISAs.
From 6 April 2027, the government is introducing a lower annual Cash ISA contribution limit for those under 65, while preserving the overall £20,000 ISA allowance.
This is not a restriction on how many Cash ISAs someone can own. It is a restriction on the combined amount of new money that can be paid into them during the tax year.
Isa Allowance Comparison: 2026/27 vs 2027/28
| ISA rule | 2026/27 | From 6 April 2027 |
| Overall adult ISA allowance | £20,000 | £20,000 |
| Cash ISA limit for under-65s | £20,000 | £12,000 |
| Cash ISA limit for those eligible for age-65 treatment | £20,000 | £20,000 |
| Lifetime ISA contributions | £4,000 | £4,000 |
| Junior ISA allowance | £9,000 | £9,000 |
| Multiple Cash ISA accounts | Permitted | Permitted |
| Multiple Stocks and Shares ISAs | Permitted | Permitted |
For someone under 65, the new £12,000 limit applies across their Cash ISA subscriptions collectively.
For example, contributing £7,000 to one Cash ISA and £5,000 to another would use the full £12,000 cash allowance for 2027/28.
They could still potentially contribute another £8,000 to qualifying non-cash adult ISAs, provided their overall subscriptions remain within £20,000.
However, there is no obligation to invest that remaining £8,000. Anyone unwilling to accept investment risk can retain money in ordinary savings accounts instead, taking account of the applicable savings-interest tax rules.
The government’s official ISA reform factsheet also explains measures intended to prevent the new Cash ISA limit from being bypassed.
Does the £12,000 Cash Isa Limit Affect Existing Savings?
No. The new limit concerns annual subscriptions rather than reducing existing ISA balances to £12,000.
For example, someone aged 40 who already has £90,000 in Cash ISAs does not need to withdraw £78,000 when the new rules begin.
Their existing ISA savings can remain protected within the ISA system, subject to the normal account conditions.
They will simply be subject to the new annual Cash ISA contribution limit when making eligible new subscriptions from 6 April 2027.
This distinction is important because some savers mistakenly interpret the £12,000 figure as a maximum permitted Cash ISA balance.
It is not.
What Happens When You Turn 65?
People entitled to the age-65 treatment will retain the ability to subscribe up to £20,000 to Cash ISAs.
An important feature is that eligibility for the higher Cash ISA limit applies from the beginning of the tax year in which someone turns 65.
For example, someone who turns 65 in February 2028 would qualify for the higher limit from 6 April 2027, rather than having to wait until their birthday.
This provides a different set of options for savers approaching retirement who want to hold a larger proportion of their ISA contributions in cash.
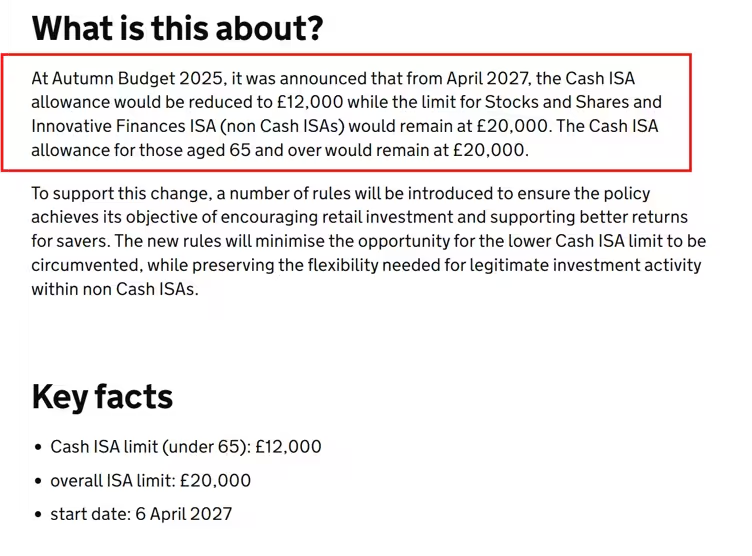
HMRC’s official 2027 ISA reform factsheet, confirming the £12,000 Cash ISA limit, £20,000 overall allowance and age-65 exception.
Will Isa Transfers Also Change in 2027?
Yes. The upcoming reforms include restrictions on transfers from non-cash ISAs into Cash ISAs for people under 65.
Under the new framework, these investors will no longer be permitted to transfer money from Stocks and Shares ISAs or Innovative Finance ISAs into Cash ISAs.
Transfers in the other direction, from Cash ISAs to eligible non-cash ISAs, will remain possible.
The transfer restriction will not apply from the start of the tax year in which an individual turns 65.
This is an important planning consideration for someone intending to move a large investment portfolio into cash within an ISA.
For example, a 45-year-old investor who has £50,000 in a Stocks and Shares ISA may currently be able to transfer that balance into a Cash ISA using the official process.
From April 2027, that transfer route will be restricted under the new rules.
Anyone considering a significant transfer should therefore distinguish between a transfer permitted under the rules in force today and one they might want to make after the reform begins.
What Is the 22% Charge on Cash Held in Stocks and Shares Isas?
Another important change is a flat-rate 22% charge on interest or qualifying alternative finance returns paid on cash held inside non-cash ISAs.
The measure is designed to discourage investors from using a Stocks and Shares ISA as a long-term substitute for a Cash ISA.
For example, suppose an investor receives £200 in interest on uninvested cash inside a Stocks and Shares ISA after the new rules take effect.
A 22% charge on that £200 would amount to £44.
The charge relates to interest on cash holdings, not a general 22% tax on investment gains made within a Stocks and Shares ISA.
Under the announced framework, ISA managers will account for the charge to HMRC, rather than investors declaring this ISA interest through Self Assessment.
The reforms also restrict portfolios consisting entirely of specified cash-like investments, particularly Money Market Funds. Portfolios containing a mixture of eligible investments and some cash-like exposure can remain permissible.
For investors maintaining several Stocks and Shares ISAs, this creates another reason to review whether each account holds investments or significant uninvested cash balances.
Is It Better to Have One ISA or Multiple ISAs?
The answer depends on the saver’s financial circumstances rather than a universal rule.
From our assessment, the strongest reasons to hold several ISAs are differences in accessibility, account terms and investment objectives.
For example, someone saving towards a house deposit while also investing for retirement may benefit from keeping those two financial goals separate.
However, an individual with three Cash ISAs offering similar interest rates and access conditions may gain little by opening a fourth.
| Financial consideration | One ISA | Multiple ISAs |
| Administration | Usually simpler | More accounts to monitor |
| Interest-rate options | Limited to chosen provider’s products | Ability to compare different providers |
| Access to savings | Depends on one account’s terms | Can combine easy access and fixed terms |
| Investment strategy | Easier to monitor centrally | Different portfolios can be separated |
| ISA allowance tracking | Usually straightforward | Requires tracking contributions across accounts |
| Provider exposure | Concentrated with one provider | Can be spread across providers |
| Fees | Potentially easier to control | Additional charges may apply |
The most appropriate structure is generally the one that achieves a clear financial purpose without unnecessary complexity.
Someone considering several fixed-rate accounts should also look at maturity dates and penalties rather than selecting products solely on their advertised AER.
Different maturity dates can be helpful because they allow parts of the savings balance to become accessible at different times.
Does Having Several Cash ISAs Improve FSCS Protection?
It can, but only when the accounts are held with appropriately separate authorised institutions.
The Financial Services Compensation Scheme (FSCS) increased its standard eligible deposit protection limit from £85,000 to £120,000 on 1 December 2025.
The current limit applies per eligible person, per authorised bank, building society or credit union.
Suppose a saver has accumulated £180,000 across multiple Cash ISAs.
If the full £180,000 is held with one authorised bank, the standard FSCS deposit protection limit would ordinarily be £120,000 for that eligible depositor, assuming no special circumstances apply.
If the saver instead holds £90,000 with each of two separately authorised institutions, both balances could potentially fall within their respective standard protection limits.
However, different banking brands do not always hold separate authorisations.
Two banks belonging to the same banking group may share an authorisation, meaning balances with both brands are combined for protection purposes.
For someone who has accumulated substantial ISA savings over many years, checking the underlying banking authorisation is therefore more important than simply counting the number of account names.
The position is also different for Stocks and Shares ISAs. FSCS investment protection does not compensate investors for ordinary market losses.
Is There a Tax Benefit to Having Multiple ISAs?
ISAs provide a tax-efficient environment for qualifying savings and investments, but having more ISA accounts does not produce additional tax allowances.
For Cash ISAs, interest is normally free from UK Income Tax.
For Stocks and Shares ISAs, qualifying investment income, dividends and capital gains remain protected from the relevant UK taxes within the ISA.
The value of this protection depends partly on an individual’s wider tax position.
Cash Isa Versus Ordinary Savings Account: A Practical Example
Consider a higher-rate taxpayer in the 2026/27 tax year with £20,000 available to save.
Assume they can earn 5% interest over a year, and that they have no other taxable savings interest.
| Calculation | Ordinary savings account | Cash ISA |
| Deposit | £20,000 | £20,000 |
| Illustrative interest rate | 5% | 5% |
| Annual interest | £1,000 | £1,000 |
| Personal Savings Allowance applied | £500 | Not required |
| Taxable interest | £500 | £0 |
| Income Tax at 40% | £200 | £0 |
| Interest after tax | £800 | £1,000 |
In this simplified example, holding the savings inside a Cash ISA results in £200 more interest after tax.
The example assumes equal interest rates, no other taxable savings income and standard 2026/27 higher-rate taxation. Actual results vary depending on income, account rates, when interest is credited and other available allowances.
Basic-rate taxpayers generally have a £1,000 Personal Savings Allowance in 2026/27, while higher-rate taxpayers have £500 and additional-rate taxpayers receive no Personal Savings Allowance.
Consequently, an ordinary savings account may be competitive for someone whose total interest remains within their available tax-free allowance.
The benefit of an ISA also extends beyond a single tax year, since money accumulated inside the ISA can continue receiving the relevant tax treatment.
For long-term savers, this can become increasingly valuable as balances and interest earnings grow.
Can Self-Employed People and Business Owners Have Multiple ISAs?
Yes. Self-employed people, company directors and business owners can hold multiple personal ISAs under the same eligibility and annual contribution rules as other UK savers.
Being self-employed does not create a separate ISA allowance or reduce the standard entitlement.
However, it is important to distinguish personal savings from business funds.
A limited company’s money does not automatically become the director’s personal money simply because they control the company.
Funds generally need to be extracted lawfully through an appropriate route, such as salary or dividends, with any relevant tax consequences considered, before they are treated as personal money available for an ISA contribution.
For sole traders, business and personal finances may be less legally separate, but funds needed to pay tax bills, suppliers or operating expenses should not automatically be committed to restricted-access savings products.
A self-employed consultant, for example, may prefer to hold emergency savings in an accessible Cash ISA while using a Stocks and Shares ISA for money intended to remain invested over the longer term.
The suitability of that approach depends on personal cash-flow needs and financial risk tolerance.
Can Married Couples Each Have More Than One ISA?
Yes. Each eligible adult has their own ISA allowance and can independently hold multiple accounts.
During 2026/27, two eligible adults could each contribute up to £20,000 to their respective adult ISAs.
That creates a combined potential household contribution capacity of £40,000, although the accounts must remain individually owned.
There is no ordinary joint adult ISA, and one partner cannot simply use an unused portion of the other’s allowance as an additional personal allowance.
Couples should also understand that money held within an ISA belongs to the named account holder.
There are special rules concerning additional permitted ISA subscriptions after the death of a spouse or civil partner. Those rules should not be confused with the normal annual ISA allowance.
Can You Have Multiple Junior ISAs for Your Children?
Junior ISAs operate differently from standard adult ISAs.
An eligible child can have one Cash Junior ISA and one Stocks and Shares Junior ISA, rather than subscribing to unlimited accounts of the same type.
The annual Junior ISA contribution limit for 2026/27 is £9,000 per child.
Contributions by parents, grandparents and other people are counted towards the child’s allowance, not the contributor’s own adult ISA allowance.
For example, a parent could potentially contribute £20,000 to their own adult ISAs and £9,000 to their child’s Junior ISA during the tax year, provided all eligibility conditions are met.
However, money placed inside a Junior ISA belongs to the child and is normally inaccessible until they turn 18.
Junior ISAs therefore should not be used simply as another place for parents to store money they expect to withdraw for their own purposes.
What Happens If You Accidentally Pay Into Too Many ISAs?
Opening multiple ISAs is permitted, but accidentally exceeding the annual contribution limit can create an issue requiring correction.
Suppose someone contributes:
| Account | New subscriptions |
| Cash ISA A | £9,000 |
| Cash ISA B | £7,000 |
| Stocks and Shares ISA | £6,000 |
| Total | £22,000 |
For 2026/27, this would ordinarily exceed the £20,000 annual allowance by £2,000.
The problem is not that the individual has three accounts. It is that their combined new subscriptions exceed the permitted limit.
If someone discovers this situation, they should contact their ISA provider or HMRC for the correct procedure.
They should not assume that withdrawing £2,000 from a random account will automatically repair the over-subscription.
HMRC has specific procedures for addressing invalid or excess subscriptions, and the correct treatment can depend on the year, account type and circumstances.
Providers may not know how much a customer has already contributed to ISAs held with other institutions, which makes accurate record-keeping particularly important.
How to Manage Multiple ISAs Without Exceeding the Allowance?
A straightforward way to manage several ISAs is to maintain a record of each account and its current-year subscriptions.
This is especially useful for anyone who makes regular monthly contributions rather than a single annual deposit.
For example:
| ISA | New contributions in 2026/27 |
| Cash ISA A | £5,000 |
| Cash ISA B | £3,000 |
| Stocks and Shares ISA | £7,000 |
| Lifetime ISA | £4,000 |
| Total subscribed | £19,000 |
| Remaining annual allowance | £1,000 |
This example leaves £1,000 available for further qualifying adult ISA contributions.
A useful personal record should distinguish new subscriptions from ISA-to-ISA transfers and from any qualifying flexible ISA replacements.
It should also include account maturity dates, relevant fees and provider-specific conditions.
Remember When the Isa Allowance Resets
The UK ISA allowance renews at the start of the tax year on 6 April.
Unused allowance generally cannot be carried forward.
For example, someone who contributes £12,000 during 2026/27 cannot add the unused £8,000 to their 2027/28 allowance.
Instead, they receive the normal allowance applying to the new tax year.
This makes the timing of contributions important, particularly for people who receive irregular income, annual bonuses or significant one-off payments.
Anyone planning contributions close to the tax-year boundary should understand when the ISA allowance resets and check their provider’s payment processing deadlines.
Five Mistakes to Avoid When Managing Multiple ISAs
- Mistake 1: Assuming each ISA provides a separate £20,000 allowance. The allowance applies to total qualifying adult ISA subscriptions, regardless of how many accounts someone holds.
- Mistake 2: Withdrawing ISA savings to change providers. Personal withdrawals are not equivalent to official ISA transfers and may lead to lost tax-efficient savings capacity.
- Mistake 3: Ignoring account restrictions. Some fixed-rate ISAs impose early-access charges, while individual providers may restrict subscriptions to their own products.
- Mistake 4: Treating Stocks and Shares ISAs as risk-free savings accounts. Investments can lose value, and from April 2027 interest on uninvested cash inside non-cash ISAs will face the announced 22% charge.
- Mistake 5: Failing to account for the 2027 Cash ISA changes. People under 65 planning to deposit more than £12,000 into Cash ISAs should distinguish the current tax-year rules from those applying from 6 April 2027.
Final Thoughts: Can You Have More Than One Isa?
Yes. UK savers can have multiple ISAs, and the rules introduced in April 2024 make it considerably easier to contribute to several accounts within the same tax year.
For 2026/27, the overall adult ISA allowance remains £20,000. That allowance can generally be divided between multiple Cash ISAs, Stocks and Shares ISAs and Innovative Finance ISAs, subject to the special rules for Lifetime ISAs.
Having several accounts can be helpful for separating financial goals, comparing interest rates, managing investment portfolios or spreading eligible deposits across financial institutions.
However, the number of accounts should not become the objective in itself.
Our assessment is that savers benefit most when every ISA serves a distinct financial purpose, account costs and withdrawal terms are understood, and total subscriptions are tracked accurately.
With the £12,000 Cash ISA limit approaching for those under 65 from April 2027, understanding these distinctions is becoming increasingly important.
The practical approach is to choose an ISA structure based on financial goals, tax circumstances and risk tolerance rather than opening additional accounts simply because the rules permit it.
Frequently Asked Questions
Can I Have Two ISAs at the Same Time?
Yes. You can hold multiple ISAs simultaneously, including accounts of the same type, provided you follow the applicable rules.
Can I Pay Into Two Cash ISAs in the Same Tax Year?
Yes. Since April 2024, eligible adults can generally contribute to more than one Cash ISA during the same tax year.
Can I Have Two Stocks and Shares ISAs With Different Providers?
Yes. You can use multiple investment platforms, although your total new contributions must remain within the annual ISA allowance.
Can I Put £20,000 Into Two Separate ISAs?
You can split £20,000 between two ISAs, but you cannot normally contribute £20,000 to each during the same tax year.
Can I Have Three Cash ISAs?
Yes. There is no general statutory limit of two Cash ISAs. Individual providers may have separate product restrictions.
Does Opening a Second ISA Affect My First ISA?
Not automatically. Opening another ISA does not remove the tax advantages of an existing eligible account.
Can I Open a New ISA Without Closing My Old One?
Yes. You can keep older ISAs and open additional accounts without automatically needing to consolidate existing balances.
Do ISA Transfers Count Towards the £20,000 Allowance?
Proper ISA-to-ISA transfers generally do not count as new personal subscriptions. Use the receiving provider’s formal transfer process.
What Happens If I Pay More Than £20,000 Into ISAs?
An excess contribution may require correction. Contact the relevant provider or HMRC rather than attempting to resolve it through unplanned withdrawals.
Can I Have a Cash ISA and a Lifetime ISA?
Yes. You can contribute to both, but Lifetime ISA contributions are limited to £4,000 annually and count towards the overall adult ISA allowance.
Can I Have More Than One ISA After Retirement?
Yes. Retirement does not prevent eligible individuals from holding several ISAs. The normal contribution and residency rules still apply.
Can I Put £20,000 Into Cash ISAs in 2027?
From 6 April 2027, those entitled to the age-65 treatment can continue contributing up to £20,000 to Cash ISAs. Those under 65 will generally have a £12,000 annual Cash ISA subscription limit.
Will Existing Cash ISAs Be Affected by the £12,000 Rule?
Existing balances do not need to be reduced to £12,000. The new limit concerns qualifying annual Cash ISA subscriptions.
Can I Have Multiple ISAs With the Same Bank?
Potentially, yes. However, some banks restrict how many of their own ISA products a customer can fund during one tax year.
Is It Better to Have One ISA or Several?
Neither approach is universally better. Multiple accounts can provide flexibility, while one account may offer simpler administration and easier contribution tracking.
More in Finance & Tax
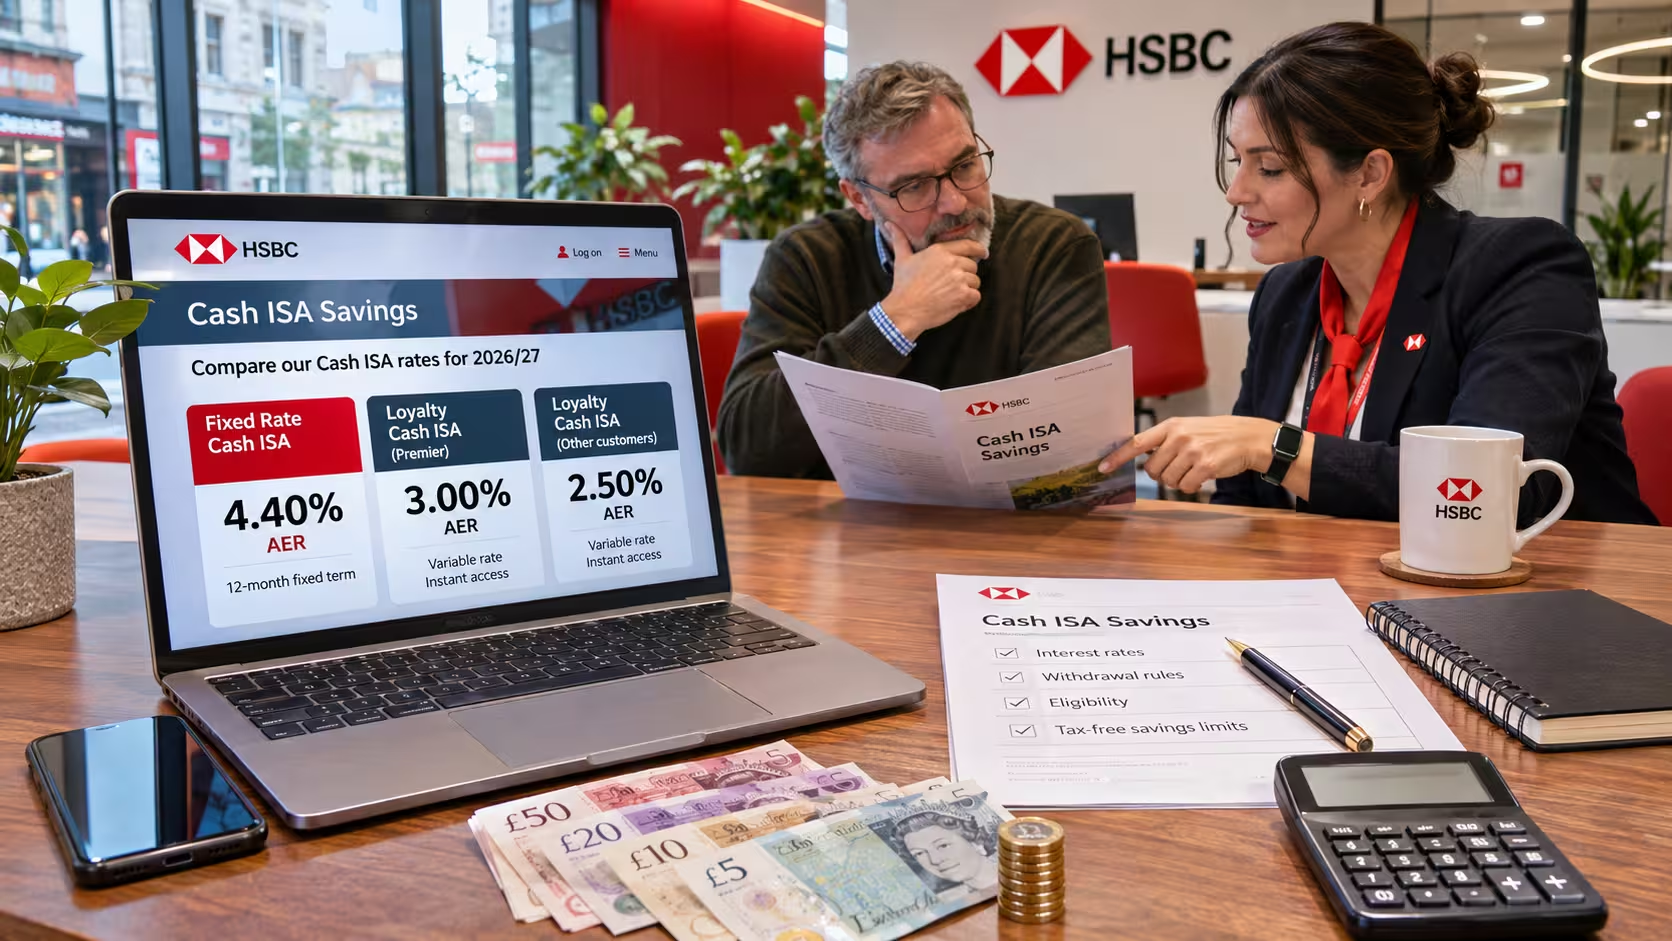
HSBC ISA Rates 2026/2027: Current Cash ISA Rates, Eligibility and Comparison
HSBC ISA rates currently range from 2.50% to 4.40% AER, depending on the Cash ISA and the customer’s account type. The HSBC Fixed Rate Cash ISA pays 4.40% AER tax-free, while the Loyalty Cash ISA pays 3.00% AER for HSBC Premier customers and 2.50% AER for customers with other eligible HSBC current accounts. The main […]
How to Open a Lifetime ISA in 2027?: Step-by-Step Guide, Eligibility and 2026 Rule Changes
Opening a Lifetime ISA in 2027 could help UK residents build a first-home deposit or create a tax-efficient savings fund for later life. The government provides a 25% bonus on eligible contributions, meaning someone who saves £4,000 in a tax year can receive an additional £1,000. However, choosing the right account involves more than finding […]