The local government pay rise for 2027 is becoming a major issue for council employees, school support workers, trade unions and local authority employers across England, Wales and Northern Ireland.
While the 2026/27 National Joint Council (NJC) settlement has been confirmed at 3.3%, negotiations over the next pay award are beginning to take shape.
An important development came on 23 October 2026, when GMB published its priorities for the 2027 NJC pay campaign. These include an inflation-linked increase of around 5%, a minimum hourly rate of £15 and stronger financial support for local authorities.
Meanwhile, the Government has confirmed that the National Living Wage will increase by 3.9% to £13.21 an hour from April 2027. This creates additional pressure on the lower NJC salary grades, which currently begin at £13.28 an hour.
Our analysis of employer announcements, published salary scales, trade union communications and local authority payroll information indicates that the 2027 pay negotiations will involve more than a simple percentage increase.
They will also address salary structures, recruitment, inflation, council finances and the growing difficulty of maintaining meaningful differences between lower-paid grades.
For workers, the immediate position is clear: the 2026 award is agreed, but no national NJC pay increase for 2027/28 has yet been finalised.
What Is the Latest Local Government Pay Rise Update for 2027?
As of 10 November 2026, the confirmed national NJC settlement remains the 3.3% award covering 1 April 2026 to 31 March 2027.
The next settlement would normally cover the pay year beginning 1 April 2027, although negotiations and payroll implementation may take place later.
| Key development | Latest position |
| Confirmed 2026/27 pay increase | 3.3% |
| 2026 pay agreement date | 24 August 2026 |
| 2026 award effective from | 1 April 2026 |
| NJC minimum annual salary | £25,614 |
| NJC minimum hourly rate | £13.28 |
| 2027/28 national NJC pay award | Not yet agreed |
| GMB’s October 2026 pay priority | Around 5%, linked to RPI inflation |
| GMB minimum-pay objective | £15 per hour |
| National Living Wage from April 2027 | £13.21 per hour |
| Next expected NJC pay-year start | 1 April 2027 |
| NJC pay-spine review | Under way |
The distinction between an agreed settlement, a trade union proposal and a statutory minimum-wage increase is particularly important.
The Government’s National Living Wage announcement is confirmed policy. GMB’s 2027 proposals are negotiating priorities, not an agreed NJC award.
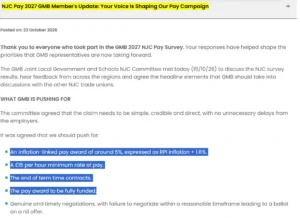
Official GMB announcement dated 23 October 2026 outlining its priorities for the 2027 NJC pay campaign.
Has the Local Government Pay Rise for 2027 Been Confirmed?
No. There is currently no agreed national NJC percentage increase for the 2027/28 pay year.
The process involves the recognised trade unions, including UNISON, GMB and Unite, developing a collective pay claim and presenting it to the National Employers.
Individual unions may first publish their preferred negotiating positions. These should not be mistaken for a final joint claim or an accepted employer offer.
On 19 October 2026, GMB’s Joint Local Government and Schools NJC Committee discussed member feedback and identified priorities for the forthcoming negotiations.
These included:
- An inflation-linked pay increase of around 5%, expressed as RPI inflation plus 1.6%.
- A minimum hourly salary of £15.
- Ending term-time contracts.
- Full funding for the pay settlement.
- Earlier and more meaningful negotiations, with potential industrial action considered if employers fail to negotiate.
These proposals suggest that 2027 bargaining could address both pay and employment conditions.
However, a 5% rise cannot yet be described as the official 2027 award. Neither the final joint-union claim nor the employers’ response should be assumed in advance.
Our assessment is that employers will face competing pressures: maintaining affordable staffing budgets while making council and school employment sufficiently attractive to retain experienced workers.
What Happened to the Local Government Pay Rise in 2026?
The 2026/27 settlement was agreed on 24 August 2026 after several months of disagreement.
The National Employers originally offered a 3.3% increase in March 2026. The unions argued that this was insufficient to reverse the erosion of council workers’ spending power.
The original union claim sought at least £3,000 or 10%, whichever was greater, alongside a £15 minimum hourly rate and changes to working conditions.
The employers maintained their 3.3% offer.
UNISON and GMB subsequently accepted the offer reluctantly. The necessary majority agreement was reached, allowing the national settlement to be implemented even though Unite did not support the final agreement.
The confirmed settlement includes a permanent 3.3% increase to NJC spinal column points 3 to 43 and applicable allowances. It also covers qualifying points above the national spine but below deputy chief officer level.
The pay rise is retrospective from 1 April 2026.
How Does the 2026 Award Compare With Earlier Years?
| Pay year | NJC pay increase | Position |
| 2025/26 | 3.2% | Agreed |
| 2026/27 | 3.3% | Agreed |
| 2027/28 | Not confirmed | Negotiations developing |
The difference between the two latest confirmed awards is only 0.1 percentage point.
However, because both awards are consolidated into base salary, they affect the starting point for subsequent annual negotiations.
A worker who received both annual awards has had a cumulative nominal increase of approximately 6.61% over the two years, assuming their salary was subject to both percentage increases and no other changes.
That cumulative increase does not automatically represent a 6.61% improvement in purchasing power because inflation and deductions must also be considered.
What Are the Latest NJC Local Government Pay Scales for 2026/27?
The 2026 settlement established new national pay rates for NJC spinal column points 3 to 43.
SCP2 was deleted from 1 April 2026. The lowest remaining national point is SCP3, with a full-time annual salary of £25,614.
The table below shows the agreed 2026/27 rates. These remain the confirmed reference point for discussing possible 2027 pay increases.
| SCP | Annual salary 2026/27 | Hourly rate |
| 3 | £25,614 | £13.28 |
| 4 | £26,016 | £13.48 |
| 5 | £26,427 | £13.70 |
| 6 | £26,847 | £13.92 |
| 7 | £27,274 | £14.14 |
| 8 | £27,709 | £14.36 |
| 9 | £28,153 | £14.59 |
| 10 | £28,608 | £14.83 |
| 11 | £29,071 | £15.07 |
| 12 | £29,542 | £15.31 |
| 13 | £30,023 | £15.56 |
| 14 | £30,515 | £15.82 |
| 15 | £31,015 | £16.08 |
| 16 | £31,525 | £16.34 |
| 17 | £32,046 | £16.61 |
| 18 | £32,578 | £16.89 |
| 19 | £33,119 | £17.17 |
| 20 | £33,673 | £17.45 |
| 21 | £34,237 | £17.75 |
| 22 | £34,811 | £18.04 |
| 23 | £35,570 | £18.44 |
| 24 | £36,581 | £18.96 |
| 25 | £37,563 | £19.47 |
| 26 | £38,510 | £19.96 |
| 27 | £39,481 | £20.46 |
| 28 | £40,444 | £20.96 |
| 29 | £41,177 | £21.34 |
| 30 | £42,123 | £21.83 |
| 31 | £43,149 | £22.37 |
| 32 | £44,253 | £22.94 |
| 33 | £45,529 | £23.60 |
| 34 | £46,579 | £24.14 |
| 35 | £47,665 | £24.71 |
| 36 | £48,738 | £25.26 |
| 37 | £49,817 | £25.82 |
| 38 | £50,908 | £26.39 |
| 39 | £51,928 | £26.92 |
| 40 | £53,051 | £27.50 |
| 41 | £54,143 | £28.06 |
| 42 | £55,224 | £28.62 |
| 43 | £56,293 | £29.18 |
These are national full-time equivalent figures, with hourly rates based on standard NJC working-time calculations. Local grades, contracted hours and enhancements can vary.
For employees comparing their contractual salary with an hourly equivalent, our salary to hourly rate calculator explains how different working-week arrangements affect the calculation.
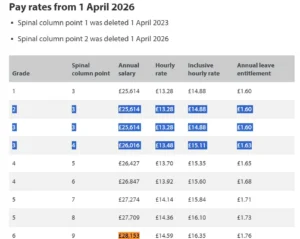
Official council NJC salary table showing the annual and hourly rates effective from 1 April 2026, including the deletion of SCP2.
How Much Could Local Government Salaries Increase in 2027?
Because the final 2027/28 award remains unknown, any salary calculation must be labelled as illustrative.
We have modelled three possible percentage increases against the confirmed 2026/27 national salary rates.
These scenarios are not forecasts or employer proposals. They simply show the financial effect of different percentage settlements.
| NJC point | Current 2026/27 | With 3% | With 5% | With 7% |
| SCP3 | £25,614 | £26,382 | £26,895 | £27,407 |
| SCP10 | £28,608 | £29,466 | £30,038 | £30,611 |
| SCP15 | £31,015 | £31,945 | £32,566 | £33,186 |
| SCP20 | £33,673 | £34,683 | £35,357 | £36,030 |
| SCP30 | £42,123 | £43,387 | £44,229 | £45,072 |
| SCP36 | £48,738 | £50,200 | £51,175 | £52,150 |
| SCP43 | £56,293 | £57,982 | £59,108 | £60,234 |
Illustrative annual full-time equivalent salaries, rounded to the nearest pound. Actual 2027 scales could differ because of rounding conventions, restructuring of spinal points or negotiated arrangements.
A 5% settlement would add approximately £1,281 a year to the present SCP3 salary and £2,106 to SCP30.
However, a flat percentage settlement could leave unresolved concerns about the distance between lower pay grades and the statutory minimum wage.
That is why the NJC pay-spine review matters.
How Will the 2027 National Living Wage Affect Council Pay?
One of the most important confirmed developments for 2027 is the increase in the National Living Wage.
On 28 October 2026, the Government announced that the hourly minimum for workers aged 21 and over would rise from £12.71 to £13.21 on 1 April 2027.
That represents a 3.9% increase.
| Measure | Hourly rate |
| National Living Wage, April 2026 | £12.71 |
| NJC starting rate, April 2026 | £13.28 |
| National Living Wage, April 2027 | £13.21 |
| Gap between April 2027 NLW and current NJC minimum | £0.07 |
| GMB’s proposed NJC minimum | £15.00 |
If the present NJC starting rate of £13.28 remained unchanged, it would sit only seven pence above the statutory National Living Wage from April 2027.
That is a margin of approximately 0.53% above the new statutory minimum.
This does not mean all council employees would automatically receive a separate pay increase because of the National Living Wage announcement. Their contractual rate, eligibility and any subsequent national settlement would still matter.
Nevertheless, it demonstrates why employers and unions are concerned about pay compression.
Why Does Pay Compression Matter?
Pay compression occurs when the difference in pay between workers at different grades becomes relatively small.
For example, employees taking on additional responsibility may see only a modest hourly difference between their salary and that of a colleague in a less demanding role.
Over time, this can weaken incentives for promotion and make skilled roles harder to recruit.
The abolition of SCP2 in April 2026 was already a structural response to pressure at the bottom of the national pay spine.
Further review may be needed in 2027 to ensure the salary framework remains workable.
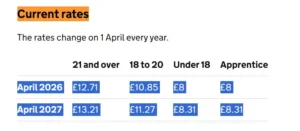
Official GOV.UK National Minimum Wage table confirming the £13.21 National Living Wage from April 2027.
Will Local Government Workers Receive £15 an Hour in 2027?
A £15 minimum hourly rate remains a trade union objective rather than an agreed national settlement.
GMB has included this demand in its October 2026 negotiating priorities.
Under the current 2026/27 national pay scales, SCP3 is worth £13.28 an hour.
Reaching £15 from that starting point would require an increase of approximately 12.95%.
By comparison, a straightforward 5% uplift would take the hourly rate to approximately £13.94 before any changes to pay-spine structure.
This demonstrates an important difference between the two negotiating objectives.
The 5% proposal concerns an inflation-linked pay award, while the £15 proposal involves establishing a higher minimum rate.
A final agreement could theoretically contain a general pay increase and additional changes to the lower spinal points.
However, there is no basis for assuming that either outcome has been agreed for 2027.
Who Will Receive the Local Government Pay Rise?
The NJC agreement principally covers eligible employees working under Green Book pay and conditions in England, Wales and Northern Ireland.
Common roles include council administration, refuse collection, recycling, libraries, environmental services, housing, planning, social care, cleaning, caretaking and various school support positions.
The precise position depends on the employee’s contract and local grading system.
For example, two workers with the same job title might receive different salaries because their councils use different local grading arrangements.
Equally, a school employee may work under NJC terms while a classroom teacher is covered by a completely separate national framework.
Our explanation of the employee and employer relationship covers why contractual terms, working arrangements and employment status matter when assessing pay and workplace rights.
Does the Award Cover Teaching Assistants?
Many teaching assistants, school administrators, cleaners, technicians, caretakers and lunchtime supervisors are covered when their contracts follow NJC Green Book terms.
However, academy trusts may have different pay arrangements.
Employees should check whether their employer has adopted the NJC agreement and whether the relevant rates have been implemented.
Teaching assistants working term-time-only contracts should also remember that the published national salary is normally a full-time equivalent figure.
Their actual annual pay depends on contractual hours, working weeks and the applicable holiday-pay method.
Are Scottish Council Workers Included?
No. Scottish local government employees are covered by separate collective bargaining arrangements.
The 3.3% NJC settlement described here should not automatically be applied to Scottish council workers.
Employees in Scotland should consult the relevant Scottish local-government pay agreement and their own employer’s salary information.
Do Parish and Town Council Employees Qualify?
Many parish and town council staff use contractual arrangements linked to the NJC pay spine.
The National Association of Local Councils published revised 2026/27 salary scales following the 3.3% settlement.
The revised scales also cover certain higher spinal points used for clerks and other staff.
Employees should check the terms of their employment and their council’s implementation notice.
When Will Local Government Employees Receive Their Back Pay?
The agreed 2026/27 NJC salary increase is retrospective to 1 April 2026.
This means eligible employees should receive arrears for the period between the effective date and the point at which their employer implemented the revised salary.
The actual payment date depends on the payroll arrangements of individual councils, schools and other employers.
For example, Devon County Council announced that the revised NJC rates would be implemented for certain maintained-school payroll clients in September 2026. Bradford’s schools payroll notice identified October 2026 for the pay award and November for relevant allowances.
These local arrangements demonstrate why there is no single national payment date for back pay.
How Can Employees Calculate Their Back Pay?
Consider an employee on SCP30.
| Salary calculation | Amount |
| Previous annual salary | £40,777 |
| Revised annual salary | £42,123 |
| Annual difference | £1,346 |
| Monthly gross increase | £112.17 |
| Seven months of approximate arrears | £785.17 |
If the employee was paid at the old rate from April through October, seven months of salary arrears would amount to approximately £785 before deductions, assuming no changes in hours, grade or employment.
The exact figure may differ because of payroll rounding, allowances, unpaid leave or contractual changes.
Can Former Council Employees Claim Back Pay?
Former employees who worked during the eligible period may also have an entitlement to arrears.
The National Employers have recommended that employers pay money due when an eligible former employee requests payment.
Someone who left employment after 1 April 2026 should contact their previous payroll or HR department and provide their employment details.
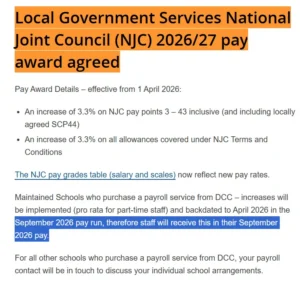
Official local authority payroll announcement confirming implementation of the 2026 NJC award and the relevant backpay arrangements.
How Much Will Council Workers Actually Take Home After the Pay Rise?
A 3.3% increase in gross salary does not necessarily produce a 3.3% increase in take-home pay.
Employee Income Tax, National Insurance, pension contributions and other deductions reduce the amount actually received.
Consider an employee receiving an additional £112.17 per month before deductions.
If that additional income falls entirely within the 20% Income Tax band and the 8% employee National Insurance band, those two deductions alone could reduce the extra cash by approximately £31.41.
That leaves approximately £80.76 before any pension, student loan or other applicable deductions.
This is an illustrative marginal calculation, not a personalised payroll estimate. Actual treatment depends on the employee’s tax position, thresholds and other circumstances.
For employees with multiple sources of income, understanding the distinction between a second job and self-employment is useful because additional income can affect their overall tax position.
Will Pension Contributions Increase?
Employees participating in the Local Government Pension Scheme should consider the impact of higher pensionable earnings.
An increased salary can produce a higher pension contribution in pounds, even where the employee’s percentage contribution remains unchanged.
Some employees may also move between contribution bands.
The outcome depends on scheme rules, pensionable pay and individual circumstances.
Higher pensionable earnings can also affect pension benefits built up under the career-average arrangements, rather than simply reducing the employee’s immediate take-home pay.
Can Back Pay Affect Universal Credit?
Yes, back pay can affect Universal Credit calculations.
An arrears payment may increase the amount of earnings reported through PAYE during a particular Universal Credit assessment period.
That can temporarily reduce a payment, depending on the claimant’s circumstances and how the earnings are treated.
Council employees receiving Universal Credit should examine both their payroll records and their benefit statements after receiving arrears.
Where the calculation appears incorrect, they should request clarification and retain payslips showing the backpay period.
Our analysis of earnings and benefit limits provides additional context on how changes in income can affect means-tested support.
It is also worth distinguishing Universal Credit from the former Working Tax Credit, which has been replaced for most relevant claimants.
Will Council Employees Receive More Than One Pay Increase in 2027?
This depends on the employee’s contractual arrangements.
An employee could experience a change in salary through a national NJC award, progression within a locally defined grade, promotion or another locally agreed adjustment.
These mechanisms should not be confused.
For example, a worker moving from SCP10 to SCP11 through progression may experience a salary change separate from the national annual award.
However, progression is not guaranteed for every employee or every grade.
A council may also operate local supplements, recruitment incentives or specific arrangements that are not automatically increased by the national percentage.
Employees should review their local pay policies rather than assume every potential increase will apply simultaneously.
Could the 2027 Pay Rise Increase the Cost of Running Councils?
Yes. A consolidated pay award creates a recurring employment cost rather than a one-off expenditure.
The National Employers estimated that the 2026 offer would increase the national pay bill by approximately £869.57 million, or 3.32%, including the cost associated with removing SCP2.
This illustrates the scale of even a relatively modest percentage increase across a large workforce.
Councillor James Lewis, Chair of the National Employers for local government services, acknowledged the pressure in March 2026:
“The National Employers are acutely aware of the additional pressure this offer will place on already hard-pressed council finances”
From a financial planning perspective, councils must consider more than basic salary.
A higher wage bill can also affect employer pension costs, National Insurance contributions and other employment-related expenditure.
For example, a hypothetical council workforce with £100 million in eligible annual basic salaries would face an additional £5 million of recurring basic pay costs if a 5% general increase were agreed.
That calculation excludes employer on-costs, restructuring and variations in the employees covered.
Could Council Budgets Affect Recruitment and Services?
Council finance officers must balance rising employment costs against the budgets available for statutory and discretionary services.
A higher settlement may improve recruitment and retention, particularly in occupations experiencing shortages.
However, if a settlement is not fully funded, employers may need to absorb additional costs through existing budgets.
Potential consequences include greater pressure on vacancy management, service planning, contract expenditure or other operating priorities.
For public-sector employers, recruitment difficulties can also create costs through agency staffing, overtime and employee turnover.
The financial question is therefore not simply whether a council can afford a particular percentage pay rise.
It is whether the long-term cost of retaining experienced employees is lower than the operational and recruitment costs associated with persistent vacancies.
Does the Local Government Pay Rise Protect Workers Against Inflation?
A nominal salary increase and an increase in real purchasing power are different.
An employee may receive a higher annual salary but still experience financial pressure if living costs rise faster than earnings.
To illustrate the difference, consider the confirmed 3.3% increase alongside two hypothetical inflation rates.
| Pay increase | Illustrative inflation | Approximate real-pay effect |
| 3.3% | 3% | +0.29% |
| 3.3% | 4% | -0.67% |
These are mathematical examples, not claims about the current inflation rate.
The financial outcome will also differ between households because spending patterns vary.
Housing, transport, energy, childcare and food can account for very different proportions of disposable income.
The headline settlement should therefore be assessed alongside actual household costs, tax deductions and pension contributions.
How Does Local Government Pay Compare With Other Public-Sector Settlements?
Local government pay should not be considered interchangeable with all public-sector salary awards.
The NHS, Armed Forces, teachers and certain council management groups have different pay-setting arrangements.
| Workforce | Pay-setting framework |
| Most NJC council employees | National Joint Council |
| Many school support workers | NJC Green Book |
| NHS Agenda for Change workers | NHS pay framework |
| Armed Forces personnel | Armed Forces Pay Review Body process |
| Teachers | Relevant national teacher-pay arrangements |
| Some senior council officers | Separate JNC arrangements |
| Scottish council employees | Scottish local-government bargaining |
For comparison, our review of the NHS pay rise explains the 2026/27 Agenda for Change settlement, while the Armed Forces pay increase follows a separate process.
These differences matter when employees compare career opportunities and employers assess their ability to recruit skilled staff.
What Are Our Expert Ratings of the Local Government Pay Settlement?
Our editorial assessment considers the confirmed award, implementation requirements and future negotiating uncertainty.
These ratings are analytical judgements rather than official government scores, independent surveys or statistically measured worker satisfaction.
| Assessment category | Editorial rating | Our reasoning |
| Certainty of 2026/27 settlement | 100% | The 3.3% agreement is finalised |
| Transparency of published salary scales | 90% | National NJC rates are available, although local grades vary |
| Implementation and payroll clarity | 70% | Backpay is confirmed but dates vary between employers |
| Strength of the 2026 settlement | 55% | The 3.3% award is below the unions’ original demands |
| Visibility of the 2027 outcome | 25% | Early union priorities exist, but there is no agreed award |
The ratings reflect our published editorial criteria and should not be interpreted as numerical predictions.
Our strongest concern is the continued compression of lower NJC salary grades.
The forthcoming 2027 increase in the statutory National Living Wage makes this issue especially important.
At the same time, the affordability of an improved settlement remains a genuine concern for councils managing ongoing budget pressures.
What Should Council Employees and Employers Prepare for in 2027?
Employees should first verify that their 2026/27 award has been correctly implemented.
Their payroll records should show the revised salary, applicable arrears and changes to relevant allowances.
They should then follow the development of the 2027 joint-union claim and subsequent employer response.
Those with additional employment should also review contractual restrictions and disclosure requirements. Our explanation of whether employees need to disclose a side hustle covers related employment considerations.
For council finance and payroll teams, the priority is scenario planning.
Budget models should distinguish between the confirmed 2026 pay bill and hypothetical increases for 2027.
They should also accommodate the statutory National Living Wage increase, changing contribution costs and any subsequent restructuring of NJC spinal points.
Employers preparing for wider 2027 payroll changes may also need to consider separate developments such as company cars and payrolling of benefits, although these are not part of the NJC salary agreement itself.
What Is the Final Outlook for the Local Government Pay Rise in 2027?
The 2027 local government pay debate is already developing around inflation, recruitment, affordability and the structure of NJC salaries.
The confirmed 2026/27 settlement delivered a 3.3% increase from April 2026, but it did not meet the unions’ original £3,000 or 10% demand or establish a £15 minimum hourly rate.
GMB’s October 2026 proposals indicate that these concerns are likely to remain central to the next negotiating round.
Meanwhile, the confirmed increase in the National Living Wage to £13.21 from April 2027 places further pressure on the bottom of the national pay spine.
Our analysis suggests that the eventual 2027/28 outcome will need to balance meaningful employee pay improvements against the financial capacity of councils and schools.
Until a formal agreement is announced, employees should use the confirmed 2026/27 salary scales for financial planning and treat any potential 2027 percentage increase as a proposal or scenario rather than guaranteed income.
Frequently Asked Questions About the Local Government Pay Rise 2027
Is there a confirmed local government pay rise for 2027?
The 2026/27 award of 3.3% is confirmed and remains effective until 31 March 2027. A separate NJC award for 2027/28 has not yet been agreed as of 10 November 2026.
Are council workers getting a 5% pay rise in 2027?
Not yet. GMB identified an inflation-linked increase of around 5% as a negotiating priority in October 2026. That is not a confirmed national settlement.
Will local government workers get £15 per hour?
The £15 minimum hourly rate remains a union objective. The confirmed 2026/27 national NJC minimum is £13.28 per hour at SCP3.
When will the 2027/28 NJC pay rise start?
The next NJC pay year would normally begin on 1 April 2027. However, the percentage, agreement date and payroll implementation timetable have not been finalised.
Will teaching assistants receive the local government pay rise?
Many teaching assistants employed under NJC Green Book terms are covered by national settlements. Actual pay depends on local grades, hours, term-time arrangements and the employer’s contractual framework.
Will council workers receive back pay from April 2026?
Eligible employees are entitled to the agreed retrospective increase from 1 April 2026. Payment dates depend on individual employers and payroll arrangements.
Does the 2027 National Living Wage increase automatically raise NJC salaries?
Not necessarily. The new £13.21 statutory minimum applies from April 2027 to eligible workers aged 21 and over. The effect on council salaries depends on existing pay rates, compliance requirements and subsequent NJC negotiations.
More in Finance & Tax
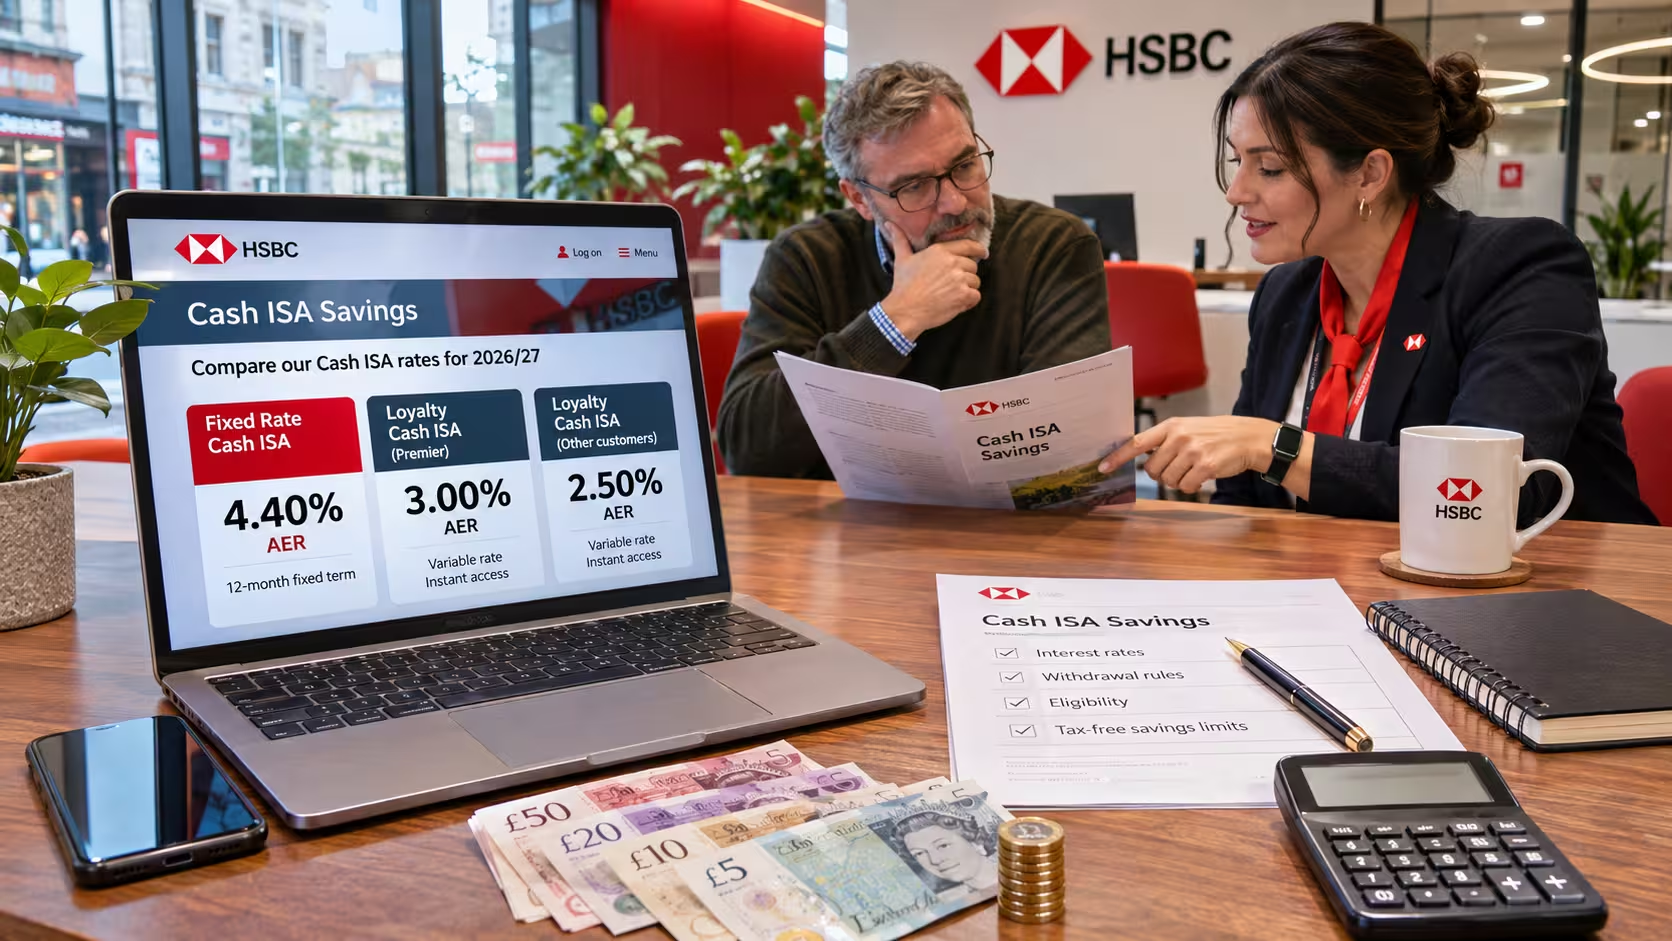
HSBC ISA Rates 2026/2027: Current Cash ISA Rates, Eligibility and Comparison
HSBC ISA rates currently range from 2.50% to 4.40% AER, depending on the Cash ISA and the customer’s account type. The HSBC Fixed Rate Cash ISA pays 4.40% AER tax-free, while the Loyalty Cash ISA pays 3.00% AER for HSBC Premier customers and 2.50% AER for customers with other eligible HSBC current accounts. The main […]
How to Open a Lifetime ISA in 2027?: Step-by-Step Guide, Eligibility and 2026 Rule Changes
Opening a Lifetime ISA in 2027 could help UK residents build a first-home deposit or create a tax-efficient savings fund for later life. The government provides a 25% bonus on eligible contributions, meaning someone who saves £4,000 in a tax year can receive an additional £1,000. However, choosing the right account involves more than finding […]