Coventry Building Society ISA rates are an important consideration for UK savers looking to earn tax-free interest in 2027.
Whether you want to lock away money for a guaranteed return, maintain access to emergency savings or transfer an existing ISA, choosing the right account can make a significant difference to your annual interest.
Our analysis of Coventry Building Society’s published savings products found fixed-rate Cash ISAs offering between 4.30% and 4.50% AER, while its unrestricted Easy Access ISA pays 2.00% AER.
The rates vary depending on how long you are prepared to commit your money and which withdrawal conditions you accept.
There is also an important development for 2027. Following the Autumn Budget 2026, the government confirmed that the annual Cash ISA allowance will remain at £20,000 for savers of all ages from 6 April 2027, reversing its earlier plan to reduce the limit to £12,000 for people under 65.
We examined the published interest rates, account restrictions, savings protection and tax implications to identify where Coventry’s accounts offer value and where savers should consider alternative options.
What Are Coventry Building Society ISA Rates for 2026 and 2027?
The following rates were displayed on Coventry Building Society’s official savings pages during our November 2026 review.
| Coventry ISA account | Interest rate (AER) | Rate type |
| Fixed Rate ISA (345), until 30 November 2027 | 4.30% | Fixed |
| Fixed Rate ISA (346), until 30 November 2028 | 4.35% | Fixed |
| Fixed Rate ISA (347), until 30 November 2029 | 4.50% | Fixed |
| 6 Access ISA – 1 Year (3) | 3.60% | Variable |
| Junior Cash ISA (2) | 3.75% | Variable |
| Easy Access ISA (12) | 2.00% | Variable |
| Additional Allowance ISA | 2.05% | Variable |
Rates checked against Coventry Building Society’s published account listings in November 2026. AER means Annual Equivalent Rate. These are current published offers, not forecasts of the rates that will be available for new applications during 2027.
The difference between the highest fixed rate and the unrestricted easy-access rate is 2.50 percentage points.
For somebody saving £20,000, that represents approximately £500 in additional annual interest at the quoted rates, before considering compounding or any account-specific conditions.
However, a higher interest rate does not automatically make an ISA the better choice. The fixed accounts restrict withdrawals, whereas the easy-access option provides significantly more flexibility.
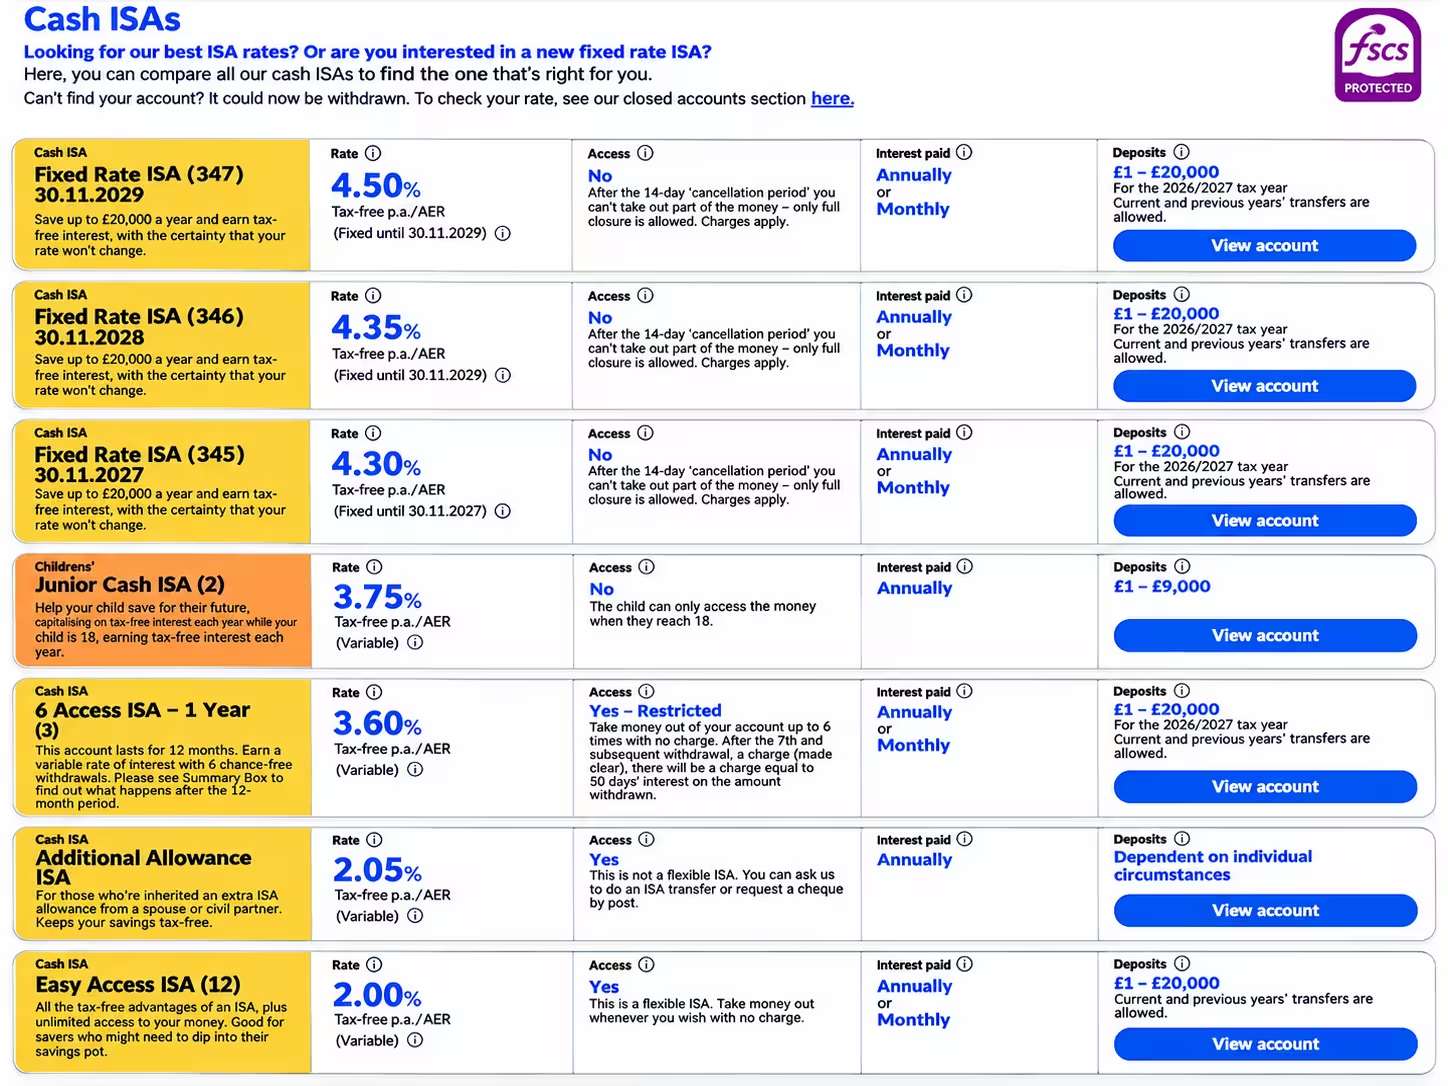
Coventry Building Society ISA rates displayed on the official Cash ISAs comparison page, showing fixed-rate products, the 6 Access ISA and Easy Access ISA.
Which Coventry Building Society Fixed Rate ISA Is Best for 2027?
Coventry Building Society offers several fixed-rate ISAs, each designed for savers with different financial horizons. Our comparison shows that the additional interest available on longer fixed terms must be weighed against the greater withdrawal restrictions.
Fixed Rate ISA Until November 2027 – 4.30% AER
The Fixed Rate ISA (345) offers 4.30% AER tax-free, with interest fixed until 30 November 2027.
Its main features include:
- Minimum balance of £1.
- Interest paid annually or monthly.
- Transfers from eligible existing Cash ISAs accepted.
- A 14-day cancellation period.
- No partial withdrawals after the cancellation period.
- An early closure charge equivalent to 90 days’ interest.
One detail that deserves particular attention is the funding deadline. Coventry requires the opening payment and additional contributions, including transfer instructions, within the specified limited funding window. Savers cannot assume they can continue adding money throughout the fixed term.
Our assessment is that this account suits somebody with a lump sum they can comfortably leave untouched until late 2027.
For broader context, compare it against the best one-year fixed-rate ISA accounts before deciding whether the convenience of remaining with Coventry justifies any difference in interest.
Fixed Rate ISA Until November 2028 – 4.35% AER
The Fixed Rate ISA (346) pays 4.35% AER, with the rate guaranteed until 30 November 2028.
Although the rate is 0.05 percentage points higher than the November 2027 account, savers accept a longer commitment.
On a £20,000 balance, that 0.05-percentage-point difference represents only about £10 in additional annual interest.
The early closure charge is also higher, equivalent to 180 days’ interest.
This highlights an important financial consideration: an extra £10 in annual interest may not compensate for reduced access if the money might be needed for a house deposit, family expenditure or business emergency.
Our comparison of two-year fixed-rate ISAs provides further options for savers willing to accept a longer commitment.
Fixed Rate ISA Until November 2029 – 4.50% AER
The Fixed Rate ISA (347) offers the highest rate within the three Coventry fixed products examined: 4.50% AER, fixed until 30 November 2029.
On £20,000, that produces approximately £900 in annual interest before considering compounding, assuming the balance is maintained for a full year.
However, it carries a substantial restriction: early closure is subject to a charge equivalent to 270 days’ interest.
Someone considering this account should distinguish between money genuinely available for long-term saving and money likely to be needed within the next three years.
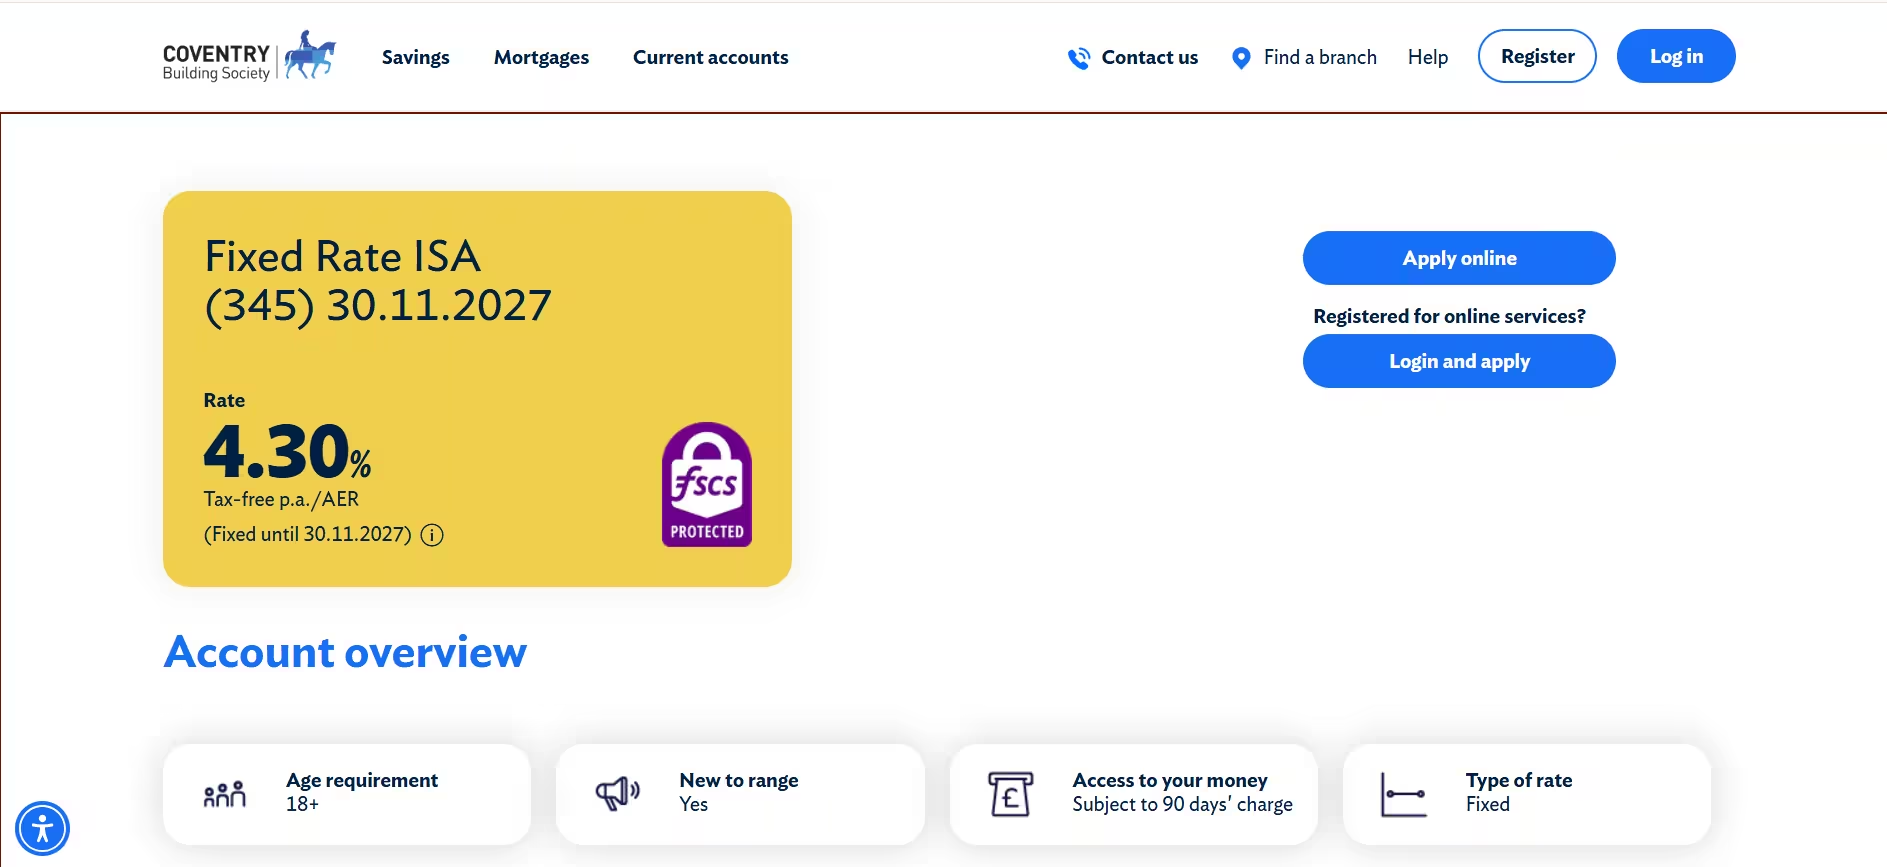
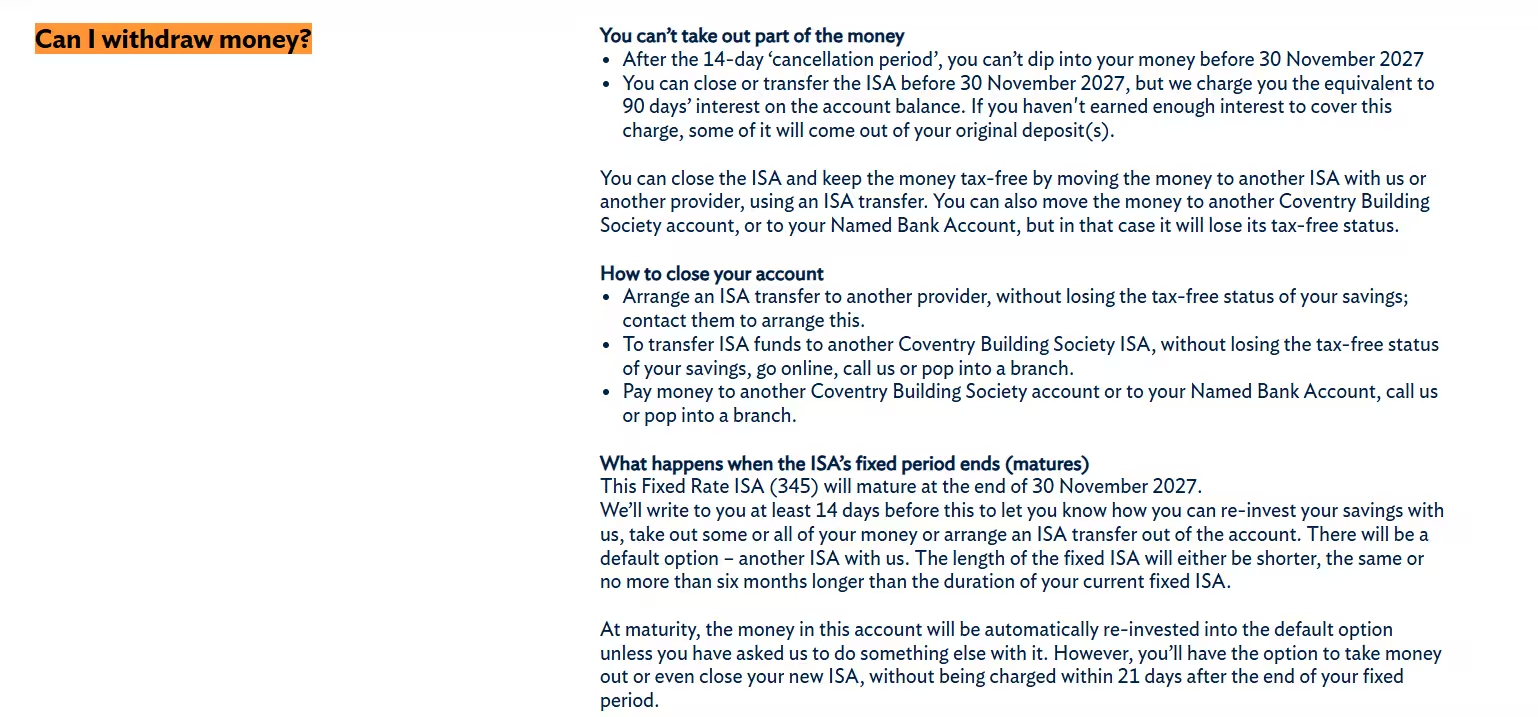
Coventry Building Society Fixed Rate ISA (345), showing the 4.30% AER rate, November 2027 maturity date and early closure charge.
How Much Interest Could You Earn With Coventry Building Society ISAs?
To compare the available products consistently, we calculated the approximate annual interest generated by different savings balances at each published rate.
| Savings balance | 2.00% Easy Access | 3.60% 6 Access | 4.30% Fixed | 4.50% Fixed |
| £1,000 | £20 | £36 | £43 | £45 |
| £5,000 | £100 | £180 | £215 | £225 |
| £10,000 | £200 | £360 | £430 | £450 |
| £15,000 | £300 | £540 | £645 | £675 |
| £20,000 | £400 | £720 | £860 | £900 |
Illustrative interest over one year, calculated as opening balance × annual AER. Assumes no withdrawals, further contributions or variable-rate changes. Actual amounts may differ according to payment dates, interest calculation and compounding. This does not represent the full return over each fixed term.
For somebody holding £20,000, the difference between the Easy Access ISA and the highest fixed-rate option is approximately £500 annually.
That is a substantial variation, but rate comparisons should never be separated from withdrawal conditions.
For example, a small-business owner may prefer slightly lower interest if maintaining access to personal reserves is more valuable than maximising returns.
What Are the Early Withdrawal Penalties on Coventry Fixed ISAs?
Early withdrawal charges are one of the most significant details to examine before opening a fixed Cash ISA.
The following comparison shows how the penalties differ.
| Fixed ISA maturity | AER | Early closure charge | Approximate charge on £20,000 |
| November 2027 | 4.30% | 90 days’ interest | £212 |
| November 2028 | 4.35% | 180 days’ interest | £429 |
| November 2029 | 4.50% | 270 days’ interest | £666 |
Illustrative calculations using the annual rate and a 365-day year. Actual charges follow the provider’s specific account terms and may differ.
An important distinction is that Coventry does not generally permit partial withdrawals from these fixed products after the cancellation period. A saver who needs access may have to close the entire account.
If insufficient interest has accrued, part of the charge could be taken from the original deposit.
Our analysis suggests that locking money away purely to obtain an extra 0.15 or 0.20 percentage points could be a poor decision when short-term liquidity is uncertain.
Is Coventry Building Society’s 6 Access ISA Better Than Its Easy Access ISA?
The 6 Access ISA provides a useful middle ground between unrestricted access and a fixed-term commitment.
It pays 3.60% AER variable, compared with 2.00% AER on the Easy Access ISA.
6 Access ISA
3.60%
Variable AER
Six withdrawals without a charge during the account’s 12-month term
Easy Access ISA
2.00%
Variable AER
Unlimited charge-free withdrawals without a fixed term
How the Six-Withdrawal Limit Works?
The 6 Access ISA allows six charge-free withdrawals over its 12-month period.
From the seventh withdrawal onward, including a closure that counts as an additional withdrawal, Coventry charges the equivalent of 50 days’ interest on the amount withdrawn.
This is different from an account that completely prohibits withdrawals.
Both the 6 Access ISA and Easy Access ISA are flexible ISAs, meaning eligible withdrawals can be replaced in the same tax year without using additional annual ISA allowance, subject to the account rules.
1 Year (3)+1
Our assessment is that the 6 Access ISA is more attractive for somebody expecting only occasional withdrawals. The unrestricted Easy Access ISA makes more sense when transaction frequency matters, although its published interest rate is significantly lower.
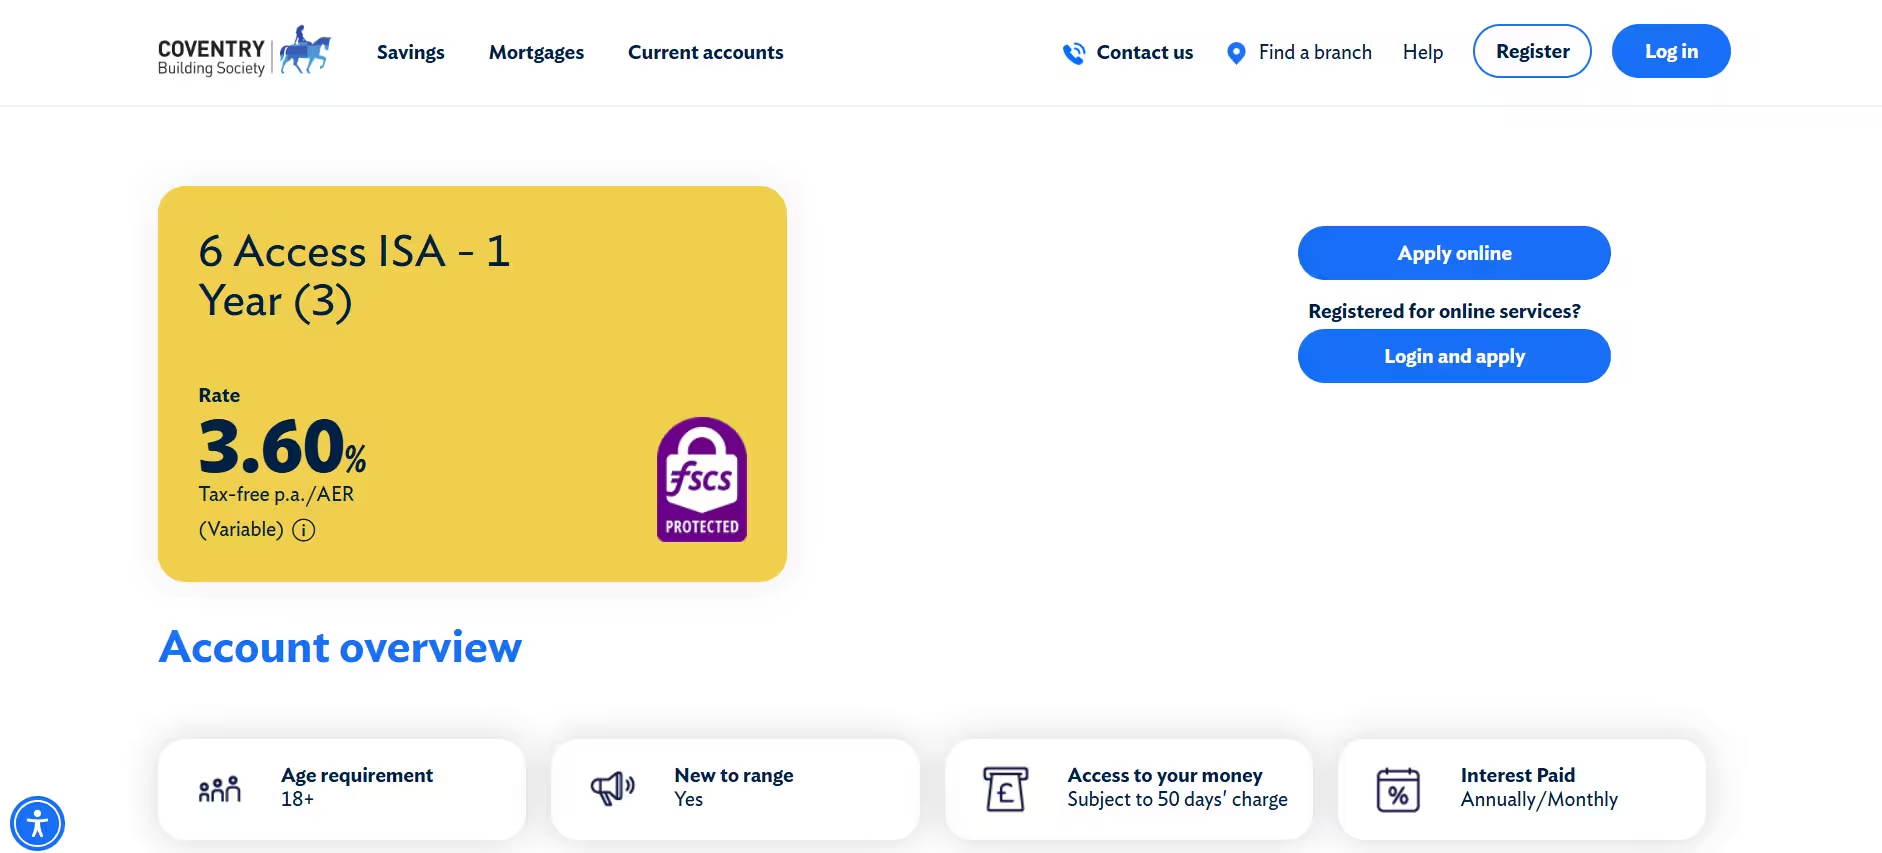
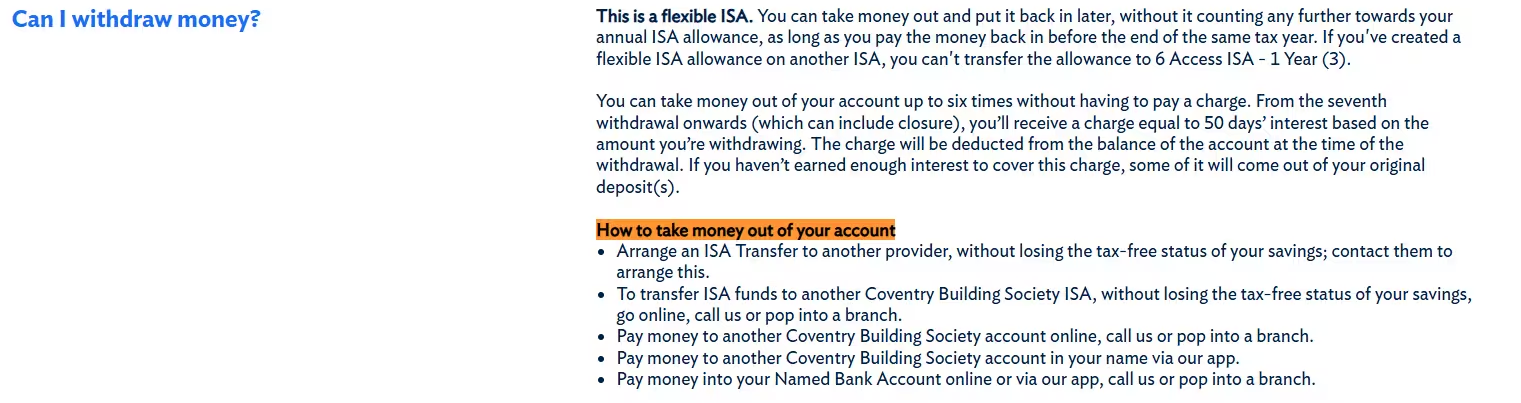
Coventry Building Society 6 Access ISA, showing its 3.60% variable rate, six permitted charge-free withdrawals and 50-day interest charge.
How Competitive Are Coventry Building Society ISA Rates Compared With Other UK Providers?
We compared Coventry’s published rates with UK Cash ISA market data available on 4 November 2026.
The comparison indicates that Coventry offers several established savings options, but its headline rates are not necessarily the highest available.
| ISA category | Coventry rate | Higher market example | Rate difference |
| One-year fixed or similar maturity | 4.30% | Shawbrook 5.02% | 0.72 pp |
| Two-year fixed or similar maturity | 4.35% | RCI Bank UK 5.15% | 0.80 pp |
| Easy access | 2.00% | Trading 212 4.87% | 2.87 pp |
Market examples recorded by Moneyfacts on 4 November 2026. Terms, maturity dates, eligibility, bonuses, opening balances and ISA transfer facilities differ. Trading 212’s quoted rate includes a promotional bonus. Figures are comparison snapshots, not guaranteed rates for 2027.
Compare & Apply
The percentage-point gaps translate into meaningful differences.
For example, the 0.72-percentage-point difference between the Coventry fixed account and the Shawbrook example represents approximately £144 annually on £20,000, assuming both rates applied for an equivalent period.
The comparison becomes more significant with easy-access accounts. However, promotional bonuses can expire, and some higher-rate products do not accept ISA transfers.
Savers should therefore compare the headline AER alongside what happens after any promotional period.
We also examined the wider best Cash ISA rates and fixed ISA rates to identify where Coventry fits within the broader savings market.
Readers considering other established financial institutions may also find the Santander ISA rates, Virgin Money ISA rates and Leeds Building Society ISA rates relevant.
Our Rate Competitiveness Assessment
Rather than assigning an arbitrary customer satisfaction rating, we calculated how Coventry’s rates compare with the selected market benchmarks.
| Coventry product | Percentage of benchmark AER |
| Fixed ISA to November 2027 | 85.7% |
| Fixed ISA to November 2028 | 84.5% |
| Easy Access ISA | 41.1% |
These figures divide Coventry’s AER by the relevant comparison rate. They are not customer reviews, investment performance forecasts or comprehensive product quality scores.
The results suggest Coventry’s fixed accounts are closer to the quoted market leaders than its unrestricted easy-access account.
What Changed for Cash ISAs in the Autumn Budget 2026?
One of the biggest developments affecting Coventry Building Society ISA customers is the government’s reversal of its planned Cash ISA allowance reduction.
Under plans announced in 2025, people under 65 would have faced a £12,000 annual Cash ISA contribution limit from April 2027.
However, the Autumn Budget delivered on 28 October 2026 reversed that decision.
Chancellor John Healey confirmed:
The limit will stay at £20,000 per year, tax-free, for people of all ages.
The government subsequently confirmed that the legislation implementing the earlier reduction would be revoked.
Cash ISA Allowances for 2026/27 and 2027/28
| Allowance | 2026/27 | 2027/28 |
| Overall adult ISA allowance | £20,000 | £20,000 |
| Maximum Cash ISA subscriptions | £20,000 | £20,000 |
| Junior ISA allowance | £9,000 | £9,000 |
| Cash ISA interest tax | 0% | 0% |
The full adult ISA allowance can be divided between eligible ISA types, subject to the applicable rules. Savers cannot contribute £20,000 into a Cash ISA and another £20,000 into a Stocks and Shares ISA during the same tax year.
The reversal is particularly relevant for people who prefer cash savings over market-linked investments.
The Budget also proposed exploring a new incentive for first-time Stocks and Shares ISA investors. Its detailed eligibility and financial terms had not been finalised at the time of our review.
This development is also relevant to the UK Budget Starter Investment ISA, although that proposed investment incentive should not be confused with Coventry’s existing Cash ISA products.
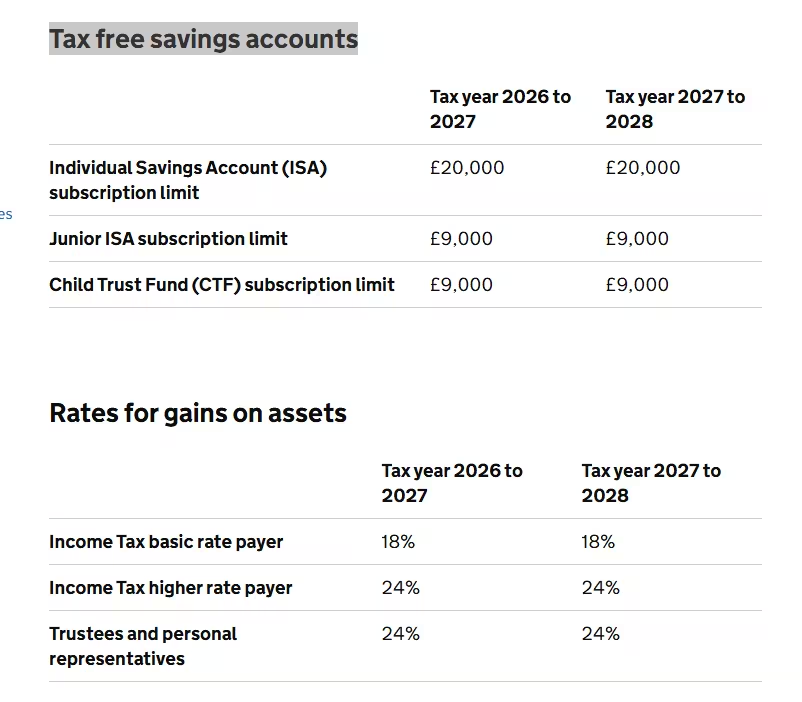
Official Budget 2026 tax allowances confirming the £20,000 annual ISA limit for both 2026/27 and 2027/28.
Will Savings Tax Changes Make Coventry Cash ISAs More Valuable in 2027?
The government has also announced higher Income Tax rates on taxable savings interest outside ISAs from 6 April 2027.
The planned rates are:
| Savings Income Tax band | 2026/27 | Planned 2027/28 |
| Basic | 20% | 24% |
| Higher | 40% | 44% |
| Additional | 45% | 49% |
These new rates are intended to apply across the UK and require the relevant legislation. Interest earned within a qualifying Cash ISA remains exempt from UK Income Tax.
How the Personal Savings Allowance Affects the Decision?
A saver should not automatically assume that an ISA is always better than an ordinary savings account.
The Personal Savings Allowance can protect some non-ISA savings interest from tax.
| Taxpayer category | Personal Savings Allowance |
| Basic-rate | £1,000 |
| Higher-rate | £500 |
| Additional-rate | £0 |
Consider somebody with £20,000 earning 4.50% interest.
The approximate annual return would be £900.
If a basic-rate taxpayer has no other taxable savings interest and qualifies for the full £1,000 allowance, that £900 could fall entirely within their Personal Savings Allowance even without an ISA.
For a higher-rate taxpayer, £400 of the £900 would exceed the £500 allowance. At the planned 44% rate, the illustrative tax liability on that excess would be £176.
Inside a qualifying Cash ISA, the £900 would remain exempt from Income Tax.
These examples assume the saver qualifies for the stated Personal Savings Allowance and ignore any other taxable savings interest, reliefs or circumstances.
Our assessment is that Cash ISAs can become particularly valuable for higher earners, people holding substantial cash savings and those expecting interest income to exceed their allowances.
Are Coventry Building Society ISAs Safe in 2026 and 2027?
Coventry Building Society is authorised and regulated as a UK financial institution, and eligible deposits benefit from Financial Services Compensation Scheme protection.
The FSCS deposit protection limit increased from £85,000 to £120,000 per eligible person, per authorised institution on 1 December 2025.
This protection generally applies to eligible deposits held across accounts covered by the same banking licence. It is not a separate £120,000 allowance for every account.
Does the Co-operative Bank Connection Affect Protection?
Coventry Building Society’s relationship with The Co-operative Bank is relevant to customers holding savings with both institutions.
Coventry’s published FSCS guidance explains that the two organisations currently operate under separate banking licences.
Accordingly, eligible deposits with each institution have separate FSCS protection limits of up to £120,000.
That position should be checked if the organisations’ banking arrangements change in the future.
Savings help
For context, this is an important distinction when comparing traditional building societies with providers that use partner-bank or platform arrangements, such as those discussed in our Trading 212 Cash ISA safety review.
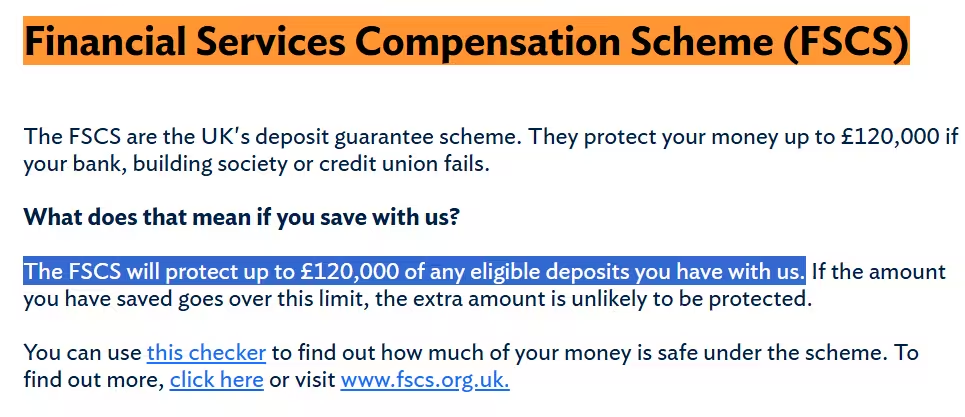
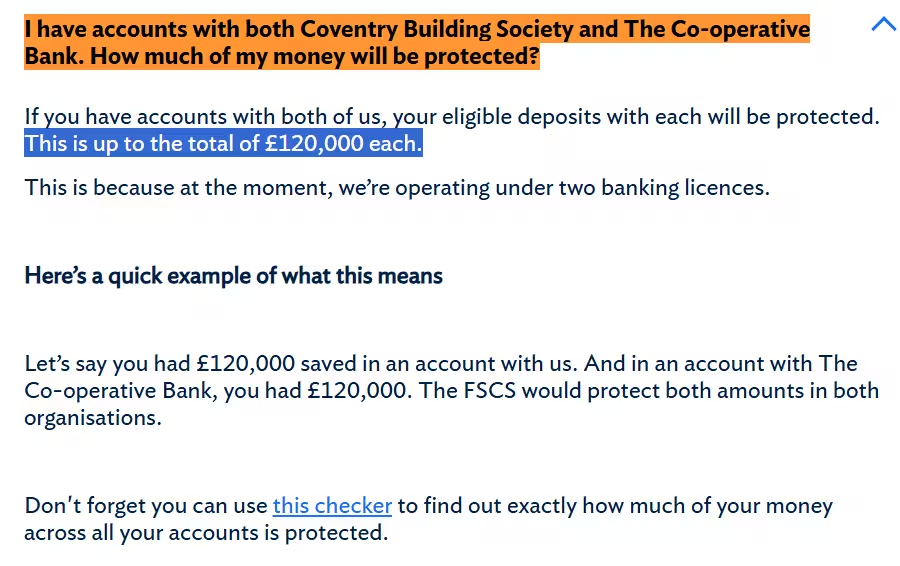
Coventry Building Society’s official FSCS guidance, showing the £120,000 deposit protection limit and how protection applies to Coventry and The Co-operative Bank.
Can You Transfer an Existing ISA to Coventry Building Society?
Yes. Coventry accepts eligible transfers from existing ISAs into several of its Cash ISA products.
An ISA transfer allows savings to move between providers while preserving their tax-free status.
The essential point is that transfers should be arranged through the receiving ISA provider rather than withdrawing the money into a normal bank account and depositing it again.
For somebody transferring a fixed ISA, the main considerations are the new interest rate and any charge imposed by the existing provider.
Our recommended transfer checks are:
- Confirm that the Coventry account is accepting applications and ISA transfers.
- Check whether your existing ISA imposes an early transfer or closure charge.
- Calculate the additional interest expected from the new account.
- Compare that benefit with all transfer-related charges.
- Initiate the transfer through Coventry’s official ISA transfer procedure.
Coventry’s particular product rules also matter. For example, its fixed account terms impose restrictions on how long customers have to arrange new deposits and transfers.
Although general UK ISA rules permit subscriptions to multiple Cash ISAs across providers, Coventry states that customers can pay into only one Cash ISA with Coventry during a tax year. The account-specific requirements should therefore be reviewed before transferring current-year subscriptions.
How Do You Open a Coventry Building Society Cash ISA?
For standard adult Cash ISAs, applicants generally need to be at least 18 years old, be UK residents and provide a National Insurance number.
Coventry offers applications and account management through several channels, depending on the product, including its website, mobile app, telephone service and branches.
The main steps are to select the desired ISA, review its Summary Box, confirm eligibility, complete identity checks and arrange a qualifying deposit or transfer.
A minimum initial balance of £1 is available on the Coventry products examined.
Before completing the application, it is worth checking whether the account’s rate is fixed or variable, how additional deposits work and whether access is restricted.
For fixed products, the applicable 14-day cancellation period is not the same as unrestricted access throughout the term.
Does Coventry Building Society Offer a Junior Cash ISA?
Coventry Building Society also offers a Junior Cash ISA for eligible children.
During our review, the Junior Cash ISA (2) paid 3.75% AER variable, with interest credited annually.
The annual Junior ISA subscription allowance is £9,000 for both 2026/27 and 2027/28.
Money saved in a Junior ISA belongs to the child and is normally inaccessible until age 18, apart from specific exceptions provided by the rules.
Parents comparing children’s long-term savings options should consider the difference between a Junior Cash ISA and investment-based alternatives, especially when the investment horizon extends over many years.
A Junior Cash ISA should also not be confused with a Lifetime ISA. The latter has different eligibility, government bonus and withdrawal rules, as discussed in our Moneybox Lifetime ISA review.
Are Coventry Cash ISAs Suitable for Business Owners and Entrepreneurs?
Cash ISAs are personal savings products, not substitutes for business bank accounts.
However, they may form part of a business owner’s personal financial planning strategy.
Entrepreneurs, sole traders and company directors often face irregular personal income patterns. That can make financial flexibility particularly important.
From a financial planning perspective, the distinction should be between capital needed to run the business and money already available for personal saving.
For example, a company director may build personal savings using legitimately withdrawn salary or dividends. Those personal funds can potentially be contributed to an ISA within the annual subscription allowance.
Company cash, however, should not simply be transferred into a director’s personal ISA without considering the legal and tax treatment of the withdrawal.
A Practical Savings Allocation Example
Consider somebody holding £30,000 in personal savings.
They might consider the following illustrative allocation:
| Purpose | Amount | Approach |
| Emergency reserves | £10,000 | Accessible savings |
| Medium-term savings | £10,000 | Limited-access or shorter fixed term |
| Longer-term savings | £10,000 | Fixed Cash ISA |
| Total | £30,000 | Mixed access strategy |
This is an example of balancing liquidity and rate certainty, not a universal recommended allocation.
The exact split should depend on income stability, emergency expenditure, outstanding liabilities and when the money may be required.
Our assessment is that business owners should be particularly cautious about locking away money they may need to cover personal living costs during periods of lower business income.
What Should Savers Expect From Coventry Building Society ISA Rates in 2027?
Future rates for new applications are not guaranteed by the rates currently advertised.
The 4.30%, 4.35% and 4.50% fixed offers apply to the specific products and maturity dates described in their terms.
A new fixed-rate account launched during 2027 could offer a higher or lower rate depending on market conditions and Coventry’s funding requirements.
Variable-rate accounts are also subject to changes before and during 2027.
Savers planning ahead should monitor four main factors: changes to the Bank of England’s monetary policy, new Coventry product issues, competing Cash ISA rates and upcoming maturity dates.
One particularly important issue is what happens when a fixed ISA matures.
Coventry explains that its fixed ISAs can move into a default replacement ISA unless the customer chooses another option. Customers should review the replacement rate rather than assuming the original fixed rate will continue.
For the November 2027 account, that means reviewing the maturity correspondence before 30 November 2027 and comparing available alternatives.
What Is Our Overall Review of Coventry Building Society ISA Rates?
Based on the published account conditions and November 2026 rate comparisons, Coventry’s strongest feature is the availability of several savings structures within one building society.
Its fixed Cash ISAs provide interest-rate certainty, while its 6 Access ISA offers an intermediate option for savers who can limit withdrawals.
The £1 minimum balance on the reviewed products also makes them accessible to people starting with relatively small amounts.
However, the broader market comparison reveals that higher rates can be available elsewhere. Coventry’s unrestricted Easy Access ISA is particularly far below the highest promotional easy-access rates included in our comparison.
| Assessment area | Our findings |
| Fixed-rate choice | Several maturity options through 2029 |
| Highest reviewed Coventry AER | 4.50% |
| Flexible access | Available on the 6 Access and Easy Access products |
| Early closure terms | Potentially substantial charges on fixed ISAs |
| Minimum opening balance | £1 on the main reviewed products |
| Deposit protection | Eligible deposits protected up to £120,000 |
| Market competitiveness | Fixed products relatively closer to comparison leaders than easy access |
Our verdict: Coventry is worth considering for savers who value a familiar building society, clearly defined account structures and fixed-rate certainty.
Nevertheless, someone prioritising the highest available interest rate should compare the wider UK Cash ISA market before opening an account.
Conclusion
Coventry Building Society ISA rates provide several opportunities for UK savers planning their finances for 2027.
Its reviewed fixed-rate products offer between 4.30% and 4.50% AER, while variable-rate accounts provide alternatives for people requiring access to their money.
Our analysis indicates that the fixed accounts offer more competitive returns than Coventry’s unrestricted Easy Access ISA, although early closure charges require careful consideration.
The decision to retain the £20,000 annual Cash ISA allowance from April 2027 is particularly significant.
Savers should compare interest rates, account flexibility, tax treatment and deposit protection before selecting an ISA that matches their financial goals.
Frequently Asked Questions
What Is the Highest Coventry Building Society ISA Rate?
The highest rate in the November 2026 range reviewed is 4.50% AER on the Fixed Rate ISA maturing on 30 November 2029. Availability and rates for new applications can change.
Will Coventry Building Society ISA Rates Increase in 2027?
There is no guaranteed increase. New product rates will depend on market conditions, while existing fixed-rate accounts retain their contracted rates until maturity.
What Is the Coventry Building Society Easy Access ISA Rate?
The Easy Access ISA (12) pays 2.00% AER variable in the reviewed listings. It offers unlimited charge-free withdrawals and qualifies as a flexible ISA.
Can I Put £20,000 Into a Coventry Cash ISA in 2027?
The government has confirmed that the annual Cash ISA allowance will remain £20,000 from 6 April 2027. Contributions must remain within the overall ISA allowance and the account’s own rules.
Are Coventry Building Society ISA Savings Protected?
Yes. Eligible deposits have FSCS protection of up to £120,000 per person, per authorised institution, subject to the scheme’s conditions.
Can I Withdraw Money From a Coventry Fixed Rate ISA?
Partial withdrawals are generally prohibited after the cancellation period on the fixed accounts reviewed. Early closure or transfer may be possible with an interest charge.
Can I Transfer My Cash ISA From Another Bank to Coventry?
Yes, where the chosen Coventry account accepts ISA transfers. Use the official ISA transfer process and check whether the existing provider charges a penalty.
Is Coventry Building Society Better Than Other Cash ISA Providers?
That depends on the saver’s priorities. Coventry offers fixed-rate certainty and several access options, but some competing products pay higher rates or have different withdrawal and transfer conditions.
More in Finance & Tax
Skipton Building Society ISA Rates 2027: Latest Cash ISA Rates and 2026 Updates
Skipton Building Society ISA rates currently reach 5.05% AER tax-free on its five-year fixed-rate Cash ISA, while its 15-month fixed account offers 4.90% and its Bonus Cash ISA Saver pays 4.21% variable, including a temporary introductory bonus. For savers preparing their finances for 2027, these rates create different opportunities depending on how long they can […]
Newcastle Building Society ISA Rates 2027: Latest Cash ISA Rates, 2026 Updates and Expert Review
Newcastle Building Society ISA rates are attracting attention from UK savers preparing their finances for 2027. With fixed-rate Cash ISAs offering up to 4.90% AER, a one-year fixed ISA paying 4.70%, and limited-access savings options available, Newcastle provides several ways to earn tax-free interest. The October 2026 Autumn Budget also brought an important change. The […]