Virgin Money ISA rates currently reach 4.77% AER tax-free, with three main Cash ISA options available to savers: a one-year fixed account, a limited-access account and a flexible easy-access ISA for eligible Virgin Money current-account customers.
As of 7 October 2026, the strongest rate is the 1 Year Fixed Rate Cash E-ISA Issue 708 at 4.77% AER, followed by the Double Take E-ISA Issue 19 at 4.15% AER variable and the M Access ISA at 3.25% AER variable.
The headline percentage, however, is only part of the decision.
Virgin Money is now part of Nationwide, the two brands share a combined FSCS deposit-protection limit, Virgin applies its own restriction on subscribing to its Cash ISAs, and its fixed Cash ISA has a defined funding window and an early-withdrawal charge.
There is also an important change coming on 6 April 2027, when the amount most people under 65 can subscribe to Cash ISAs falls from £20,000 to £12,000.
We have therefore assessed Virgin Money’s ISA range not simply on the advertised AER but on rate competitiveness, accessibility, transfers, flexibility, penalties and practical usefulness for savers, freelancers, company directors and entrepreneurs managing personal cash reserves.
What Are the Current Virgin Money ISA Rates?
The Virgin Money Cash ISA range checked on 7 October 2026 is:
| Virgin Money ISA | Current rate | Rate type | Minimum deposit | Access |
| 1 Year Fixed Rate Cash E-ISA Issue 708 | 4.77% AER | Fixed | £1 | Withdrawals allowed with 60 days’ interest charge |
| Double Take E-ISA Issue 19 | 4.15% AER | Variable | £1 | Up to two withdrawals per calendar year |
| M Access ISA | 3.25% AER | Variable | £0 | Easy access; flexible ISA |
The 4.77% one-year fixed rate is currently Virgin Money’s strongest Cash ISA rate.
However, each product is aimed at a different type of saver.
Someone with £20,000 that will definitely not be required for around a year may reasonably favour the fixed account.
Someone who wants a competitive rate but expects no more than one or two withdrawals could prefer Double Take.
The M Access ISA sacrifices a substantial amount of interest in return for much greater freedom.
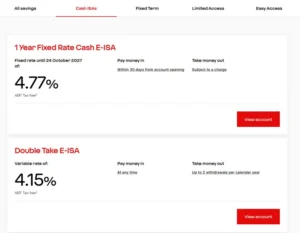
Virgin Money’s savings range showing the current 4.77% fixed Cash ISA, 4.15% Double Take E-ISA and 3.25% M Access ISA rates, checked in October 2026.
Rates on savings products can move quickly. Variable rates can change after opening, while limited-issue accounts can be withdrawn and replaced with a new issue.
Which Virgin Money ISA Pays the Highest Rate?
The 1 Year Fixed Rate Cash E-ISA Issue 708 pays 4.77% AER tax-free, making it the highest-paying Cash ISA currently offered in Virgin Money’s online range.
The interest rate is fixed until 24 October 2027.
A fixed rate gives the saver certainty. Even if general savings rates fall during the term, the account continues paying its contracted rate.
That certainty has a cost: access is less flexible.
Virgin Money allows withdrawals, but an early withdrawal is subject to a charge equivalent to 60 days’ interest on the amount withdrawn.
There is also a funding deadline.
Money needs to reach the account within 30 days of opening. Virgin Money states that the account will close if no money is received within that period.
This makes the account more appropriate for an existing lump sum than for somebody intending to build their ISA gradually throughout the year.
How Much Interest Could the 4.77% Virgin Money ISA Pay?
Assuming a saver receives the full 4.77% AER for a year and makes no withdrawals, approximate returns would be:
| Amount saved | Rate | Approximate annual interest | Approximate balance |
| £1,000 | 4.77% | £47.70 | £1,047.70 |
| £5,000 | 4.77% | £238.50 | £5,238.50 |
| £10,000 | 4.77% | £477.00 | £10,477.00 |
| £15,000 | 4.77% | £715.50 | £15,715.50 |
| £20,000 | 4.77% | £954.00 | £20,954.00 |
These figures are illustrative. The precise return can depend on when money is deposited and how interest is paid.
For someone using the full £20,000 2026/27 ISA allowance, a 4.77% annual return equates to roughly £954 of tax-free interest.
That illustrates why differences of even 0.10 or 0.20 percentage points deserve attention when larger ISA balances are involved.
How Competitive Is Virgin Money’s 4.77% Fixed ISA?
Virgin Money is competitive, but it is not currently the highest-paying one-year Cash ISA in the entire UK market.
Recent October 2026 market comparisons show leading one-year fixed Cash ISA rates of around 4.9% or slightly above, with MoneySavingExpert listing a market-leading conventional one-year rate of approximately 4.94% AER when checked.
That leaves Virgin Money roughly 0.17 percentage points behind a 4.94% account.
On £20,000:
| One-year rate | Approximate interest |
| Virgin Money at 4.77% | £954 |
| Alternative at 4.94% | £988 |
| Approximate difference | £34 |
A £34 difference over one year is not enormous.
For some savers, Virgin Money’s £1 minimum deposit, established banking infrastructure and familiarity may outweigh it.
For somebody transferring £80,000 or £100,000 accumulated over previous tax years, however, small percentage-point differences become considerably more significant.
Anyone primarily chasing the highest available return should compare the wider best Cash ISA rates in the UK before committing.
How Does the Virgin Money 1 Year Fixed Rate Cash E-ISA Work?
The fixed ISA is relatively straightforward.
Funding
The minimum opening amount is only £1.
Customers can use new ISA subscriptions and can also transfer eligible existing ISAs.
New contributions remain subject to the applicable annual ISA subscription limit.
The account has a 30-day funding window, so it is important not to open it months before the money is available.
Interest
The annual interest rate is 4.77%.
Virgin Money also offers a monthly-interest option, where the underlying monthly tax-free rate is lower but produces the same stated 4.77% AER when calculated on an equivalent annual basis.
ISA transfers
Transfers from existing Cash ISAs and Stocks and Shares ISAs are currently accepted under the applicable rules.
Using an official ISA transfer is particularly important where previous years’ ISA balances are involved.
Withdrawing an old ISA into an ordinary current account and then paying the money into a new ISA is not the same thing as completing an ISA transfer.
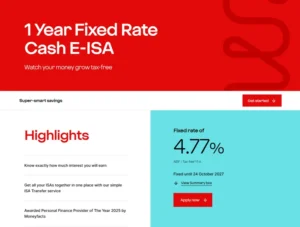
Virgin Money’s 1 Year Fixed Rate Cash E-ISA summary showing the 4.77% AER fixed rate and 24 October 2027 maturity date.
What Does It Cost to Withdraw From the Virgin Money Fixed ISA Early?
Virgin Money applies a charge equivalent to 60 days’ loss of interest on the amount withdrawn during the fixed-rate period.
For perspective, an approximate 60-day interest cost at 4.77% would be:
| Amount withdrawn | Approximate 60-day interest |
| £1,000 | £7.84 |
| £5,000 | £39.21 |
| £10,000 | £78.41 |
| £20,000 | £156.82 |
These are illustrative calculations rather than quotes of the exact charge Virgin Money would apply to an individual withdrawal.
The financial point is more important than the precise pennies.
A fixed ISA paying a slightly higher rate may not be the better account if there is a realistic chance that the money will be required unexpectedly.
This consideration is particularly relevant to freelancers, contractors and business owners whose personal drawings or income can fluctuate.
An emergency fund should generally remain accessible rather than being placed entirely inside an account that penalises withdrawals.
Is the Double Take E-ISA Better for Flexible Saving?
The Double Take E-ISA Issue 19 pays 4.15% AER variable.
It sits between a conventional fixed ISA and a true easy-access account.
Customers can add money during the year and can make up to two withdrawals per calendar year.
After the second withdrawal, additional ordinary withdrawals cannot be made until the next calendar year.
A saver can, however, request a full closure or closing ISA transfer.
This restriction makes the name “Double Take” fairly descriptive: the account works best for money that is expected to remain untouched apart from one or two planned withdrawals.
For example, it could suit someone saving towards:
- A tax bill
- A home improvement project
- A future vehicle purchase
- A large annual insurance premium
- A personal contingency reserve that is unlikely to be used frequently
It is less suitable as an everyday emergency account where withdrawals may be unpredictable.
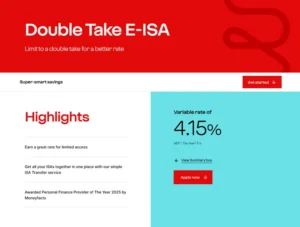
Double Take E-ISA Issue 19 showing the 4.15% variable rate and limit of two withdrawals per calendar year.
How Much Could the Double Take E-ISA Pay?
At the current 4.15% variable rate, and assuming the rate remained unchanged for a full year:
| Balance | Approximate annual interest |
| £1,000 | £41.50 |
| £5,000 | £207.50 |
| £10,000 | £415 |
| £20,000 | £830 |
| £50,000 | £2,075 |
Unlike the fixed ISA, the 4.15% rate is not guaranteed for a year.
Virgin Money can increase or reduce it.
That means the projected £830 on £20,000 should not be interpreted as a guaranteed return.
Is the Double Take ISA Flexible?
This is where the word “flexible” needs to be used carefully.
A savings account allowing withdrawals is not automatically a Flexible ISA for HMRC allowance purposes.
Virgin Money specifically identifies its easy-access M Access ISA as flexible.
The Double Take E-ISA is instead marketed as a limited-access ISA.
Savers should therefore not assume that withdrawing money from Double Take and subsequently paying it back will receive the same allowance treatment as withdrawing and replacing money from the M Access ISA.
That distinction is frequently missed when Cash ISAs are compared purely by interest rate.
What Is the Virgin Money M Access ISA Rate?
The M Access ISA currently pays 3.25% AER tax-free variable.
The account allows money to be added and withdrawn without notice and is a Flexible ISA.
However, eligibility is restricted.
Applicants need an eligible Virgin Money personal current account, such as an M Plus Account, M Account or Club M Account.
Virgin Money states that holders of an Essential Current Account or Virgin Money Current Account do not qualify.
There is no minimum opening balance.
Why Does the M Access ISA Pay Less?
The 3.25% rate is substantially below Virgin Money’s 4.77% fixed rate.
The difference is essentially the price of flexibility.
Someone with £20,000 would generate approximately:
- £954 at 4.77%
- £830 at 4.15%
- £650 at 3.25%
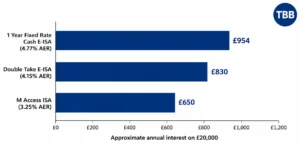
The difference between the fixed ISA and M Access is approximately £304 over a year on £20,000, assuming the variable M Access rate remained unchanged.
A saver should therefore ask whether unrestricted access is worth approximately £304 a year on that balance.
For someone with volatile income, it may be.
For someone holding cash they know will not be touched, probably not.
Why Is the M Access ISA’s Flexible Status Important?
A Flexible ISA allows qualifying withdrawals to be replaced within the same tax year without necessarily using additional ISA allowance.
Suppose someone pays £15,000 into the M Access ISA during 2026/27.
They later withdraw £5,000.
Because it is flexible, that £5,000 can generally be replaced in the same account before the end of the tax year without being treated as another £5,000 of ordinary ISA subscription.
That feature can be particularly useful for people with irregular personal cash flow.
A company director, consultant or freelancer might temporarily need money for a large personal expense and then replenish the ISA after receiving dividends, salary or self-employed income.
For more detail on the wider rules, see whether you can have more than one ISA.
Can You Pay Into More Than One Virgin Money Cash ISA?
Virgin Money applies a restriction that deserves particular attention.
Although wider ISA rules now generally allow people to subscribe to multiple ISAs of the same type subject to the overall annual allowance, Virgin Money says customers can only subscribe to one Virgin Money Cash ISA during a tax year.
That is a provider-specific condition.
It does not necessarily mean somebody who pays into a Virgin Money Cash ISA is prohibited from using another provider’s Cash ISA, provided all current ISA rules and overall contribution limits are followed.
For example, an eligible saver might potentially allocate the 2026/27 allowance as:
| Account | Contribution |
| Virgin Money Cash ISA | £10,000 |
| Cash ISA with another provider | £5,000 |
| Stocks and Shares ISA | £5,000 |
| Total | £20,000 |
The critical point is that Virgin Money’s own account conditions still need to be observed.
How Much Can You Put Into a Virgin Money ISA in 2026/27?
The overall adult ISA allowance for 2026/27 is £20,000.
The tax year runs from 6 April 2026 to 5 April 2027.
Existing ISA balances from earlier tax years do not automatically use the new £20,000 allowance simply because they remain inside an ISA.
This means somebody could already have £100,000 accumulated in old ISAs and still receive a new annual subscription allowance.
Eligible existing ISA money can also be moved through the formal ISA-transfer system rather than being treated as a new contribution.
Anyone planning contributions around the end of the tax year can also check when the ISA allowance resets.
What Changes to Cash ISAs From April 2027?
A substantial ISA reform takes effect on 6 April 2027.
For people under 65, the annual Cash ISA subscription limit falls to:
£12,000
The overall adult ISA allowance remains:
£20,000
For people aged 65 or over, the Cash ISA limit remains:
£20,000
So an under-65 saver wanting to use the full allowance in 2027/28 could potentially have:
| ISA type | Example contribution |
| Cash ISA | £12,000 |
| Stocks and Shares ISA | £8,000 |
| Total | £20,000 |
That does not mean everybody should invest the remaining £8,000.
Stocks and shares can fall in value. The appropriate choice depends on time horizon, tolerance for investment risk and the purpose of the money.
The 2026/27 tax year is therefore significant because it is the final tax year before the lower Cash ISA subscription limit applies to most under-65s.
Can You Transfer an Existing ISA to Virgin Money?
Yes. Virgin Money’s current Cash ISA range accepts eligible ISA transfers.
For savers with large amounts accumulated over previous years, transfers can be particularly useful because properly transferred previous-year ISA balances generally do not use the current year’s normal contribution allowance.
The process should be completed through the receiving provider.
Avoid withdrawing ISA money into an ordinary bank account merely to move it.
Once money leaves the ISA wrapper, restoring its previous tax-protected position may not be possible, particularly when the balance exceeds the available annual allowance.
What Does the Nationwide Takeover Mean for Virgin Money ISA Customers?
This is now an important part of any Virgin Money ISA review.
Virgin Money’s business transferred to Nationwide Building Society on 2 April 2026.
The Virgin Money brand continues to appear on its banking and savings products, but there are practical consequences for savers.
One of the most important concerns FSCS protection.
Eligible deposits held across Virgin Money and Nationwide are now considered together when applying the standard deposit-protection limit.
Is Money in a Virgin Money ISA FSCS Protected?
Eligible deposits are covered by the Financial Services Compensation Scheme, but Virgin Money and Nationwide now share a combined £120,000 protection limit per eligible person.
This means a person should not assume they have:
- £120,000 protection at Virgin Money plus
- Another £120,000 at Nationwide.
For example, someone holding:
- £80,000 with Virgin Money
- £70,000 with Nationwide
has £150,000 across the two brands.
Subject to eligibility and the normal FSCS rules, the ordinary combined protection ceiling would be £120,000 rather than £240,000.
This is particularly relevant for people transferring large Cash ISA balances accumulated over many years.
Those already holding substantial Nationwide savings should account for them before moving a large ISA to Virgin Money.
Our analysis of current Nationwide ISA rates provides a useful comparison because the two brands are now connected for FSCS purposes.
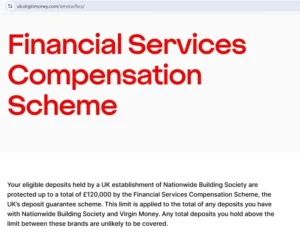
Virgin Money’s FSCS information explaining that eligible Virgin Money and Nationwide deposits share the £120,000 protection limit.
What Happens When a Virgin Money Fixed Cash ISA Matures?
There is another significant change following the Nationwide transfer.
Virgin Money says it will no longer offer a Virgin Money Fixed Rate Cash ISA as the reinvestment option when an existing fixed Cash ISA reaches maturity.
Instead, customers can be offered the option of reinvesting into a Nationwide Transfer Fixed Rate Cash ISA.
Alternatively, they may be able to transfer their ISA elsewhere or withdraw the money, subject to the applicable maturity instructions.
This makes the maturity date more important than it might initially appear.
Someone opening the current 4.77% Virgin Money fixed ISA should not assume that, when the term finishes, another equivalent Virgin Money-branded fixed ISA will automatically be available.
The rate and terms available through Nationwide at that point could be different.
How Does Virgin Money Compare With Nationwide, Santander and Halifax?
Among established UK banking names, Virgin Money’s 4.77% one-year fixed rate is currently particularly competitive.
For comparison, readers considering major providers can examine the latest:
The important point is not to compare brand against brand without comparing equivalent products.
A one-year fixed ISA should ideally be compared with another one-year fixed ISA.
A limited-access account should be compared with accounts imposing similar withdrawal conditions.
An easy-access flexible ISA should be assessed against other flexible easy-access products.
Otherwise, a headline rate table can be misleading.
Is a Virgin Money Cash ISA Worth It for Business Owners?
A Cash ISA is a personal savings product, not a business deposit account.
A limited company cannot simply place company cash directly into a director’s personal Cash ISA.
Money first needs to belong to the individual through an appropriate route, such as salary, dividends or another legitimate extraction method, with the associated tax and accounting treatment considered separately.
Once the funds are genuinely personal money, the individual can consider an ISA in the normal way.
For sole traders, the legal separation is different because the trader and business are not separate legal persons, although keeping adequate funds available for tax and working-capital obligations remains important.
This is why we would not automatically recommend locking every available pound into the highest-rate ISA.
Entrepreneurs frequently have less predictable personal cash flow than employees receiving the same salary every month.
A practical structure might therefore involve:
- Keeping immediate emergency money in easy access.
- Keeping expected short-term expenditure accessible.
- Separating money required for business or tax obligations.
- Using a higher-rate Cash ISA for genuinely surplus personal cash.
- Fixing only the portion unlikely to be required during the fixed term.
The highest percentage does not help if the saver repeatedly needs to break the account and pay withdrawal charges.
Is a Cash ISA Better Than an Ordinary Savings Account?
Not automatically.
The principal benefit of a Cash ISA is that qualifying interest remains sheltered from UK Income Tax.
Ordinary savings accounts can sometimes offer higher interest rates.
The Personal Savings Allowance also means many people can already receive a certain amount of ordinary savings interest without paying tax.
For 2026/27, the Personal Savings Allowance is generally:
| Tax position | Personal Savings Allowance |
| Basic-rate taxpayer | £1,000 |
| Higher-rate taxpayer | £500 |
| Additional-rate taxpayer | £0 |
Consider somebody with only £20,000 of savings.
At 4.77%, annual interest would be approximately £954.
A basic-rate taxpayer who has no other taxable savings interest could potentially remain within the £1,000 Personal Savings Allowance even outside an ISA.
The immediate tax advantage of the ISA may therefore be limited.
For a higher-rate taxpayer, an additional-rate taxpayer, or someone with substantially larger cash savings, the ISA wrapper can become more valuable.
There is also a long-term advantage: ISA money remains sheltered rather than relying every year on the Personal Savings Allowance remaining sufficient.
Our Virgin Money ISA Review and Percentage Ratings
For this review, we considered the product range from the perspective of people who care about both return and practical cash management.
These are our editorial percentage scores, not Virgin Money customer-survey results.
| Category | Our rating |
| Interest-rate competitiveness | 96% |
| Minimum deposit accessibility | 99% |
| ISA transfer support | 95% |
| Product clarity and transparency | 92% |
| Access and flexibility | 82% |
| Range of Cash ISA options | 78% |
| Suitability for entrepreneurs/self-employed savers | 86% |
| Overall editorial rating | 90% |
Interest-rate competitiveness: 96%
The 4.77% fixed account sits relatively close to the best one-year fixed Cash ISA rates available nationally.
Virgin Money is therefore highly competitive among recognisable mainstream banking names.
Minimum deposit accessibility: 99%
A £1 minimum on the fixed and Double Take ISAs removes one of the common barriers found with some competing fixed-rate products.
The M Access ISA does not require a minimum opening balance.
Transfer support: 95%
Virgin Money accepts eligible ISA transfers, which is essential for people moving substantial amounts accumulated in previous tax years.
Access and flexibility: 82%
There is a good spread of choices, but compromises remain.
The fixed ISA charges 60 days’ interest for withdrawals, Double Take limits ordinary withdrawals to twice a calendar year, and the genuinely flexible M Access ISA pays only 3.25% and has current-account eligibility requirements.
Product range: 78%
The range covers the three main needs reasonably well — fixed, limited access and easy access — but it is not particularly broad.
Savers seeking multiple fixed terms or the absolute highest easy-access rate will need to compare the wider market.
What We Like About Virgin Money’s ISA Range?
The strongest points are:
- 4.77% fixed AER is highly competitive
- The fixed and Double Take accounts can be opened from £1
- Existing eligible ISAs can be transferred in
- Customers have a choice between fixed, limited and easy access
- M Access offers genuine Flexible ISA functionality
- Virgin Money provides clear summary boxes explaining rates and withdrawal conditions
- The 60-day fixed-ISA withdrawal charge is lower than some fixed products charging several months of interest
What Could Be Better?
There are also clear disadvantages:
- The 4.77% rate is not currently the highest one-year Cash ISA rate in the market
- M Access pays only 3.25%
- M Access requires an eligible Virgin Money current account
- Double Take restricts savers to two ordinary withdrawals per calendar year
- Virgin Money permits subscriptions to only one of its own Cash ISAs per tax year
- Virgin Money and Nationwide no longer provide separate FSCS protection limits
- Fixed Cash ISA maturity arrangements are moving towards Nationwide products
- Variable rates can fall after an account has been opened
Who Is the Virgin Money 1 Year Fixed ISA Best For?
It is strongest for somebody who:
- Has a lump sum ready now
- Wants a guaranteed rate
- Does not expect to need regular access
- Values an established mainstream banking brand
- Wants to transfer an existing ISA
- Does not want a high minimum opening deposit
It is weaker for somebody with unpredictable short-term cash requirements.
Who Is the Double Take E-ISA Best For?
It may suit somebody who:
- Wants a higher variable rate than Virgin’s unrestricted M Access ISA
- Can reasonably limit withdrawals to two per calendar year
- Wants to keep adding savings
- Does not want to commit to a fixed term
- Wants to transfer an existing ISA
It is not a substitute for a true everyday easy-access emergency fund.
Who Is the M Access ISA Best For?
The M Access ISA makes more sense for an eligible Virgin Money current-account customer who prioritises:
- Unlimited access
- Flexible ISA functionality
- Regular deposits
- No minimum balance
- Branch, online and mobile management
The compromise is the comparatively low 3.25% AER.
Final Verdict: Are Virgin Money ISA Rates Good in 2026?
Virgin Money’s ISA rates are competitive overall, with the 4.77% one-year fixed Cash E-ISA being the standout product.
It is close enough to the top of the wider one-year market that savers who value Virgin Money’s accessibility, low £1 minimum and established banking infrastructure may find the small rate difference acceptable.
The Double Take E-ISA at 4.15% offers a useful middle ground but requires discipline because of its two-withdrawal limit.
The 3.25% M Access ISA provides the most freedom and genuine ISA flexibility, but its return is considerably less attractive.
Our overall assessment is 90%, led primarily by the competitiveness of the one-year fixed account, low minimum deposits and strong transfer support.
The biggest considerations are now broader than the headline ISA rate.
Virgin Money and Nationwide share one £120,000 FSCS limit, Virgin’s fixed ISA maturity process is moving towards Nationwide products, and the Cash ISA subscription limit for most under-65s falls to £12,000 from 6 April 2027.
For those reasons, a saver choosing Virgin Money today should compare rate, access, tax treatment, existing Nationwide deposits and likely cash requirements, rather than choosing solely because 4.77% is the largest number in Virgin Money’s current range.
Frequently Asked Questions
What is the current Virgin Money ISA rate?
Virgin Money currently offers Cash ISA rates of 4.77%, 4.15% and 3.25% AER, depending on the account. Rates were checked on 7 October 2026.
What is Virgin Money’s best ISA rate?
The highest current rate is 4.77% AER tax-free on the 1 Year Fixed Rate Cash E-ISA Issue 708.
Is Virgin Money’s 4.77% ISA fixed?
Yes. The 4.77% rate is fixed until 24 October 2027 for the current issue.
Can I withdraw from the Virgin Money fixed ISA?
Yes, but withdrawals during the fixed term are subject to a charge equivalent to 60 days’ loss of interest on the amount withdrawn.
How many withdrawals can I make from the Double Take E-ISA?
The account permits two ordinary withdrawals per calendar year. After the second, further ordinary withdrawals are restricted until the next calendar year, although full closure or a closing transfer remains possible.
Is the Virgin Money M Access ISA flexible?
Yes. The M Access ISA is a Flexible ISA, allowing qualifying withdrawn money to be replaced during the same tax year without normally using additional ISA allowance.
Can I transfer an existing ISA to Virgin Money?
Yes. Virgin Money currently accepts eligible Cash ISA and Stocks and Shares ISA transfers into its Cash ISA products, subject to individual account conditions.
Can I pay into more than one Virgin Money Cash ISA?
Virgin Money states that customers can only subscribe to one Virgin Money Cash ISA in a tax year, even though wider ISA rules can permit multiple Cash ISA subscriptions across providers.
Is Virgin Money part of Nationwide?
Yes. Virgin Money’s business transferred to Nationwide Building Society on 2 April 2026.
Do Virgin Money and Nationwide have separate £120,000 FSCS limits?
No. Eligible deposits across the two brands are aggregated and share the standard £120,000 per-person FSCS protection limit.
What happens to a Virgin Money fixed ISA at maturity?
Virgin Money says maturing fixed Cash ISA customers will no longer be offered another Virgin Money Fixed Rate Cash ISA as the reinvestment option. A Nationwide Transfer Fixed Rate Cash ISA can instead be offered, alongside other transfer or withdrawal choices.
How much can I put into a Cash ISA in 2026/27?
The overall adult ISA allowance remains £20,000 for 2026/27. From 6 April 2027, most people under 65 will be restricted to £12,000 of annual Cash ISA subscriptions while the overall £20,000 ISA limit remains.
Is Virgin Money’s ISA worth it?
The 4.77% fixed ISA is competitive for savers who can leave their money largely untouched for the fixed term. People needing unrestricted access should compare easy-access alternatives before choosing solely on rate.
More in Finance & Tax
Best 1 Year Fixed Rate ISA UK 2026: Top Cash ISA Rates Compared
The best 1 year fixed rate ISA in the UK currently pays up to 4.98% AER tax-free, with UBL UK offering the highest verified rate in our October 2026 comparison. Shawbrook Bank follows at 4.97%, while Vanquis Bank offers a competitive 4.96% alongside a lower minimum opening deposit. However, choosing the best one-year fixed Cash […]
Moneybox Lifetime ISA Review 2026: Interest Rates, Bonuses, Fees and Is It Worth It?
The Moneybox Lifetime ISA is a UK savings and investment account designed to help eligible adults save for their first home or retirement. It offers a 25% government bonus on contributions of up to £4,000 each tax year, potentially adding £1,000 annually to a saver’s money. Moneybox offers both Cash and Stocks & Shares Lifetime […]