Leeds Building Society ISA rates currently reach 4.90% AER tax-free, with fixed-rate Cash ISAs available over one, two, three and five years. Savers can also choose an Online Access Cash ISA paying 4.16% AER variable, alongside monthly-income and limited-access products.
However, the highest interest rate does not automatically represent the best account. Withdrawal charges, maturity dates, minimum balances and ISA transfer restrictions can significantly influence the return savers actually receive.
We analysed the society’s published interest rates, product conditions, tax-free savings rules and competing ISA options to assess the financial advantages and limitations of its accounts.
Our review also considers how self-employed professionals, business owners and households can use Cash ISAs within their wider financial planning, particularly ahead of the changes to UK ISA allowances in April 2027.
What Are the Current Leeds Building Society ISA Rates in 2026?
As of 13 October 2026, Leeds Building Society offers fixed and variable-rate Cash ISAs, with advertised rates ranging from 1.45% to 4.90% AER across its listed adult products.
The strongest fixed rate currently available is 4.90% AER on the five-year account, while its highest listed unlimited-access Cash ISA pays 4.16% AER variable.
Leeds Building Society ISA Rates Comparison Table
| Cash ISA product | Interest rate | Minimum deposit | Withdrawal conditions |
| 1 Year Fixed Rate Cash ISA (Issue 242) | 4.70% fixed | £100 | 90 days’ interest penalty |
| 2 Year Fixed Rate Cash ISA (Issue 230) | 4.80% fixed | £100 | 180 days’ interest penalty |
| 3 Year Fixed Rate Cash ISA (Issue 186) | 4.85% fixed | £100 | 270 days’ interest penalty |
| 5 Year Fixed Rate Cash ISA (Issue 181) | 4.90% fixed | £100 | 365 days’ interest penalty |
| 1 Year Fixed Rate Monthly Income Cash ISA (Issue 22) | 4.70% fixed | £100 | 90 days’ interest penalty |
| 2 Year Fixed Rate Monthly Income Cash ISA (Issue 20) | 4.80% fixed | £100 | 180 days’ interest penalty |
| 3 Year Fixed Rate Monthly Income Cash ISA (Issue 20) | 4.85% fixed | £100 | 270 days’ interest penalty |
| 5 Year Fixed Rate Monthly Income Cash ISA (Issue 22) | 4.90% fixed | £100 | 365 days’ interest penalty |
| Online Access Cash ISA (Issue 23) | 4.16% variable | £1,000 | Unlimited withdrawals |
| Six Access ISA | 3.10% variable | £1,000 | Six withdrawals per calendar year without penalty |
| E-ISA | 1.45% variable | £1 | Unlimited withdrawals |
| ISA Saver | 1.45% variable | £1 | Unlimited withdrawals |
All rates are tax-free p.a./AER. Product issues and rates can change or be withdrawn. The terms shown are those published for the listed issues at the review date.
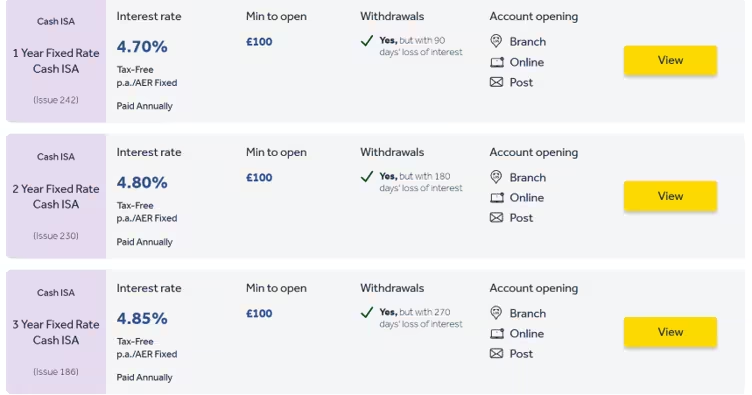
Leeds Building Society’s official Cash ISA comparison table showing current interest rates, minimum opening balances and withdrawal restrictions.
What Does Our Analysis Reveal?
Three findings stand out from the current range.
First, fixed-rate Cash ISAs offer the highest advertised returns. The difference between the one-year rate of 4.70% and the five-year rate of 4.90% is only 0.20 percentage points.
Second, the Online Access Cash ISA at 4.16% is materially more competitive than the standard E-ISA at 1.45%. This makes the exact account name and issue important when comparing products.
Third, accessibility comes at different costs. Fixed-rate accounts permit early withdrawals, but the interest penalties become substantially larger with longer terms.
Our assessment is that savers should choose the account based on the date they might need their money, rather than selecting the highest published percentage alone.
How Do Leeds Building Society Fixed Rate ISA Accounts Work?
A fixed-rate Cash ISA guarantees the advertised interest rate for a defined period. This protects savers from reductions in the interest rate during the fixed term.
Leeds Building Society currently provides four main fixed-term choices, including corresponding monthly-income versions.
1. One Year Fixed Rate Cash ISA – 4.70% AER
The 1 Year Fixed Rate Cash ISA (Issue 242) offers 4.70% AER tax-free, fixed until 30 November 2027.
Its main conditions include:
- Minimum opening deposit: £100.
- Interest: Calculated daily and paid at maturity.
- Early withdrawal: Charge equivalent to 90 days’ interest on the withdrawn amount.
- Additional deposits: Permitted within the stated funding window.
- Deposit deadline: 30 November 2026.
- Opening methods: Online, in branch or by post.
A deposit of £10,000 held for a full year at 4.70% would earn approximately £470 in tax-free interest, assuming the advertised rate and no withdrawals.
Our assessment: This is a practical option for people planning to use their savings within approximately 12 months. It provides certainty without the prolonged commitment associated with three- or five-year products.
2. Two Year Fixed Rate Cash ISA – 4.80% AER
The 2 Year Fixed Rate Cash ISA (Issue 230) pays 4.80% AER fixed until 4 December 2028.
The account requires a £100 minimum balance and allows additional eligible deposits until 4 December 2026.
An early withdrawal or transfer out incurs a charge equivalent to 180 days’ interest on the amount removed.
For a £10,000 opening deposit, the provider’s illustrative two-year return equates to approximately £983 in interest, assuming annual interest is retained and no additional transactions occur.
Our assessment: The two-year account offers a middle ground between return certainty and commitment. It could suit someone saving for a medium-term expenditure, provided that expenditure can be postponed until maturity.
3. Three Year Fixed Rate Cash ISA – 4.85% AER
The 3 Year Fixed Rate Cash ISA (Issue 186) provides a guaranteed 4.85% AER until 3 December 2029.
The product has a £100 minimum opening balance, with new eligible deposits accepted until 3 December 2026.
Interest is calculated daily and paid annually. Savers may choose to retain the interest within the ISA or receive it in another account.
Early withdrawals carry a charge equivalent to 270 days’ interest.
A £10,000 deposit could generate approximately £1,526.70 over three years using the provider’s illustrated annual compounding assumptions.
Our assessment: This product offers a relatively small additional annual return over the two-year alternative. Its suitability therefore depends more on the intended savings timeframe than on the 0.05-percentage-point rate difference.
4. Five Year Fixed Rate Cash ISA – 4.90% AER
The 5 Year Fixed Rate Cash ISA (Issue 181) offers the highest fixed rate in the current range, at 4.90% AER.
The interest rate remains fixed until 1 December 2031, and eligible deposits can be made until 1 December 2026.
Key details include a minimum deposit of £100, interest paid annually and an early withdrawal charge equivalent to 365 days’ interest.
Based on the provider’s illustrative compounded return, £10,000 could grow to approximately £12,702.20 over five years.
The potential disadvantage is that money remains committed for an extended period. An unexpected need for funds could result in a significant penalty.
Our assessment: The five-year product is more appropriate for surplus savings that are genuinely unlikely to be required before December 2031.
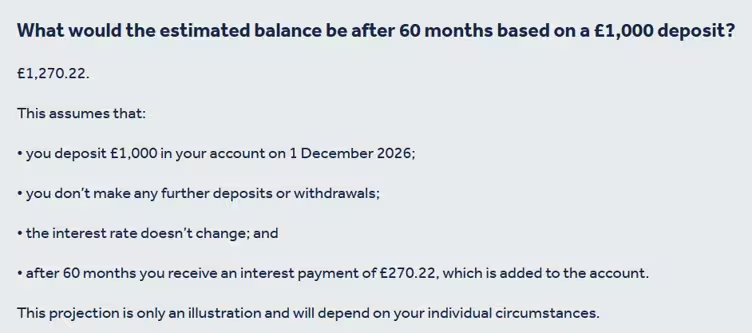
Official five-year fixed Cash ISA showing the 4.90% AER interest rate, December 2031 maturity date and early withdrawal conditions.
How Much Interest Could You Earn With Leeds Building Society?
The amount of interest earned depends on the opening deposit, account rate, holding period, timing of deposits and whether interest remains in the account.
For an initial comparison, our calculations show how different balances could perform over one year.
Estimated Annual Cash ISA Interest
| Initial savings | 4.16% AER | 4.70% AER | 4.90% AER |
| £1,000 | £41.60 | £47 | £49 |
| £5,000 | £208 | £235 | £245 |
| £10,000 | £416 | £470 | £490 |
| £15,000 | £624 | £705 | £735 |
| £20,000 | £832 | £940 | £980 |
| £50,000 | £2,080 | £2,350 | £2,450 |
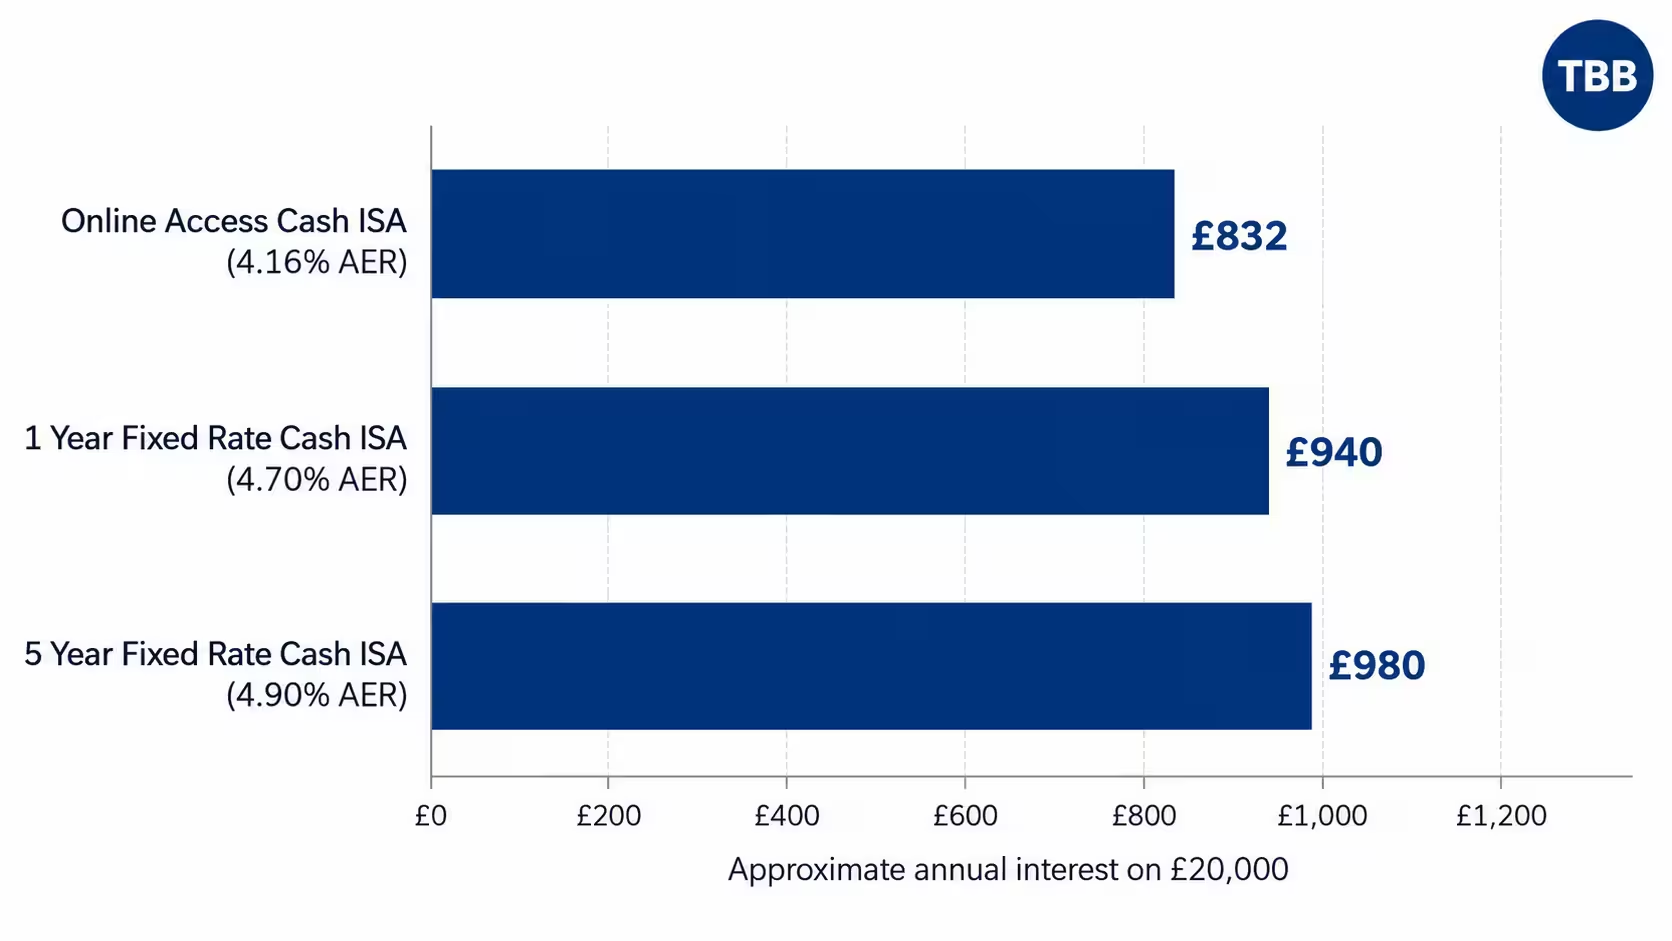
Illustrative annualised interest only. The £1,000 minimum deposit and account-specific eligibility rules still apply. Fixed-term products may not pay interest after exactly one year, and the 4.16% variable rate is not guaranteed.
For someone with £20,000 in savings, the difference between 4.16% and 4.90% is approximately £148 annually.
However, receiving the additional £148 would require accepting the conditions of the five-year fixed product rather than the unrestricted access of the online account.
This illustrates why comparing nominal returns without considering liquidity can produce misleading conclusions.
What Happens When Interest Compounds?
Compound interest occurs when interest is retained within an account and subsequently earns interest itself.
For a £10,000 deposit held for the full relevant fixed term, the published account illustrations produce the following approximate outcomes when interest is retained.
| Fixed term | AER | Estimated total interest | Estimated final balance |
| 1 year | 4.70% | £470 | £10,470 |
| 2 years | 4.80% | £983 | £10,983 |
| 3 years | 4.85% | £1,526.70 | £11,526.70 |
| 5 years | 4.90% | £2,702.20 | £12,702.20 |
These calculations are illustrations, not guaranteed monetary outcomes. Actual payments can vary with deposit dates, account rules and whether interest is paid away.
The five-year return is larger mainly because the money remains invested for longer, rather than because the interest rate is dramatically higher.
Does Leeds Building Society Offer a Monthly Interest ISA?
Yes. Leeds Building Society offers fixed-rate monthly-income Cash ISAs across one-, two-, three- and five-year terms.
These products are designed for savers who want their interest distributed regularly instead of accumulated within the same ISA.
The advertised annual equivalent rates are currently:
| Monthly-income ISA | AER | Interest paid |
| 1 year | 4.70% | Monthly |
| 2 years | 4.80% | Monthly |
| 3 years | 4.85% | Monthly |
| 5 years | 4.90% | Monthly |
The monthly-income accounts have a £100 minimum deposit and early withdrawal penalties corresponding to their fixed terms.
How Much Monthly Income Could £10,000 Generate?
At 4.70% annually, £10,000 would generate roughly £470 over a full year.
That is equivalent to approximately £39 per month on average.
Actual monthly payments vary because interest is calculated daily and payment months contain different numbers of days.
The society’s one-year monthly-income account provides an illustrative payment of approximately £3.92 per month for a £1,000 deposit.
An important restriction is that monthly interest must be paid to another account rather than added to the monthly-income ISA itself.
If that money is paid into an ordinary savings account, subsequent interest earned outside the ISA may be taxable, depending on the saver’s circumstances and allowances.
Our assessment: Monthly-income ISAs can be helpful for people seeking regular income from cash savings. However, someone focused on long-term capital growth may prefer an account that retains interest so it can compound.
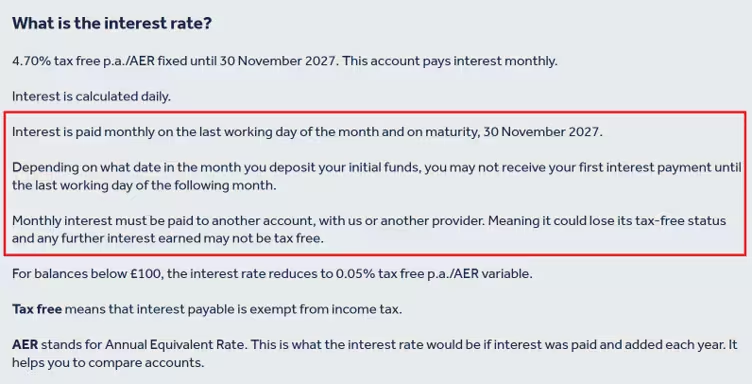
The monthly-income ISA conditions explain when interest is paid and why monthly distributions cannot be reinvested directly into the same account.
What Is the Leeds Building Society Easy Access ISA Rate?
The Online Access Cash ISA (Issue 23) currently pays 4.16% AER tax-free variable.
It allows unlimited withdrawals and online account management, making it more suitable for savings that may be required at short notice.
The opening balance must be at least £1,000.
Other important features include:
- Interest rate: 4.16% AER variable.
- Withdrawal allowance: Unlimited.
- Minimum balance: £1,000.
- Interest payment: At maturity on 30 November 2027.
- Account management: Online only.
- ISA transfers: Accepted subject to product conditions.
- ISA flexibility: The account is not a flexible ISA.
Does the Online Access ISA Have a Fixed Interest Rate?
No. Although the product has a maturity date of 30 November 2027, its interest rate is variable.
This distinction is important.
The maturity date determines when that particular product issue ends. It does not guarantee that the 4.16% rate will remain unchanged until then.
If the society reduces the variable interest rate, the actual return earned over the holding period will also fall.
At maturity, the account balance and interest are scheduled to move to an instant-access Cash ISA maturity account, under the relevant terms.
What Happens if the Balance Falls Below £1,000?
The interest rate falls to 0.05% tax-free variable if the Online Access Cash ISA balance drops below £1,000.
For example, withdrawing £9,500 from a £10,000 balance would leave £500 in the account.
Under the published conditions, that remaining £500 would earn the lower rate rather than the headline 4.16%.
This makes the minimum balance a significant consideration for savers who expect to make large withdrawals.
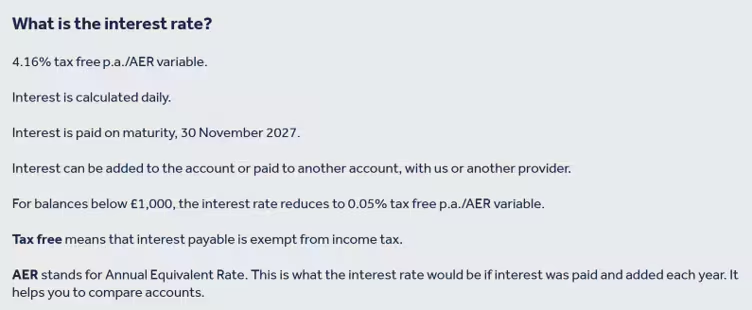
Online Access Cash ISA (Issue 23) paying 4.16% AER variable, with unlimited withdrawals and a £1,000 minimum balance.
Is the Six Access ISA Worth Considering?
The Six Access ISA currently pays 3.10% AER variable and permits up to six withdrawals per calendar year without an interest penalty.
It requires a minimum deposit of £1,000 and can be opened in branch or by post, rather than online.
Interest is calculated daily and paid annually on 28 February.
Exceeding the permitted six withdrawals or transfers results in a charge equivalent to 30 days’ interest on the amount withdrawn.
The account offers a different operational model from the Online Access Cash ISA, particularly for people who prefer branch or postal banking.
However, the Online Access Cash ISA currently offers an interest rate 1.06 percentage points higher while also allowing unlimited withdrawals.
On a constant £10,000 balance, that rate difference represents approximately £106 over a year.
Our analysis therefore suggests that the Six Access ISA has a narrower appeal based on how customers prefer to manage their account rather than purely on financial returns.
What Are the Early Withdrawal Penalties on Leeds Building Society Fixed ISAs?
Early withdrawal charges are among the most important considerations when comparing the society’s fixed-rate products.
Unlike instant-access savings accounts, these products impose a financial charge when money is removed before maturity.
The charge is calculated using a specified number of days’ interest on the relevant amount withdrawn or transferred.
Early Withdrawal Penalty Comparison
| Fixed ISA | Interest rate | Penalty period | Illustrative charge on £10,000 |
| 1 year | 4.70% | 90 days | £115.89 |
| 2 years | 4.80% | 180 days | £236.71 |
| 3 years | 4.85% | 270 days | £358.77 |
| 5 years | 4.90% | 365 days | £490 |
Approximate examples calculated using the advertised annual rates and a 365-day year. Actual charges depend on the product terms and withdrawal circumstances.
A saver withdrawing £10,000 early from the five-year account could therefore face an interest charge of approximately £490.
Importantly, a penalty can exceed the interest earned up to the withdrawal date. The product terms warn that savers could receive less than their original deposit.
How Should Savers Assess These Charges?
Our approach is to compare the potential interest-rate advantage with the cost of losing access to funds.
Consider two choices:
Option A: Keep £10,000 in the Online Access Cash ISA at 4.16% variable.
Option B: Fix £10,000 for five years at 4.90%.
The initial annual rate advantage of Option B is only £74 on a £10,000 balance.
A single early withdrawal penalty could outweigh several years of that additional annual return.
For emergency savings, a variable-rate account with unrestricted access can therefore provide greater practical value even when the advertised interest rate is lower.
Can You Transfer an Existing ISA to Leeds Building Society?
Yes. The society accepts eligible ISA transfers into its Cash ISA products, subject to the individual product’s conditions and funding deadlines.
Transferring an ISA is different from withdrawing the funds into a current account and making a new deposit.
A correctly completed ISA transfer preserves the existing tax-free status of the savings.
How to Transfer an ISA Step by Step?
- Choose a suitable Cash ISA: Compare rates, account issues, withdrawal terms and minimum balances.
- Check your existing provider: Confirm whether any exit penalties or maturity restrictions apply.
- Open the receiving account: Complete the required Leeds Building Society account application.
- Request an ISA transfer: Use the provider’s ISA transfer process rather than withdrawing the savings personally.
- Provide account details: Supply the existing ISA provider’s name and account information.
- Monitor the transfer: Confirm the full amount reaches the new account and that its tax-free status is retained.
The society states that Cash ISA transfers may take up to 15 working days, while transfers involving stocks and shares ISAs can take up to 30 calendar days.
It also states that when transferring an ISA out to another provider, it will transfer the funds within five working days after receiving the new provider’s request.
Does an ISA Transfer Count Towards the Annual Allowance?
An eligible transfer of previous tax-year ISA savings does not normally use the current year’s new subscription allowance.
For example, someone with £35,000 accumulated in Cash ISAs over earlier tax years may be able to transfer that balance into a new eligible Cash ISA, even though the annual contribution allowance is £20,000.
This is different from depositing £35,000 of new savings during one tax year.
The society also requires the full amount subscribed to a Leeds Cash ISA in the current tax year to be transferred when moving those current-year subscriptions.
Readers considering several accounts should understand the wider rules on having more than one ISA, because the general UK rules and an individual provider’s subscription restrictions are not necessarily identical.
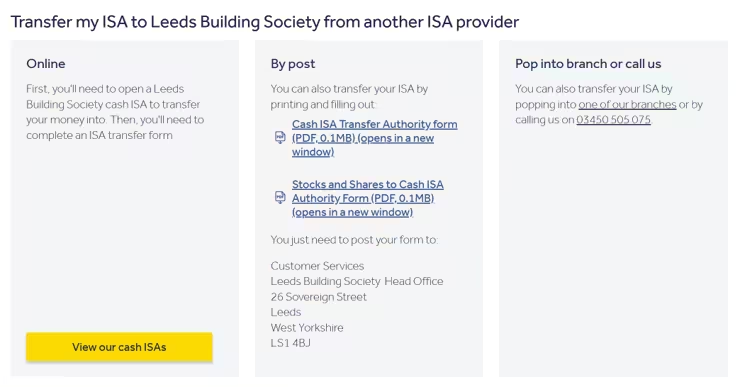
Official ISA transfer guidance explaining how to transfer existing savings without withdrawing the money and losing its ISA protection.
How Will the 2027 ISA Allowance Changes Affect Leeds Building Society Savers?
One of the most important considerations for Cash ISA savers is the change scheduled for 6 April 2027.
For the 2026/27 tax year, eligible adults can subscribe up to £20,000 across their ISAs, subject to the applicable product rules.
From 6 April 2027, the government is introducing a lower Cash ISA subscription limit for investors under 65.
ISA Allowances for 2026/27 and 2027/28
| ISA rule | 2026/27 | From 6 April 2027 |
| Overall annual ISA allowance | £20,000 | £20,000 |
| Cash ISA limit for under-65s | £20,000 | £12,000 |
| Cash ISA limit for eligible savers aged 65 or over | £20,000 | £20,000 |
| Interest on eligible Cash ISA savings | Tax-free | Tax-free |
| Transfers from non-cash ISAs into Cash ISAs for under-65s | Permitted under applicable rules | Restricted under the new rules |
The reduced limit applies to new Cash ISA subscriptions rather than automatically capping the total balance already accumulated from earlier tax years.
For example, someone with £80,000 already sheltered in Cash ISAs does not have to reduce that balance to £12,000 merely because the annual contribution limit changes.
The restriction principally affects how much additional money can be subscribed during future tax years.
It is also important to distinguish an ISA contribution from a valid ISA-to-ISA transfer, while checking the additional restrictions being introduced on certain transfers between ISA types.
Those planning their savings contributions around the tax-year boundary should check when the ISA allowance resets before making deposits.
What Does This Mean for Self-Employed Professionals?
A sole trader may hold personal Cash ISA savings separately from funds reserved for business expenses and tax liabilities.
The 2027 reform makes forward planning important for anyone hoping to shelter more than £12,000 of additional cash savings annually while under 65.
However, ISA limits should not encourage people to lock away money they may need for immediate financial commitments.
For business owners, access to working capital and emergency reserves remains more important than securing a small additional percentage of interest.
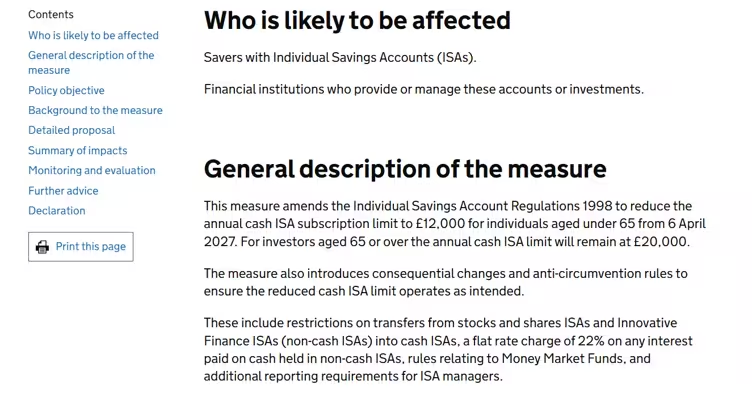
HMRC’s official explanation of the new £12,000 annual Cash ISA limit for under-65s from 6 April 2027, while the overall ISA limit remains £20,000.
Is Leeds Building Society Better Than Other ISA Providers?
Whether Leeds Building Society is the best option depends on the type of account, required access and rates available elsewhere.
In reviewing UK Cash ISA comparisons, we found that headline interest rates can differ considerably between major banks, building societies and specialist savings providers.
Some competing products advertise higher rates but may require additional conditions, such as promotional bonuses, limited deposits, specific access methods or restrictions on ISA transfers.
Which ISA Providers Should You Compare?
| Provider | Relevant comparison | What to check |
| Leeds Building Society | Fixed and variable Cash ISAs | Maturity dates, withdrawal penalties and account issues |
| Nationwide | Fixed and limited-access ISAs | Account eligibility and withdrawal restrictions |
| Virgin Money | Fixed and variable ISA products | Promotional conditions and applicable interest rates |
| Halifax | Fixed, variable and limited-access accounts | Interest payment frequency and access |
| Santander | Fixed-rate and other Cash ISA choices | Product availability and account-specific conditions |
The precise ranking changes as providers introduce new product issues or amend variable rates.
For example, comparing Nationwide ISA rates is useful when evaluating building society products, particularly for people deciding between fixed returns and restricted withdrawals.
Similarly, savers looking at Virgin Money’s ISA options can assess whether a different interest rate or account structure better meets their requirements.
Established banks also provide alternatives. Comparing Halifax ISA accounts alongside the available Santander Cash ISA products can help identify differences in account access, minimum funding requirements and fixed-term commitments.
These comparisons should always use rates checked on the same date.
How Much Difference Does a Higher Competitor Rate Make?
Consider a competitor offering 5.00% AER compared with an account paying 4.70%.
The difference is 0.30 percentage points.
On £20,000, that represents approximately £60 in additional interest over a full year, assuming a constant balance and unchanged rates.
On £50,000, the difference would be approximately £150.
These figures illustrate why comparing providers is worthwhile, but they do not establish that the hypothetical 5.00% account is available or appropriate.
A small improvement in interest may not compensate for extra access restrictions, additional fees or complicated promotional conditions.
Our view is that savers should compare the effective return after relevant costs, rather than selecting the product displaying the largest number.
Is Leeds Building Society Safe for Cash ISA Savings?
Leeds Building Society is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority.
Eligible deposits are protected under the Financial Services Compensation Scheme.
The standard FSCS deposit protection limit increased to £120,000 per eligible person, per authorised firm on 1 December 2025.
This protection generally applies to the combined qualifying deposits held with the same authorised institution, rather than a separate £120,000 allowance for each individual account.
For example, a customer with £80,000 in a Leeds Cash ISA and £50,000 in another eligible Leeds savings account would hold £130,000 in combined deposits.
Under the standard protection limit, £120,000 would be covered and the remaining £10,000 would fall outside that ordinary limit, subject to any applicable special protections.
Certain temporary high balances arising from qualifying life events may benefit from additional protection.
Does the FSCS Guarantee the ISA Interest Rate?
No. FSCS protection relates to eligible deposits if an authorised financial institution fails.
It does not protect savers against a normal reduction in the interest rate of a variable savings account.
Nor does it eliminate the contractual withdrawal penalties attached to fixed-rate products.
Our analysis therefore separates three different considerations: the security of eligible deposits, certainty over the advertised interest rate, and access to the savings.
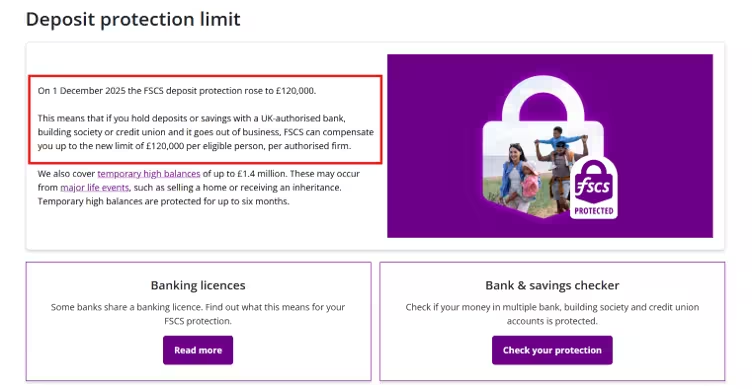
FSCS confirmation that eligible deposits are protected up to £120,000 per person, per authorised firm.
What Are the Advantages and Disadvantages of Leeds Building Society Cash ISAs?
No single Cash ISA will suit every saver. Our evaluation identifies several strengths and limitations within the available range.
Main Advantages
- Competitive fixed returns: The current fixed-rate range offers between 4.70% and 4.90% AER.
- Low fixed-account entry point: A £100 opening requirement makes fixed-rate products accessible to savers without substantial initial deposits.
- Tax-free interest: Qualifying Cash ISA interest remains outside ordinary Income Tax on savings.
- Multiple fixed terms: Customers can choose between one, two, three and five years.
- Monthly-income options: Separate products cater to savers requiring regular income.
- ISA transfer support: Eligible existing ISA balances can be transferred while preserving their tax-free status.
- FSCS protection: Eligible deposits benefit from statutory protection within the applicable limit.
Main Disadvantages
- Early withdrawal costs: Fixed-rate products impose penalties ranging from 90 to 365 days’ interest.
- Variable-rate uncertainty: The 4.16% Online Access Cash ISA rate can change.
- Minimum balance restrictions: Higher-rate accounts may drop to 0.05% interest if balances fall below the required minimum.
- Non-flexible ISA structure: Withdrawn funds cannot simply be replaced without the normal subscription implications.
- Limited funding windows: Fixed-rate account issues close to additional deposits on specified dates.
- Account-management differences: Some products require online operation, while others use branch or postal services.
- Maturity monitoring: Savers need to review the replacement account and interest rate when a product matures.
Our evaluation suggests that the society provides a broad range of cash savings products, although savers need to pay close attention to terms that are less prominent than the headline rate.
How Do We Rate Leeds Building Society ISA Accounts in 2026?
We assessed the current ISA range using five criteria: published rates, account accessibility, entry requirements, security arrangements and clarity of product conditions.
The scores below are our editorial assessments out of 100, not customer-survey results or independently audited performance statistics.
Our ISA Review Ratings
| Evaluation category | Editorial rating | Assessment |
| Interest-rate competitiveness | 86% | Strong fixed-rate choices |
| Access and withdrawal flexibility | 68% | Penalties reduce flexibility |
| Minimum deposit and eligibility | 83% | Accessible fixed-rate entry requirements |
| Deposit protection and regulation | 95% | Established regulatory and FSCS framework |
| Product terms and transparency | 75% | Detailed terms require careful review |
Overall editorial rating: 81% – Good
The overall score reflects a weighted editorial assessment, giving particular importance to interest rates and access conditions. It should not be interpreted as an official customer satisfaction rating.
Our analysis places the greatest strength of Leeds Building Society’s ISA offering in its combination of fixed-rate choices and relatively low opening deposits.
The principal weakness is the trade-off between higher returns and meaningful restrictions on accessing money.
Which Leeds Building Society ISA Is Best for Different Savers?
Rather than recommend one product to every reader, we compared the accounts against common savings objectives.
| Savings objective | Account worth considering | Main reason |
| Emergency fund | Online Access Cash ISA | Unlimited access |
| Money needed in about one year | 1 Year Fixed Rate Cash ISA | Shorter fixed commitment |
| Medium-term savings | 2 Year Fixed Rate Cash ISA | Fixed interest over two years |
| Longer-term savings | 3 Year Fixed Rate Cash ISA | Multi-year rate certainty |
| Surplus savings for five years | 5 Year Fixed Rate Cash ISA | Highest listed fixed rate |
| Monthly income requirement | Fixed Rate Monthly Income Cash ISA | Regular interest payments |
| Branch or postal account management | Six Access ISA | Non-online account operation |
Should Business Owners Use a Personal Cash ISA?
A Cash ISA is a personal savings product rather than a business bank account.
A self-employed individual may choose to allocate eligible personal funds to a Cash ISA, but a limited company cannot use an individual’s ISA as a substitute for a company savings account.
Our financial assessment suggests that business owners should separate money into operational reserves, tax provisions and longer-term personal savings before selecting an ISA.
For example, funds required to meet VAT payments, supplier invoices or payroll should not ordinarily be committed to a fixed product carrying early withdrawal charges.
The potential interest advantage may be modest compared with the cash-flow consequences of losing access to essential funds.
Should You Choose a Fixed or Variable ISA?
A fixed-rate ISA is generally better aligned with a defined savings horizon and a preference for predictable returns.
A variable-rate ISA provides more scope to respond to changing financial circumstances, although the interest rate itself is uncertain.
In practice, many savers may benefit from keeping emergency money accessible while allocating only genuinely surplus funds to longer fixed-term accounts.
The right allocation depends on existing financial commitments, available emergency reserves and tolerance for restricted access.
How Can You Open a Leeds Building Society Cash ISA?
The application process depends on the selected product and the permitted account-opening methods.
The Online Access Cash ISA is opened online, while fixed-rate Cash ISAs can generally be opened online, in branch or by post.
Applicants must normally be at least 18 and meet the relevant UK residency or qualifying Crown employment conditions.
What Should You Check Before Applying?
- Account issue: Confirm the current issue number matches the advertised rate.
- Minimum deposit: Ensure the intended opening amount meets the product requirement.
- Funding deadline: Check the last date on which additional eligible money can be added.
- Withdrawal rules: Review charges and access restrictions before committing.
- ISA allowance: Calculate subscriptions already made during the tax year.
- Transfer eligibility: Confirm that any previous ISA can be transferred into the selected product.
- Maturity arrangements: Understand what happens to the balance when the account ends.
Customers should read the Summary Box and product terms before completing an application.
What Mistakes Should You Avoid When Choosing an ISA?
Our analysis identified several avoidable mistakes that can undermine Cash ISA returns.
- Choosing the highest percentage without checking the term: A five-year product may pay more than an access account but could be unsuitable for money required in the near future.
- Ignoring the minimum balance: A withdrawal that leaves a higher-rate account below its required minimum can substantially reduce the interest earned on the remaining money.
- Using an outdated product issue: ISA providers frequently replace account issues. A rate advertised several days earlier may apply to a product no longer available for new applications.
- Confusing the maturity date with a rate guarantee: A variable-rate ISA can mature on a specified date without fixing the interest rate for that entire period.
- Withdrawing money instead of arranging an ISA transfer: This can remove savings from the ISA wrapper and create unnecessary subscription complications.
- Failing to compare competing offers: Even differences of 0.20 or 0.30 percentage points can become financially significant on larger balances.
- Forgetting to review maturity instructions: Money transferred automatically into a maturity account may receive a different rate from the original fixed product.
Savers who address these issues are better positioned to compare accounts on their full economic value rather than their headline advertising.
Are Leeds Building Society ISA Rates Worth It in 2026?
Leeds Building Society offers a credible range of Cash ISA options, particularly for savers prioritising fixed interest rates and relatively low minimum opening deposits.
Its current five-year fixed rate of 4.90% AER is the highest in the published range, while its one-year product provides 4.70% AER with a much shorter commitment. The Online Access Cash ISA at 4.16% variable offers an alternative for customers who need access to their savings.
The central financial consideration is not whether 4.90% exceeds 4.16%. It is whether the additional potential interest compensates for the restrictions and risks associated with a longer fixed term.
Our review also highlights the importance of the April 2027 Cash ISA reforms. Savers under 65 who plan to make substantial new cash subscriptions should understand the reduced annual limit and the distinction between new contributions and qualifying transfers.
Our overall assessment is that Leeds Building Society is worth considering, but its strongest account for an individual saver depends on their available balance, financial objectives and need for access.
Comparing equivalent products across multiple providers remains essential before making a decision.
Frequently Asked Questions
1. What is the highest Leeds Building Society ISA rate in 2026?
The highest listed rate is 4.90% AER tax-free on the 5 Year Fixed Rate Cash ISA (Issue 181), as checked on 13 October 2026.
2. What is the Leeds Building Society one-year ISA rate?
The 1 Year Fixed Rate Cash ISA (Issue 242) currently pays 4.70% AER tax-free, fixed until 30 November 2027.
3. Can I withdraw money from a Leeds Building Society fixed ISA?
Yes, but early withdrawals and transfers incur a charge of between 90 and 365 days’ interest, depending on the fixed term.
4. Does Leeds Building Society offer an easy access Cash ISA?
Yes. Its Online Access Cash ISA (Issue 23) pays 4.16% AER variable and permits unlimited withdrawals, subject to account conditions.
5. Is Leeds Building Society covered by FSCS protection?
Yes. Eligible deposits are protected up to £120,000 per person, per authorised firm under the current standard FSCS limit.
6. Can I transfer an existing Cash ISA to Leeds Building Society?
Yes, eligible ISA transfers are accepted subject to the receiving account’s conditions. Use the formal transfer process to preserve ISA tax benefits.
7. Will the Cash ISA allowance change in April 2027?
Yes. From 6 April 2027, the annual Cash ISA subscription limit for savers under 65 reduces to £12,000, while eligible savers aged 65 and over retain a £20,000 Cash ISA limit.
More in Finance & Tax
Best 1 Year Fixed Rate ISA UK 2026: Top Cash ISA Rates Compared
The best 1 year fixed rate ISA in the UK currently pays up to 4.98% AER tax-free, with UBL UK offering the highest verified rate in our October 2026 comparison. Shawbrook Bank follows at 4.97%, while Vanquis Bank offers a competitive 4.96% alongside a lower minimum opening deposit. However, choosing the best one-year fixed Cash […]
Moneybox Lifetime ISA Review 2026: Interest Rates, Bonuses, Fees and Is It Worth It?
The Moneybox Lifetime ISA is a UK savings and investment account designed to help eligible adults save for their first home or retirement. It offers a 25% government bonus on contributions of up to £4,000 each tax year, potentially adding £1,000 annually to a saver’s money. Moneybox offers both Cash and Stocks & Shares Lifetime […]